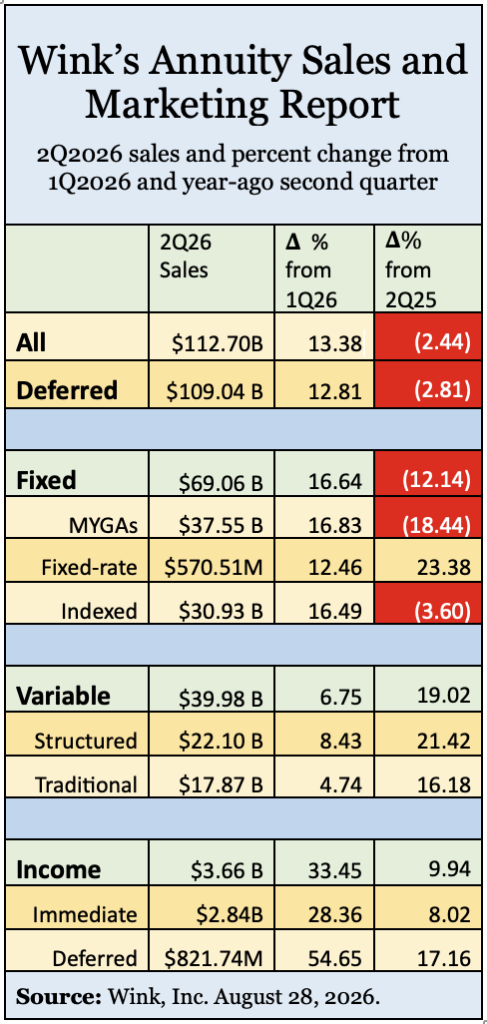

This quarter marked some substantial sales improvements from last quarter. The fall of indexed annuity sales in 2Q2026 was tough, but it didn’t have quite the same sting as the drop in multi-year guaranteed annuity (MYGA) sales for the quarter.
Every line of business experienced an increase in sales, relative to 1Q2026. Indexed annuity and MYGA volumes were down, however, when compared to this quarter, last year. There were 44 negative rate adjustments during quarter two, compared to 112 at this time last year.
Multi-year guaranteed annuities, fixed annuities and indexed annuities’ sales were directly impacted with those negative rate adjustments. The end result? Forty-one percent of annuity participants experienced declines over 1Q2026 sales, and 39% of participants experienced declines over 2Q2025. Overall, annuity sales were up over 13% from last quarter, but down over 2% from this time in 2025. We anticipate that annuity sales will fall short of 2025 levels this year.
Deferred annuities experienced much of the same, relative to all annuities. Rates are relatively good, but that isn’t enough to get agents off the beaches and into their offices to sell more annuities. The summer is always a challenging quarter, as far as sales go.
That said, sales of all deferred annuities increased nearly 13% from last quarter but dropped by nearly 3% when compared to this time, last year. The MYGA line of business was up nearly 17% from 1Q2026—and that’s great. However, sales were also down on these commoditized products- over 18% from 2Q2025.
One-year guarantee fixed annuities increased over 12% from last quarter and over 23% from this time, last year. That said, it is easy to beat a benchmark that is already low to begin with. Indexed annuities increased sales more than 16% from the prior quarter, but down nearly 4% from this time last year. Next quarter should be an improvement.
Structured annuities (Registered Indexed-Linked Annuities, or RILAs) shined this quarter with an increase in sales exceeding 8% from last quarter. Those offering the newest type of deferred annuity are killing it, and it shows; sales were up over 21% from 2Q2025. There is no questioning that structured annuity sales will set another record in 2026.
And variable annuities…they are steadily on the rise. Sales levels were up nearly 5% from last quarter and up more than 16% versus this period, last year. Income annuities of the immediate kind had a great quarter with a 28% increase from 1Q2026 and an 8% thrust forward from this period, one year ago.
Deferred income annuities’ growth would be remarkable if sales weren’t so low to begin with. The 55% increase in sales of DIAs from last quarter is a roadmap for others to follow. With sales up 17% from 2Q2025, it isn’t a bad time to be selling these guaranteed lifetime income instruments.
Although rates on MYGAs have not been as attractive as they were a few years ago, they improved from last quarter, which set MYGAs up for a “win.” Sales levels improved nearly 17% from the previous quarter, although MYGA sales were down more than 18% from this time in 2025. Fifty percent of the top ten companies experienced challenging MYGA sales, relative to 1Q2026.
As for sales compared to this time last year, the biggest company in annuity sales increased its own sales nearly 150% from the prior 2Q, which softened the blow on the sales declines from this time in 2025. While it is tough to feel confident in any sales forecasting when there is talk of inflation, changing the Fed Funds Rate, the increasing cost of oil—it all looks like MYGA sales will come up short this year, despite continued lack of competitiveness against Certificate of Deposit (CD) rates.
Fixed annuities with a one-year guaranteed rate had some positive momentum with their sales in second quarter. However, we are talking about a product line that cannot break $600 million in a quarter. Ultimately, sales of traditional fixed annuities were up more than 12% from last quarter and up more than 23% from this same quarter, one year ago.
Having the top carrier in the space increase this quarters’ sales well into the triple digits (from this time last year) certainly helps when other companies are having a tough time closing sales due to the rate environment. We still anticipate that this product line will have an increase in sales for 2026, topping the previous year’s levels modestly.
Fixed indexed annuities
Sales of indexed annuities haven’t been this high for a couple of quarters. An increase of more than 16% left the product line sitting pretty, but then sales dropped almost 4% from the same period, a year prior.
When evaluating the top ten best-selling indexed annuity companies, one cannot help but notice the huge sales increase that the top seller had over 1Q2026. However, a comparison against indexed annuity sales last year illustrates that 60% of the top ten players had mostly double-digit losses. We are anticipating that indexed annuity sales will be down considerably for all of 2026.
Structured and traditional variable annuities
The darling of the deferred annuity market is still chugging along, making impressive increases in sales levels, while still maturing as a product line. Impressive rates on structured annuities have helped buoy these products to increases of 8% over 1Q2026 and a huge leap of more than 21% when compared to this time, last year.
When evaluating how structured annuity sales fared, relative to the previous quarter, you would be remiss to overlook the fact that only 21% of carriers in the market experienced a loss in sales. Perform that same exercise, but with sales during this time, one year ago, and only 16% of product manufacturers experienced a loss in structured annuity volumes. This was a record-setting quarter for structured annuity sales, topping the prior 4Q2025 record by 3.51%. There is no question that 2026 will set a record for structured annuity sales.
What happens when the stock market is on the rise? Variable annuity (VA) sales fare well. This quarter was no exception to that rule, with VAs clocking a nearly 5% increase in sales from the prior quarter and a jump of more than 16% from this time, last year.
Note that only 65% of participants had sales climb compared to 1Q26 and nearly half of those reporting sales experienced a decline from this quarter, last year. While many are discussing a market correction, it seems logical that sales of VAs will fall. However, for now the market still seems to be upward trending, which will no doubt result in VAs closing out the year better than 2025, but by a small margin.
Like MYGAs, single-premium immediate income annuities (SPIAs) are commoditized. When the payout is great, the sales will follow. And payouts must be good because immediate income annuities experienced more than 28% growth over the last quarter and more than an 8% progression when measured against last year, same quarter.
The amazing part? More than 40% of participants experienced sales declines, when compared to 1Q2026. Thanks in large part to the number one seller of immediate income annuities, these products will likely sell more than they did in 2025, but not by much.
Deferred income annuities (DIAs) had a great quarter, despite the fact that 61% of participants experienced a drop in sales from last quarter. That said, nearly a quarter of the companies offering these products had triple digit increases in sales from Q1. Just the two top sellers of the product line had such substantial increases in sales that they effectively canceled-out the sales declines from other carriers.
And while evaluating the nearly 55% sales surge from last quarter, one needs to remember that we are reviewing a product offering that cannot keep pace and seems to wane a little more each year. Wink projects that DIA sales will be up for 2026, but certainly will not set any records.
© 2026 Wink, Inc. Reprinted by permission of the author.