Archives: Articles

IssueM Articles

Shorts Reveal Jackson National’s Journey toward ‘Bermuda Triangle’

QVT Financial, an investment firm, is shorting Jackson Financial’s (NYSE: JXL) stock. Jackson Financial is the parent of Brooke Life, which is now the parent of Jackson National Life, the largest issuer of traditional variable annuities in 2025 and the fifth-largest issuer of structured variable annuities (“RILAs”), according to LIMRA.

“As of the date of this article, accounts managed by QVT Financial LP… hold short positions in the debt and equity securities of JXN, including through derivatives,” the asset manager wrote in its September 17 report.

Since 2021, when Jackson Financial separated from Prudential Plc and went public, its share price has climbed from $25 initially to about $130. During that rise, Jackson Financial spent more than $1 billion buying back its stock from shareholders.

Where did that money come from? According to QVT, Jackson National Life found it by booking, as an asset, the present value of rider fees that it expects to receive from owners of its variable annuities with guaranteed minimum withdrawal benefits (GMWBs).

Jackson Financial’s share price history since going public, from Reuters.

Under SAP accounting standards, which life insurers use, Jackson National couldn’t book that asset without capitalizing the risk that VA/GMWB owners might lapse their contracts and stop paying rider fees. To manage the pain of that expense, Jackson Financial set up Brooke Re, a captive insurer in Jackson’ home state of Michigan.

Regulators in Michigan allowed Brooke Re to use less-conservative GAAP accounting instead of life insurers’ required SAP accounting. Brooke Re would not need as much capital as Jackson would for the same liability—and “release” capital that Jackson Financial could use elsewhere.
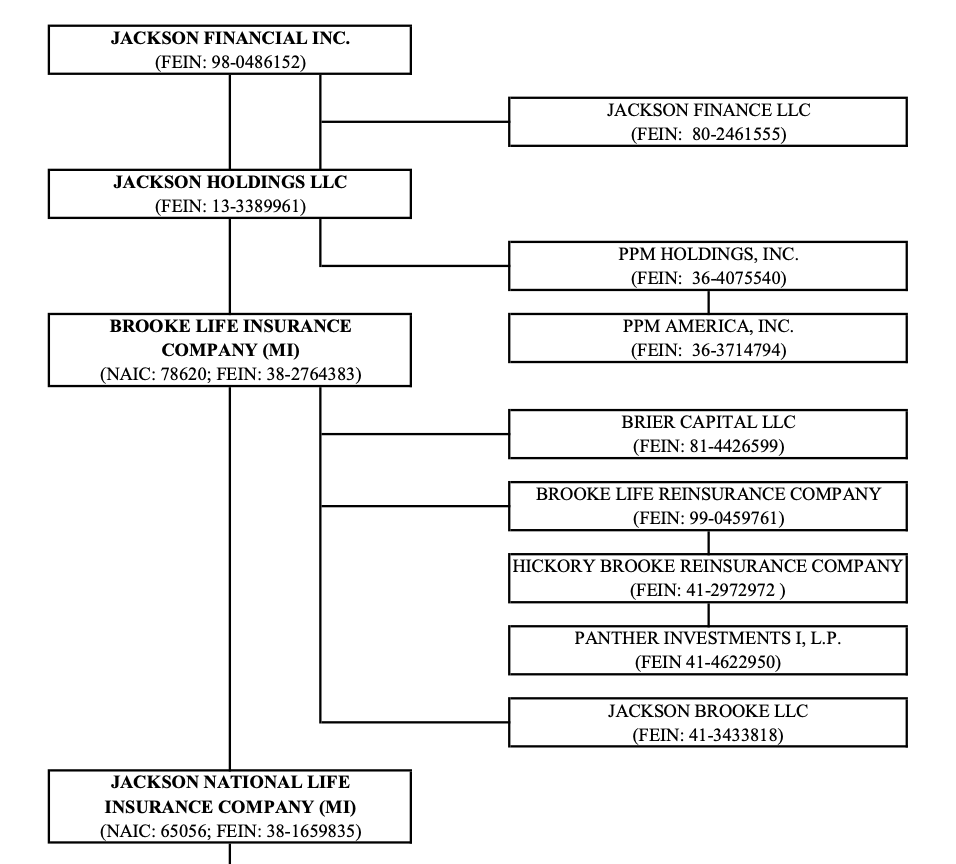
“This permitted practice… increased capital and surplus by $1,348,933,927 and $848,933,927 as of June 30, 2026 and December 31, 2025, respectively,” Jackson National described the arrangement in its 2Q26 state filing. [Jackson explored the possibility of creating an affiliated reinsurer in Bermuda before deciding on a Michigan captive, RIJ was told by someone familiar with that effort.]

QVT isn’t buying it. The investment company says this arrangement gives Jackson capital to support an aggressive share buyback program but leaves Brooke Re underfunded—and perhaps unable to fully reimburse Jackson National in the event of a wave of contract lapses and a write-down in the PV of future fee revenue. So the company, led by Arthur Chu, who has a masters in physics from Harvard, is shorting Jackson Financial’s stock.

“The Brooke Re transaction transferred the bulk of the risk in JNL – the variable annuity market guarantees and their hedges – but only a small fraction of the assets. Brooke Re began with only $700MM of hard assets to hedge a ~$175B variable annuity book. …We calculate that Brooke Re has less than half the liquid assets needed to service its payable to JNL and insufficient capital for the risks it assumed… If Brooke Re cannot service this receivable, JNL will face a significant capital deficit,” said QVT’s white paper.

“In order for public shareholders to receive the capital generated by JNL, JNL first pays dividends to its owner Brooke Life; Brooke Life passes some or all of these proceeds to its owner JXN; these proceeds are then passed to shareholders.”

Is this a problem?

At least one stock analyst thinks so. “One of the questions that we get most often from investors is how do you get comfort that Brooke Re is well capitalized?” Jefferies’ Suneet Kamath asked on a call discussing Jackson’s 2024 results, noting “some reluctance in terms of providing additional disclosure,” according to a report on this matter in Hunterbrook media.

But annuity industry veterans aren’t giving up on Jackson National. “Is this a problem? I’m not sure,” said Larry Rybka, CEO of Valmark Securities, an Akron, Ohio-based independent broker-dealer, in an email to RIJ.
“If it is, the scale of the problem doesn’t approach that of fixed annuity writers that are private equity-owned. As a public company, Jackson has different goals and constraints. At least the Jackson policyholders have their sub-account values. It is also audited by a Big Four accounting firm.”

Bobby Samuelson, publisher of Life Product Review and CEO of Illustra, an illustration tool for life/annuity companies, agreed. “VA with GLWB is one of the most complex liability structures ever written at scale by the insurance industry. There’s a built-in mismatch between GAAP and Stat accounting that every publicly-traded carrier has to manage. This just seems like a mechanism to smooth the results,” he told RIJ.

Jackson, which didn’t respond to my email query, appears to be spreading the cost of hedging the lapse risk over several years, rather than capitalizing it all at once. That strategy is similar to the way life insurers deal with the cost of the up-front commissions (“deferred acquisition costs,” or DAC) that they pay third-party agents and advisers.

“It’s similar to DAC,” an actuary told RIJ. “They’re asking regulators, ‘Why do you allow me to capitalize that under SAP and not this? Both are dependent on the same fee stream.’”

QVT seems to be saying that Jackson National is capitalizing Brooke Life Re in the skimpy way that credit cardholders make minimum monthly payments while their account balances compound at high rates of interest. In that view, the liability just gets uglier, like the painting of Dorian Gray in Oscar Wilde’s 1891 novel.

Here’s how Jackson Financial’s August 2026 investor presentation slide described its hedging strategy.

Is Jackson National a ‘Bermuda Triangle’ life insurer?

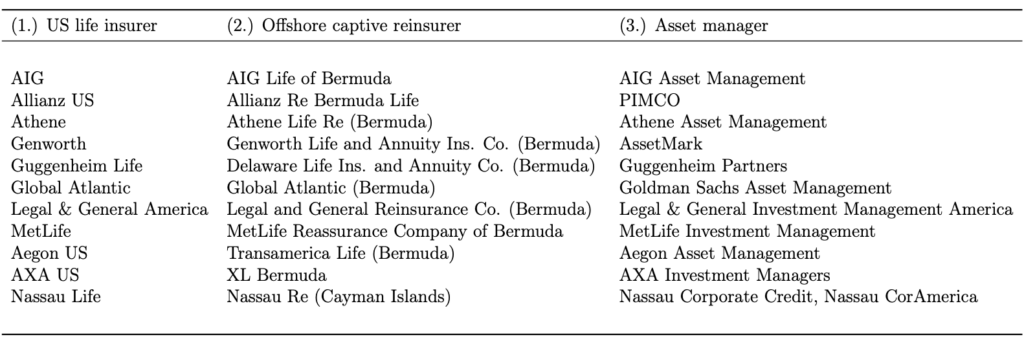
This controversy suggests that Jackson National is adopting the Bermuda Triangle strategy, including its three key elements. That strategy requires a U.S. life insurer, an affiliated reinsurer able to use GAAP accounting, and an affiliated asset manager with private credit chops.

Jackson Financial started out with the first element. It added the second element in 2024. And it added the third element ten months ago.

Last January, Jackson Financial agreed to a long-term strategic investment management partnership with TPG, an alternative asset management firm that’s trying to build its private credit business. According to a release, TPG will manage “a minimum commitment of $12 billion of AUM for Jackson,” with incentives to reach $20 billion.” TPG will focus on investment grade asset based finance (ABF) and direct lending.

Simultaneously, TPG invested $500 million in Jackson, about 6.5% of the insurer. Jackson will receive $150 million of TPG stock at the market price. Jackson could receive additional shares if TPG’s mandate reaches $20 billion.

Does this deal make Jackson Financial, Jackson National and Brooke Re a Bermuda Triangle “flywheel” company (McKinsey’s name for the Bermuda Triangle), like Apollo, Athene and Athene Re?

There are significant differences. Athene is a “PE-led” insurer. Its private equity owner is Apollo, which created Athene in 2009 to take advantage of asset fire-sales at annuity issuers like Jackson National. Athene sells deferred fixed-rate and fixed indexed annuities. It is regulated by the state of Iowa. Its products are distributed insurance licensed advisers and agents via independent marketing organizations. Athene’s core mission is apparently to buy high-yield private market assets that Apollo, as SEC-regulated public company, originates.

Jackson National, created in 1961, is an insurer-led insurer. Its primary product is annuities, not private market assets. Jackson Financial is a public company that reports to the SEC, but Jackson National Life, the operating company, is regulated by the state of Michigan. It sells variable annuities (traditional and, increasingly, RILAs). They are SEC-registered annuities, distributed by SEC-regulated broker-dealers and sold by registered brokers and advisers.

There’s a significant difference in the way Athene and Jackson National have used affiliated reinsurance to date. For instance, in the chart below, note that Athene uses ceded reinsurance to greatly reduce the amount of new liabilities (and thereby lower required capital) associated with its annuity sales. Jackson National does not appear to.

But there is a similarity between Jackson National (and other RILA issuers) and Bermuda Triangle companies, and it’s an important one. RILAs and FAs are both general account products. Confusingly, RILA assets are described as “non-insulated” separate account assets in Jackson National’s 2Q2026 state filing (p. 7.16). Either way, the RILA issuer, not the contract owner, decides how to invest the underlying reserves. Below: a Jackson Financial August 2026 investor-day slide depicting the company’s retooling since its separation from Prudential Plc five years ago.

So Jackson can invest at least some of the reserves backing its RILAs—its future flagship—in private market assets that TPG or other alt-asset managers bring to it. In transitioning from a traditional VA separate account company to a RILA general account (or uninsulated separate account) annuity issuer, Jackson National plants at least one foot in the Bermuda Triangle.

If so, then Jackson Financial’s senior management may be playing a longer game than QVT, with its short position, seems to think.

© 2026 RIJ Publishing LLC. All rights reserved.
State guaranty funds are imperfect safety nets

Two weeks ago we visited the question of moral hazard as it pertains to state guaranty associations (SGAs). We considered the advisability of buying (or recommending) fixed deferred annuities with superior yields from life insurers with inferior strength ratings and/or short track records.

One adviser had asked me: Why shouldn’t my client do that, given the safety net provided to annuity owners by SGAs and assuming that the premium was within the state’s coverage limit?

Several good reasons exist to avoid that, RIJ has been advised:

  • Insolvencies can take years to resolve. Your clients may not get their money back quickly. Attorneys, accountants, and actuaries may struggle over who gets paid how much out of the carrier’s remaining assets. If the owners of the insurer oppose the declaration of insolvency, the contract owners may not recover their savings for years. Clients can’t necessarily afford to wait that long.
  • In the case of single-premium immediate annuities in the payout stage, the calculation of covered benefits requires estimating a present value of future benefits. That depends on the age(s) of the contract owner(s).
  • Other factors contribute to delays. SGAs have no pre-funded reimbursement funds. Insolvent carriers will likely have sold contracts or policies in many states, then the state leading the insolvency has to ask for proportionate amounts of money from surviving insurance carriers in each of those states.
  • Once a carrier is in liquidation, contracts or policies earn a maximum interest rate based on an aggregate rate established by a ratings agency. That’s usually less than competing carriers pay on similar contracts. Thus, if an annuity matures during liquidation, it will [could?] rollover into a sub-optimal rate. At least some states can choose to lower the contractual rate on an annuity contract in liquidation if they consider it unreasonable. Carriers can’t offer unreasonable rates to preempt a state’s reduction.
  • Annuity contract owners may not get all their premium back. The principal [current account value] for deferred fixed-rate or fixed indexed annuities in the accumulation stage are covered by the guaranty associations up to about $250,000 per contract ($500,000 if jointly owned). The exact amount varies from state to state.  For SPIAs it is the present value of $250,000. For amounts over the limit, the contract owner becomes a creditor of the insolvent company.
  • The assets of variable annuities reside in separate accounts, beyond the reach of creditors. But SGA protection of the values of income riders (“living benefits,” or “guaranteed minimum withdrawal benefits”) on variable or fixed-indexed annuities is still unclear.

While the account value of a variable annuity is in a separate account, the guarantees on living benefits are backed by the carrier’s general account. No insurer that sold these products has become insolvent yet. So processes and outcomes haven’t been established.
(Given how heavily the costs of maintaining large blocks of VA/GMWB business weighed on many carriers after 2008, that’s remarkable.)

Bottom line: Why lose sleep for, say, half a percentage-point more yield? Over five years (1,825 nights), a $100,000 contract at 5.5% gains $30,696 while a 5% contract gains $27,628. You’re gaining less than $2 per night. Why disturb any sleep to “save” $600/year?

“You can roll the dice and bottom-feed for the best rate,” one knowledgeable SGA observer told RIJ, “but the odds of things turning out badly are likely not worth the extra interest.”

The buyer of a fixed deferred annuity that offers a higher yield (or a high crediting formula) is, in effect, buying a cheaper product. If people were about to spend six figures on a luxury car, would they, as a rule, choose the one that’s a few thousand dollars cheaper?

© 2026 RIJ Publishing LLC. All rights reserved.
Three Solutions for Social Security’s Shortfall

What will happen, can happen, or should happen when the Social Security trust fund becomes technically insolvent in the early 2030s? This month, we present three recent research papers that attempt to answer those questions.

Two of the three papers come from scholars of the American Enterprise Institute, via The Journal of Retirement. A third comes from a retired actuary and Certified Financial Planner who frames Social Security through the lens of Modern Monetary Theory.

None of these papers calls for a change in Social Security’s basic payroll-tax-fund structure. The first two recommend cutting benefits on the “rich” rather than explicitly raising anybody’s taxes. The third paper suggests the creation of a voluntary national defined contribution plan in addition to Social Security.

“A Simple Plan to Address Social Security Insolvency,” Andrew Biggs and Kristin Shapiro. The Journal of Retirement, Fall 2025.

“The question that is truly at stake in Social Security reform: Should we increase taxes to maintain full benefits for high-income retirees?” Andrew Biggs of the American Enterprise Institute and his co-author, Kristin Shapiro, of Cleveland law firm Baker Hostetler, write.

They recommend capping the Social Security benefit at about $2,050 (in 2024 dollars) a month. People currently receiving less than that amount would still receive all of their promised benefits, but nobody would receive more. That would reduce expenses by 21% and the program wouldn’t be guilty of paying out benefits in excess of its revenues.

In the event that Congress couldn’t solve the problem before Social Security’s trust fund went into deficit, the president could step in, Biggs and Shapiro write. No law would require him to reduce everybody’s benefits by the same percentage. “The President could… choose to create reasonable criteria that would focus the necessary benefit reductions on the retirees who are most able to absorb them.”

This method wouldn’t raise taxes, they say. It wouldn’t reduce benefits for the neediest 80% or pitch anyone into poverty. It wouldn’t even hurt the wealthiest 10% of beneficiaries because they currently rely on their benefits (~$43,000, on average) for only 10% of their retirement income. He considers the possibility that those who lose benefits might sue for them, but believes, based on legal precedent, that they would lose.

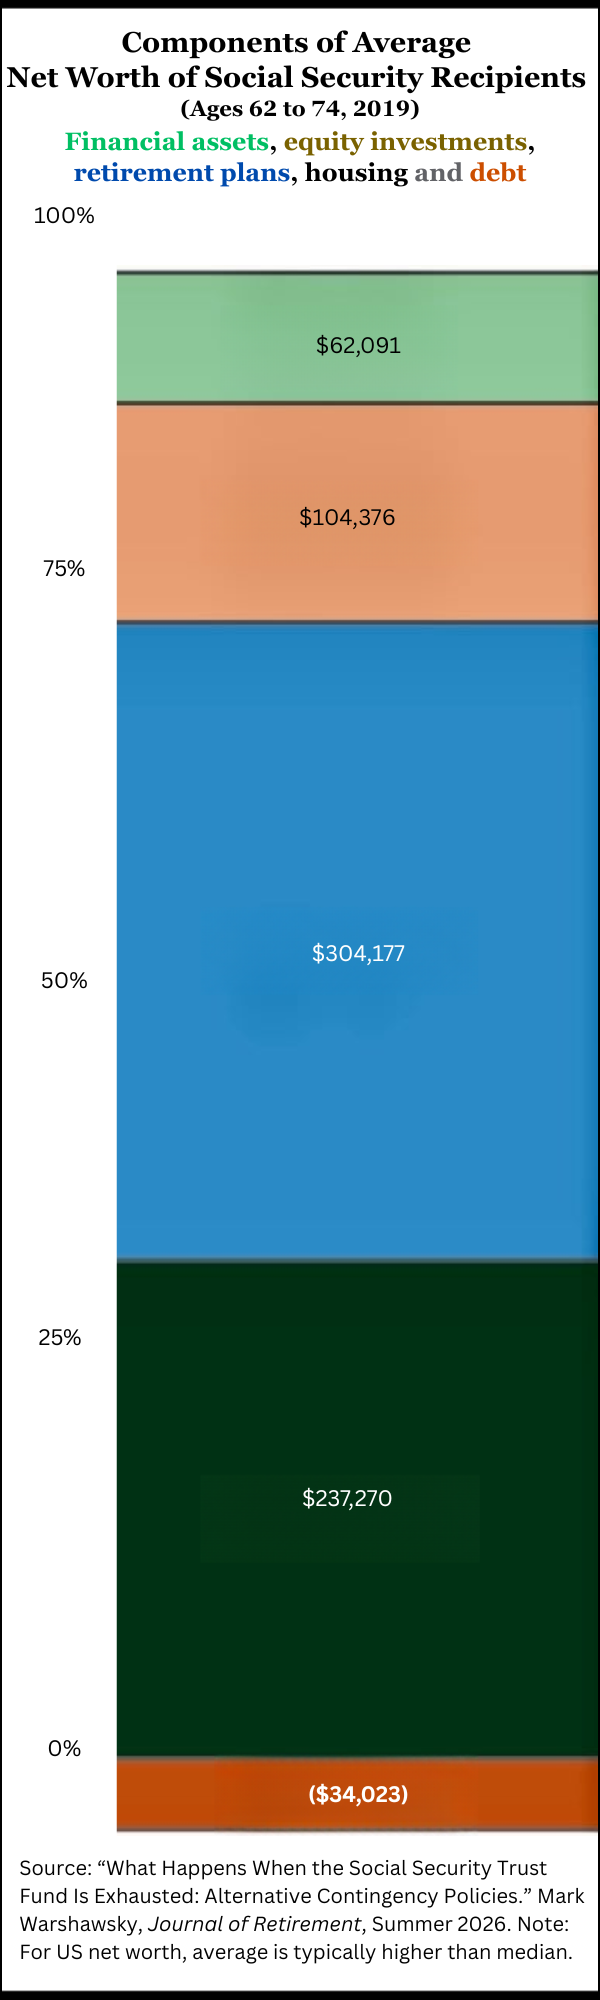
“What Happens When the Social Security Trust Fund Is Exhausted: Alternative Contingency Policies,” Mark Washawsky.  The Journal of Retirement, Summer 2026.

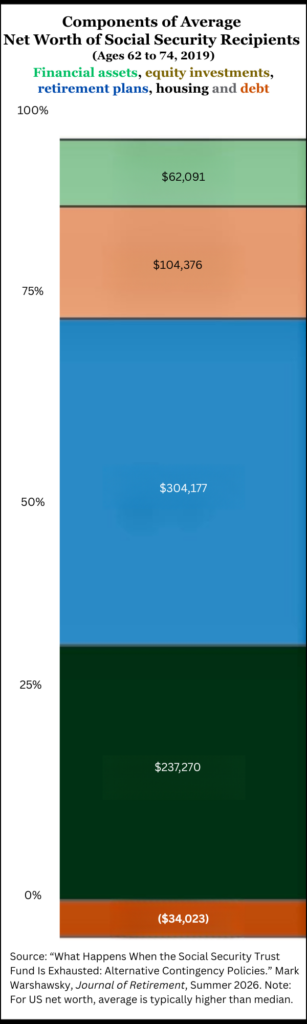
A long-time advocate of the use of single-premium income annuities in personal retirement financing, Warshawsky, who like Biggs is a fellow the AEI, also describes a no-new-taxes approach to Social Security and preservation of the pay-as-you-go system.

But he reduces Social Security’s liabilities through “means-testing” instead of capping benefits, and takes Australia’s means-test as his model.

Australia offers retirees a basic pension, financed out of general tax receipts. A test of each person’s net worth—the means test—determines how big a basic pension, if any, he or she will receive in a given year. (The basic pension is a safety net for retirees who haven’t accumulated enough savings in Australia’s “Super,” a national, mandatory “collective defined contribution” retirement savings plan.)

Reductions in Social Security benefits under Warshawsky’s plan would be restricted to those ages 62–74 who are disabled and those with individual (not household) net worths below $470,400 (in 2025 dollars), with partial cuts for those due to receive the median benefit with net worths below $785,400.

“The Forced Bid: What Privatizing Social Security Would Do to Stock Prices, and Why Recent Developments in the Economics of Market Flows Strengthen the Case Against It,” Edward Lane, July 2026.

The “forced bid” in Lane’s paper refers to the potential impact of diverting all or part of the 12.4% Social Security payroll tax into stocks and bonds. That would backfire, he writes. Citing 2021 research, he claims that the increase in demand for securities would create a short-term  windfall for large shareholders but no real benefit for most other Americans. In his view, it would push the P/E ratio up and the equity risk premium without offsetting the impact of a shrinking workforce.

“The stock market is not a loophole in demography,” he writes.

Applying Modern Monetary Theory, Lane rejects the idea that Social Security’s predicted insolvency represents a crisis. MMT, for those unfamiliar with it, isn’t a theory but a description of how the U.S. fiscal and monetary system actually works. In MMT, the U.S. government is never broke; therefore Social Security is never broke.

For Lane, permanent solvency for the Social Security trust fund isn’t needed, but it is possible. “If Congress wishes to adjust the program’s internal accounting along the way,” he writes, “raising or eliminating the taxable wage cap will do the job without reducing any worker’s protections.”

“Once solvency is recognized as a non-issue for a currency-issuing government, the Social Security ‘problem’ reduces to a demographic question about future real output, which is smaller and more tractable than the financial crisis the privatizers described,” Lane writes.

“Insolvency was never the binding constraint. Real production was, and the privatization debate spent its life arguing about the wrong one.”

Lane also accounts for the cost of a transition to private accounts. “If workers divert part of the payroll tax into personal accounts,” he writes, “benefits to current retirees do not stop, so the government fills the gap by borrowing. Every dollar that flows into a personal account and then into the stock market is matched, dollar for dollar, by new Treasury bonds sold to the public.”

Similarities and differences

Biggs, Shapiro and Warshawsky find ways to bring the Social Security trust fund into balance without any explicit increases in the payroll tax. For Lane, Social Security’s looming deficit doesn’t create an emergency like the one that, say, an insolvent life insurer faces. For me, Lane makes a much-needed contribution to the Social Security debate by accurately framing the program as cost-effective insurance for its price rather than as a bad investment. In this view, Social Security is not an ugly duckling. It’s a swan.

All four writers mention the “rich.” Biggs makes the fairly large assumption that retirees who qualify for Social Security benefits above $2,050 don’t need the excess. Warshawsky counters that people with high benefits aren’t necessarily rich. He asks why we should all pay higher payroll taxes just to keep Social Security benefits intact for the rich. So he suggests an ongoing test of net worth.

But should retirees be described as “rich” if they have net worths of, say, $1 million, including real estate? Or are they merely the “millionaires-next-door” who prudently saved enough to finance a 20- or 30-year retirement?

Lane suggests that only the rich—existing owners of large amounts of securities—would benefit in real terms, and only at first, from diverting payroll taxes into the equity and bond markets. Conversely, he predicts trouble for a privatized savings system when withdrawals start to exceed contributions.

None of these writers seems to mention the implicit tax hike that high-net-worth workers would face if their future benefits were reduced but not their payroll taxes or, conversely, if their payroll taxes went up (because of an increase in the FICA limit) but not their benefits. Warshawsky admits that means-testing is complicated and labor-intensive, but he believes that it’s working in Australia.

Elections may decide

Social Security’s long-term future is likely to depend on the balance of power in Washington during the next seven years. The elections of 2028, 2030, and 2032 could empower either a no-tax-increase or a no-benefit-cut party. Or elections could produce a divided, deadlocked government unable to compromise on a solution.

This article’s illustration is excerpted from a mural by Seymour Fogel in the Wilbur J. Cohen Federal Building in Washington, D.C.

© 2026 RIJ Publishing LLC. All rights reserved.
Bermuda Shorts

Marsh to support triangular-strategy companies in Bermuda

Marsh, a global professional services firm, has launched “Archer by Marsh,” a service that aims to help asset managers and life/annuity annuity companies establish and operate reinsurance businesses. Clients will be able to use the service’s “shared operating infrastructure” while maintaining ownership and control.

According to a release, Archer by Marsh “makes the product, asset, capital, and operating decisions as one simple set, then establishes the vehicle to carry them out. Clients start with what they already have, and Archer by Marsh builds the remaining capabilities to meet the client’s objectives.

The service combines actuarial, capital, risk, reinsurance, life and annuity insurance management, and regulatory expertise to design tailored structures. It supports clients through regulatory approval, establishment, and ongoing operation. These structures can include standalone reinsurance vehicles, special purpose reinsurers, and dedicated reinsurance cells or incorporated segregated accounts (cells).

Faisal Haddad, a Bermuda-based member of Oliver Wyman’s actuarial practice, has been selected as the CEO of Archer by Marsh, pending receipt of all necessary approvals. Marsh has also formed Mangrove ISAC Life Re, a Bermuda-based incorporated segregated accounts company that facilitates sidecar and affiliate reinsurance solutions. Marsh has annual revenue of $27 billion and more than 95,000 employees.

Ratings downgrades for two A-CAP annuity issuers

Two life insurers in the troubled A-CAP Group, Atlantic Coast Life (SC) and Sentinel Security Life (UT), have had their financial strength and credit ratings downgraded, according to a release from AM Best. The ratings agency also maintained the “under review with negative implications” status for the carriers’ credit ratings.

A-CAP, its investment partner, 777 Partners, and an affiliated reinsurer, 777 Re, have been examples of how the conflicts-of-interest and low transparency inherent in the pure Bermuda Triangle strategy can lead to a financial and legal disaster.

That strategy involves organizing, in the same group or as strategic partners, one or more life companies that issue single-premium fixed deferred annuities, one or more aggressive asset managers, and one or more reinsurers domiciled in a U.S. state or foreign country more flexible calculation of capital requirements than in the insurers’ home state.

Fixed deferred annuities are more like investments than like traditional insurance, especially if they have no attached guaranteed income riders or death benefit riders. They are typically purchased with large lump sums, not with incremental premiums. Their terms typically last for less than 10 years. Contract owners buy them primarily for yield, and don’t necessarily use them to produce monthly income over the course of a  20- or 30-year retirement, as buyers of traditional income annuities would.

The life insurers Financial Strength Ratings (FSR) were cut to C+ (Marginal) from B (Fair) and their Long-Term Issuer Credit Ratings (Long-Term ICR) to “b-” (Marginal) from “bb+” (Fair).

The rating downgrades are based on increasing weakness in A-CAP Group’s balance sheet strength, its marginal operating performance, limited business profile, marginal enterprise risk management and operating performance during the first half of 2026, an AM Best release said.

Current capital levels and regulatory capital ratios have deteriorated in the first six months of 2026, continuing a trend since 2024. The group has a significant allocation to illiquid assets and equities that are not traditionally associated with insurance company investments.

There is a concentration in individual securities, investments in affiliated assets and concentration in thinly traded Level 3 assets. There is also an elevated level of paid-in-kind assets that continues to increase over time, along with underperforming mortgages.

The group also has concentrated reinsurance leverage. It utilizes a mix of rated and unrated unaffiliated reinsuring counterparties at the rated entities and at captives, as well as an unrated operating company. The risk of the unrated counterparties is mitigated using collateralized reinsurance agreements.

AM Best acknowledges A-CAP Group’s pending capital raise but has concerns regarding execution risk. Pretax operating gains have been negative for the A-CAP Group each quarter for the past five quarters. Cash flow from operations has been negative at various operating entities over the same period as outflows from benefit payments periodically have exceeded revenues from investment income and varying levels of net premiums and ceding commissions on a quarter-by-quarter basis.

Surrenders have remained elevated from the first quarter of 2025 through the second quarter of 2026. Surrenders peaked at multiples of historical experience in the first half of 2025 after regulatory filings at year-end 2024. After the dismissal of these regulatory filings, surrenders experienced a downward trend through the first quarter of 2026 but were still elevated compared with levels prior to the aforementioned regulatory filings. The downward trend reversed after AM Best’s rating downgrades on A-CAP Group in the first quarter of 2026 but remain below the peak levels experienced in early 2025. Fixed annuity premiums decreased substantially in 2025 after steady growth from 2020 through 2024.

The limited business profile is manifested in reputational damage resulting from publicized regulatory rulings, which have resulted in a material decrease in new premium and material increase in surrenders/outflows.

A-CAP Group’s primary focus is the fixed index annuity market, a dynamic and credit sensitive sector with strong long-term prospects. A-CAP Group has been slow to re-establish its brand presence in this competitive landscape.

The marginal ERM assessment reflects A-CAP Group’s risk culture, which has led to an elevated risk profile related to its invested assets for which the investment cash inflow does not match the cash outflow of the insurance liabilities, and its highly levered reinsurance relationships.

The ratings of ACAP Group remain under review with negative implications based on the potential of a credible capital raise and corporate restructuring, while also considering the uncertainty associated with the completion of the capital raise and execution risk of the transaction. The under-review status also acknowledges the recent Rehabilitation Petition filed by the South Carolina Department of Insurance against a member of the A-CAP Group, Atlantic Coast Life Insurance Company.

The ratings will remain under review with negative implications while AM Best assesses the development and impact of the potential transaction, as well as the ongoing regulatory action.

Florida passenger railroad in private credit restructuring

Assured Guaranty Inc. (AG), a provider of “credit enhancement products” to the U.S. and non-U.S. public finance, infrastructure and structured finance markets, has agreed to help restructure a financially off-the-rails private railroad that has been providing high speed passenger service along Florida’s busy eastern shore.

AG insures a majority, slightly over 50%, of the existing senior tax-exempt bonds of Brightline Florida Trains, the operating company (OpCo) of Brightline Florida Holdings. It owns the majority debt voting position and will exercise its corresponding control rights.

AG has some of the features of a Bermuda Triangle company. Assured Guaranty Inc. is a unit of Assured Guaranty Ltd. It also has an ownership interest in Sound Point Capital Management, LP and in the annuity reinsurance business through Assured Life Reinsurance Ltd.

In connection with the restructuring, which is subject to the bankruptcy court’s review and approval, certain Brightline Florida financial stakeholders, including AG, have entered into a restructuring support agreement.

The restructuring support agreement will provide OpCo, following the Brightline Florida entities’ exit from bankruptcy, $490 million of new capital, consisting of $350 million of new junior debt and $140 million of additional senior debt.

This additional senior debt will be pari passu with OpCo’s existing senior debt. Of the total $490 million of new capital, AG has committed to provide $70 million of the additional OpCo senior debt. This new capital will be used to support Brightline Florida’s ongoing operations and help position it for long-term stability and success, in addition to repaying the post-petition financing described below.

Certain Brightline Florida financial stakeholders, including AG, have also agreed to provide OpCo $258 million of post-petition funding during the pendency of Brightline Florida entities’ bankruptcy process, which funding will be pari passu with the existing OpCo senior debt. AG has agreed to provide up to $178 million of that funding. This funding will be repaid upon the exit of such Brightline Florida entities from the bankruptcy process.

Brightline Trains Florida LLC (OpCo), the obligor with respect to the tax-exempt senior bonds insured by AG, has not filed for Chapter 11 protection. The Chapter 11 bankruptcy filings of certain other Brightline Florida entities do not alter any of the payment obligations to such AG-insured OpCo senior bonds.

© 2026 RIJ Publishing LLC.

PE-led life insurers hold half of industry’s affiliated investments: NAIC

Life insurers reported affiliated bond investments of $121 billion in Schedule D Part 1 and Part 2, which include issuer credit obligations and ABS, respectively, according to a Capital Markets Special Report in September by the National Association of Insurance Commissioners.

Issuer credit obligations include traditional bond investments, such as corporate bonds, and other structures for which payment depends on an operating entity’s creditworthiness. Life insurers with a PE (private equity) relationship accounted for approximately half of all life insurers’ affiliated investments.

They also accounted for approximately 95% of life insurers’ affiliated ABS, 50% of affiliated issuer credit obligations, and one-third of affiliated other long-term investments. Lastly, among life insurers with PE relationships, accounted for almost 50% of all life insurers’ total reported affiliated investments. ABS includes structures in which debt service to investors is derived from the cash flows on the underlying collateral.

For example, with collateralized loan obligations (CLOs), principal and interest are paid to noteholders based on the cash flows derived from income generated by the transaction’s underlying bank loan collateral. Coincidentally, many large life companies have CLO asset managers that are affiliates or subsidiaries. Therefore, a portion of their affiliated ABS exposure likely consists of CLOs issued by affiliated entities.

Over the last several years, there has been an uptick in the number of life insurers acquired by private equity (PE) firms. As such, life insurers may leverage their relationship with the PE firm to access capital markets or investments not otherwise available to them, while the PE firm benefits from additional income generated through the acquired life insurer’s business.

Source: “U.S. Life Insurers’ Affiliated Investments at Year-End 2025,” September 2026.

How Leveraged Are Bermuda Triangle Life Insurers?

Life insurers used to brag about the size of their surpluses, aka their capital buffers against loss. Today, asset manager-led life insurers in the Bermuda Triangle are more likely to brag about their “capital efficiency” and intention to run “capital-light” companies.

That’s Wall Street-speak for more leverage. Leverage—borrowing to invest—is a normal part of finance. Insurance is an inherently leveraged business, floating on the savings of its customers. Used successfully, leverage can multiply returns on equity capital. But, in a financial crisis, if the borrowed money is secured by collateral that’s also borrowed, and whose value is subject to market volatility, leverage can multiply the risk of loss or insolvency.

Bermuda Triangle companies—annuity-issuing life insurers with affiliated alternative asset managers and offshore reinsurers—tend to carry a lot of leverage. Collectively, these powerful combinations have leveraged hundreds of billions of dollars in annuity sales revenue and borrowed billions more from institutional investors, primarily to finance the asset managers’ high-yield private-credit loans to already-leveraged firms.

Their degrees of leverage are hard to measure. The life insurers’ annuity contracts are complex. The asset managers’ loans to middle-market companies are by nature high-risk, complex, illiquid and bespoke. Simultaneously serving as borrowers and lenders, affiliated life insurers and asset managers can at times control both sides of large transactions. The operations of their holding companies, which straddle state, federal and international jurisdictions, have both worried and frustrated regulators and watchdogs. They see the growth of the strategy as a potential threat to the stability of the global financial system.

This month, as part of RIJ’s ongoing effort to shine light on the inner clockwork of the three-way Bermuda Triangle strategy, we identify their obvious and obscure sources of leverage.

Sources of leverage aka capital efficiency

Balance sheet leverage. Insurance is itself is a highly leveraged business. When a life insurer borrows sells fixed deferred annuities (the product of choice for Bermuda Triangle companies), it in effect borrows the savings of risk-averse older Americans. The life insurer takes their five- or six-figure premiums, buys and holds mainly investment-grade bonds, and earns a spread—the difference between what it promised annuity contract owners and what it earns on its purchased assets.

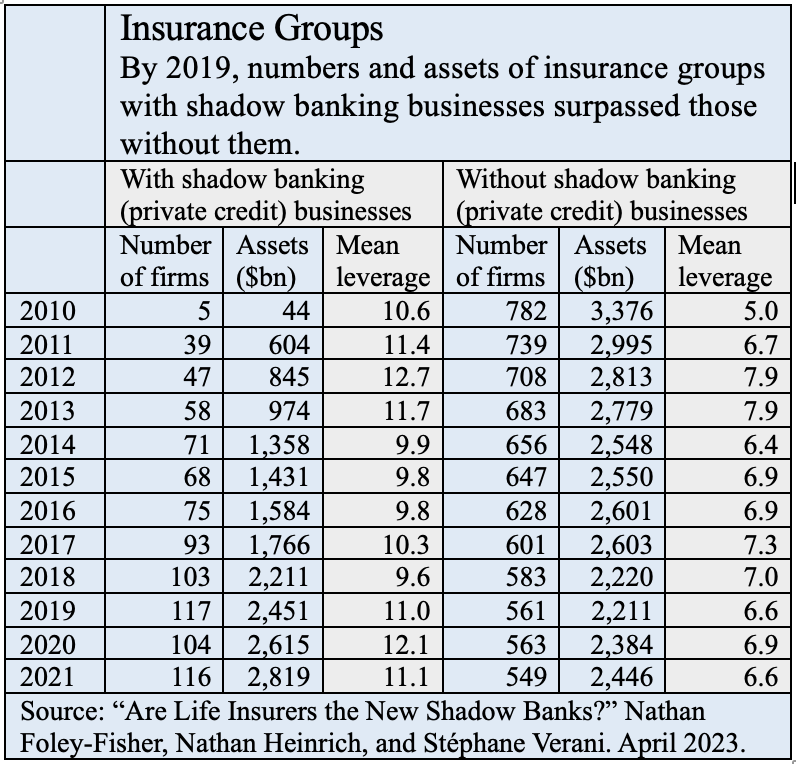
The spread might only be 2%, but the insurer earns upwards of 10% to 15% in return on equity, thanks to leverage. Of $100 billion in reserves that a life insurer invests, for example, its surplus might be only $5 billion. A 2% spread on the invested assets means a $2 billion gain on equity capital of $5 billion. That’s a 40% gross return, which expenses might reduce by two-thirds or more. A 2023 Federal Reserve research paper (see table at right) showed that, from 2010 to 2021, life insurers with “shadow banking” or private credit activities—RIJ’s “Bermuda Triangle”—ran consistently higher average leverage levels  than life insurers without such businesses.

Leverage levels at asset-manager-led life insurers have been going up. According to the Federal Insurance Office’s September 2025 Annual Report on the Insurance Industry, “The trend in investment exposure and surplus exposure—with potentially heightened insurers’ exposure to certain risks that can stem from a downward spiral in asset prices, increased issuer leverage, rising defaults, and funding risks—continues to be monitored by FIO. “The asset leverage for privately-owned insurers is somewhat higher” than the insurance industry average, according to ALIRT.

Capital-efficient products. As insurance products go, fixed deferred annuities, and especially fixed indexed annuities (FIAs), are priced for demanding relatively little life insurer capital.

Sold as safe investments and not life-contingent income, and usually running for terms of three to 10 years, fixed deferred annuities don’t carry the decades-long exposure to changing longevity or mortality rates that, say, a traditional immediate income annuity or a life insurance policy would. (Editor’s note: Much of the media seems to confuse deferred annuities with income annuities.)

In the case of FIAs, the contract owners themselves finance an at-the-money call option on an equity index or hybrid index. They use roughly the interest they might have earned on a fixed-rate annuity, adding to this “options budget” by selling rights to index returns above a certain level. Through their management of the volatility controls inside bespoke indices, FIA issuers can put governors on the returns of the index and make their returns more consistent.

When the risk of the liability is under control, the insurer conserves capital, which implicitly raises leverage levels. That capital can be used to increase annuity sales and to help finance bundles of high-yield loans. Purchasers of FIAs, especially those who reach for the highest-yielding contracts, presumably like to see their insurers reaching for yield—they’re banking on the fixed annuities’ no-loss-of-principal guarantees to keep them whole.

Reinsurance. This may be the most overlooked source of leverage in the Bermuda Triangle.

Traditionally, life insurers reduced their leverage ratios by selling books of capital-intensive business to reinsurers to “free up capital.” Many still do. But asset manager-led life/annuity companies have flipped that logic. When they’re not buying blocks of distressed annuity or life insurance business from older life insurers, they’re using reinsurance to reduce the capital requirements triggered by new annuity sales or riskier investments.

From Foley-Fisher et al, April 2023.


They typically do this in partnership with an affiliated reinsurer—another unit of the same holding company—in Bermuda or the Cayman Islands. The offshore reinsurer can put up the capital to back new sales and assume the risks associated with high-yield lending. Those jurisdictions may require less capital than the U.S. regulators require. Moreover, the Bermuda reinsurer can lever “sidecars”—financed by international institutional investors—for some or most of its capital. That’s another form of leverage.

“Privately-owned life insurers reported much higher reinsurance leverage (both affiliated and unaffiliated) than the life insurance industry in total, the insurance analysts at ALIRT reported in July of this year. “This reflects the greater use of reinsurance among privately-owned carriers as well as the portion of capital held at foreign reinsurance entities in some cases.”

“The vast majority of reserves ceded are covering liabilities for indexed and fixed annuities,” said Best’s Special Report, “Big Year of Growth for Life/Annuity Sidecar-Like Activity in 2025.” “As a result of managing strong premium growth through reinsurance, the individual annuity composite has steadily seen its reinsurance leverage double since 2019. In addition, overall surplus relief of nearly 11% in 2025 was double that of the previous year.”

According to recent Bank of International Settlements research, “By 2023, US life insurers had ceded $2.1 trillion in reserves, up from $500 billion in 2017, representing 25% of their total assets. Offshore reinsurers accounted for 40% of these risks, up from 14% in 2017, with some of this activity occurring in jurisdictions with less stringent regulatory frameworks.”

“PE-influenced reinsurers… account for about half of the assets of all long-term reinsurers in Bermuda,” according to a 2023 International Monetary Fund study. “As of the latest available data in 2021, Bermuda long-term reinsurance assets, a proxy for life reinsurance, grew to more than $1 trillion, about 4% of total life insurance assets globally, doubling their share when compared to the previous four years.”

‘Embedded’ leverage. Life insurers can get exposure to higher-yielding, below-investment grade assets, without a proportionate increase in their capital requirements, by financing investment-grade senior tranches of collateralized loan obligations (CLOs) created or managed by their affiliated asset managers. In effect, the financial engineering process of securitization lets them hold riskier assets without employing as much capital.

The International Monetary Fund calls this “embedded leverage.” According to the IMF, “The National Association of Insurance Commissioners (NAIC) has found that an insurer that owns all the tranches of a collateralized loan obligation with underlying assets of B-rated loans would have a substantial beneficial regulatory capital arbitrage compared to holding directly the underlying B-rated loans based on existing risk-based capital (RBC) calculations for life insurers. NAIC is proposing to address this regulatory capital arbitrage by adding additional NAIC designation categories and relevant RBC factors.”

“An insurer in the U.S. or Bermuda that packages its middle-market loan holdings into a CLO and invests in the entire CLO capital stack could reduce its capital charge by a factor of 10… Insurers holding a portfolio of B-rated loans can cut their risk-based capital charges by two-thirds if they package those loans into a CLO and purchase the entire CLO capital stack,” according to a March 21, 2025, FED Notes bulletin entitled, “Life Insurers’ Role in the Intermediation Chain of Public and Private Credit to Risky Firms.”

The life insurer earns a rate of interest that’s higher than comparably-rated public-market securities, while the asset manager is in a position to earn management fees (CLOs are, or can be, actively managed) and, if it has an interest in the risky equity tranche of the CLO, a return multiplied by all the borrowed money in the CLO stack.

Borrowings from Federal Home Loan Banks. The FHLBs are a system of 11 regionally-based government-sponsored banks providing liquidity to financial institutions to promote housing and community initiatives. Insurers can borrow from the FHLB if they engage in mortgage lending (or hold mortgage-backed securities) and purchase FHLB stock. To receive advances from the FHLB, they post collateral, sometimes using the money they borrowed by issuing funding agreement-backed notes or FABNs (see below).

A June 2026 Best’s Special Report, “Funding Agreements Drive FHLB Borrowings for the L/A Industry in 2025,” states that borrowings in the form of funding agreements totaled $153 billion in 2025, compared with $136 billion in the previous year, as annuity writers have been able to leverage the lower cost of borrowing from the FHLBs and gain a favorable spread on investments. Although the FHLBs provide an inexpensive short-term financing option potentially used to increase investment income, an insurer may be exposed to credit risk, collateral risk and market risk.

According to the report, borrowing capacity grew at a faster rate than borrowings in 2025, increasing by 18%, again heavily driven by annuity writers. “Borrowing capacity is still broadly available, although it is somewhat more limited than in 2019, before the more recent annuity sales boom amid private capital heavily entering the life/annuity industry. Two-thirds of companies used less than half of their available capacity in 2025, which is up from 62% in 2019; however, a notably higher share of companies have outstanding borrowings today as compared with 2019.”

The report added, “Since FHLB funding agreement borrowers are predominantly companies that sell annuities and spread-play business, the investment profile of these borrowers closely mirrors that of the individual annuity composite in asset classes such as private placements and affiliated and high-risk investments, as well as bond yields.”

For example, Delaware Life, which is currently under SEC investigation for understating its degree of lending to affiliated companies, reported in its latest statutory filing that $6.4 billion of its assets are pledged as collateral for its FHLB loans. It was part of the $10.6 billion in “restricted assets” that the company can’t readily liquidate. Delaware Life’s surplus, by comparison, is just $3.9 billion.

The Congressional Research Service, in a March 27, 2025 report to Congress, didn’t comment directly on FHLB loans to life/annuity companies, but noted, “Because Congress created FHLBs to facilitate mortgage market liquidity, public policy discussions often consider the system’s effectiveness at achieving the congressional intent.

“One concern is that many member institutions eligible to join the FHLB system may not be principally engaged in residential mortgage finance, calling into question the extent to which FHLB advances subsidize the funding of mortgages or the funding of member institutions’ asset portfolios in general.” [Emphasis added.]

Funding Agreement Backed Notes. The 1994 invention of “funding agreement backed notes” has been attributed to former SunAmerica CEO and later Athene CEO Jim Belardi. Life insurers can use funding agreements, which are similar to guaranteed investment contracts (GICs), to borrow money in the wholesale money markets. The life insurer sends a funding agreement to a special purpose vehicle (SPV) it creates. The SPV sells notes or securities—interest-paying IOUs—to institutional investors, and passes the proceeds of the sale back to the life insurer.

These borrowings, which are in effect secured by the same general account assets that back the insurer’s obligations to annuity owners, can be used to secure the life insurer’s FHLB advances. The life insurer’s obligations to FABN lenders are said to be “pari passu”—on equal footing—with the insurer’s obligations to contract owners and policyholders.

The chart below, from a 2025 presentation by the American Council of Life Insurers, shows the steady increase in FABN borrowing by life insurers.

FABNs give an insurer a new deposit-like asset and a new insurance liability without changing its surplus. They can, however, increase a carrier’s economic leverage. The table below shows how new FABN debt can change surplus ratios.

Source: ChatGPT and RIJ.


“A highly leveraged insurer with well-matched, liquid assets and widely staggered fixed-term maturities may be manageable,” said a NAIC primer on FABNs. “A rapidly growing insurer funding illiquid private-credit assets with short or concentrated FABNs is considerably more vulnerable. So the appropriate conclusion is: the growth is a legitimate regulatory concern and potentially a systemic-risk signal, especially if it is not visible in conventional leverage statistics. But the danger depends on the structure and use of the funding, not on issuance volume alone.”

The NAIC doesn’t have complete data on the amount of FABN borrowing by life insurers, according to the primer: “Statutory reporting of FABNs by insurers does not exist, making it difficult to accurately assess overall exposure levels and the appropriate matching of assets to liabilities (i.e., whether the duration of the funding agreement matches that of the FABNs issued).

“To address this transparency risk, the NAIC has proposed standards for additional disclosures in insurer annual statement filings for funding agreements that back FABNs. Currently, the only required reporting is the amount of funding agreements issued in aggregate for all purposes, with disclosure of funding agreements issued in connection with FHLB advances.”

Conclusion

There’s a lot of leverage in the Bermuda Triangle. Life/annuity companies in effect borrow by selling annuity contracts, by issuing FABN notes, and by receiving advances from Federal Home Loan Banks. The insurers then finance their asset managers’ private credit operations while money from institutional investors helps capitalize their affiliated reinsurers.

Leverage can be good and bad. On the one hand, it multiplies return on equity. On the other hand, it allows investment companies to take big financial risks with other people’s money. The Bermuda Triangle scares certain regulators and watchdogs—the Federal Reserve, the IMF, the FIO, the BIS, and the NAIC—because its business model is opaque and the securities that its practitioners use as loan collateral can be illiquid, hard to rate and hard to price. Bermuda Triangle companies are good at turning cash into paper assets. But in a crisis, will they be able to turn that paper back into cash?

The private nature of private lending, coupled with fragmented regulation, is bound to make it hard to know who is on the hook to provide the cash and how much money they owe.

“The migration of credit creation and corporate control toward private intermediaries redistributes and reshapes risk rather than eliminating it,” said a recent paper from the CFA Institute’s Research and Policy Center. “As these intermediaries scale, the issue is no longer only leverage and liquidity. It is also accountability—who ensures valuation integrity and transparency—and how standards and supervisory frameworks adapt to protect investors and the stability of the system.”

© 2026 RIJ Publishing LLC. All rights reserved.
AM Best marks growth of offshore reinsurance

AM Best identifies strength, weakness and growth of offshore reinsurance

Strong annuity product growth, higher interest rates, and offshore transactions that take advantage of differing capital regimes is driving U.S. life/annuity companies to cede out business and increase their level of reinsurance leverage, according to the latest Best’s Market Segment Report.

The report, “Global Life/Annuity Reinsurers Remained Poised for Steady Growth,” is part of AM Best’s look at the global reinsurance industry ahead of the Rendez-Vous de Septembre in Monte Carlo.

“Persistent and intensifying competition” is pressuring asset-manager-led life/annuity companies in particular to grow returns, AM Best said. “Asset-intensive reinsurance” (protection from asset underperformance, not from liability shocks) can enhance profitability by providing surplus relief.

Bermuda and, to a lesser extent, the Cayman Islands, offer opportunities for surplus relief through regulatory arbitrage. Offshore L/A reinsurance has averaged 31% annual growth over the past 10 years. Pure life-side product reinsurance is a more mature marketplace but still sees a steady growth rate of about 4% a year. Many companies have placed their focus on counterparty risk.

“The treatment of required capital and reserves is often less stringent than for reinsurers domiciled onshore in the United States. There is increased recoverability risk in some cases due to a lack of collateralization in some jurisdictions,” said Edward Kohlberg, director, AM Best, in a release.

AM Best noted “pockets of concern that the level of excess capitalization may be insufficient to support claims in stress scenarios”—meaning that the reinsurers, having provided surplus relief to the ceding companies, might turn out not have enough capital to cover the ceding companies’ losses in a big asset price crash.

The amount of reserve credit taken and funds withheld on U.S. cedents’ balance sheets has been steadily increasing as a percentage of gross reserve credits taken, the release said. At year-end 2025, 41% of ~$1.61 trillion in reserve credits taken belonged to reinsurers, up from about 21% at year-end 2016.

Sidecars can help. “Sidecars have also gained prominence in the L/A space,” said Lou Silvers, senior financial analyst, AM Best. “These are reinsurance affiliated or non-affiliated entities that draw on capital from third-party limited investors and can provide incremental just-in-time capital to execute larger deals when opportunity arises and earn additional fees for the general partner.”

Asset manager-led insurers drive offshore reinsurance growth: AM Best

The amount of annuity reserves ceded offshore continued to increase in 2025 and now represent more than half of ceded annuity reserves as companies manage risk-based capitalization levels amid increased market competitiveness, according to a new AM Best report.

The Best’s Special Report, “Unaffiliated Offshore Reinsurance Deals Drive Asset-Intensive Reinsurance Market in 2025,” is a part of AM Best’s look at the global reinsurance industry ahead of the Rendez-Vous de Septembre in Monte Carlo.

Takeaways from the report include:

  • Unaffiliated reinsurance deals outpaced affiliated deals in 2025 for the first time in three years, with the 10 largest unaffiliated reinsurance transactions in 2025 totaling over $107 billion, greatly surpassing the $35 billion in 2024.
  • AM Best notes that cross-border reinsurance introduces operational complexity and opacity. While the use of offshore reinsurance helps manage risk-based capitalization, reinsurance dependence, quality and the appropriateness of reinsurance programs can have negative impacts to the overall balance sheet strength assessment in AM Best’s rating analysis.
  • Although reinsurance deals with offshore entities often complicate accounting, AM Best captures these risks at the consolidated level by looking at the ceding and affiliated captive reinsurance company in its global Best’s Capital Adequacy Ratio (BCAR) calculations.

The asset-intensive reinsurance market remains competitive as annuity growth slows at primary insurers, leading to steadily increasing reinsurance leverage for the life/annuity segment. In this report, AM Best states that offshore reinsurance accounted for nearly 56% of ceded annuity reserves, including modified coinsurance (modco) reserves.

While Bermuda continues to be the dominant offshore domicile, the Cayman Islands increased its share of the market in 2025, heavily driven by a few recently established sidecars.

The dramatic increase in ceded reserves to offshore affiliates has been driven largely by private equity/asset manager-owned companies.

“Private equity/asset manager-owned insurers generally lean more into this strategy, as these companies account for nearly half of reserves ceded to offshore affiliates, but account for only one-quarter of total reserves ceded,” said Jason Hopper, associate director, Industry Research and Analytics, AM Best.

A Flurry of Activity in the Triangle

Two regional banks pause sales of Delaware Life annuities

Truist Financial Corp. and Fifth Third Bancorp. have paused distribution of Delaware Life products while Mark Walter responds to an SEC investigation, Bloomberg has reported, based on confidential interviews.

“The banks are tapping the brakes on their role as sale channels for Delaware Life Insurance Co. amid a US probe of Walter’s sprawling business empire that has cast a shadow over credit ratings for the provider of annuities and life insurance,” Bloomberg reported.

The lenders had made the insurer’s products available through branches or adviser networks with the underlying risk of the insurance and market borne by the insurer itself.

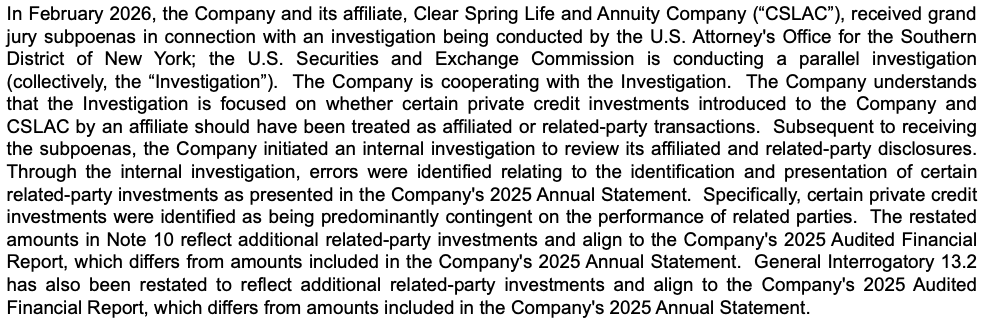
Delaware Life and the smaller Clear Spring Life (formerly Guggenheim Life) are controlled by Walter’s holding company, TWG Global. The insurers revealed in June that they had more than $20 billion of affiliated loans on their books that were not marked as such.

TWG said in a statement earlier this week that it’s working to resolve any regulatory concerns and that there “has been no fraud. No one has been harmed, and no one has claimed they were harmed.”

While new sales of products are paused, the insurer is in contact with client advisers at both institutions, one of the people said. Representatives for Truist and Fifth Third declined to comment. “Our communications with key distribution partners remain open and cooperative,” a spokesperson for Delaware Life told Bloomberg.

Malibu Life partners with Legacy Marketing to launch its first FIAs

Malibu Life USA, which is controlled by Third Point Investors, has tapped Legacy Marketing Group as its distribution partner for Malibu’s new PillarMark and SpireMark FIAs. Both products are expected to launch this month.

The products will be underwritten by Texas-domiciled TruSpire Retirement Insurance Company. TruSpire, which Malibu Life parent Malibu Life Holdings Ltd. acquired this year, is expected to serve as Malibu Life’s direct U.S. annuity origination platform. The group has a Cayman Islands reinsurer, Malibu Life Re.

The force behind Malibu Life is Daniel S. Loeb, the billionaire CEO of asset manager Third Point Investors Ltd. As RIJ reported last November:

“In little over a year, Loeb and his team have:

  • Turned their Hudson Yards-based closed-end fund into a London-listed insurance holding company
  • Bought Birch Grove, an $8 billion private-credit investment shop
  • Established Malibu Life Re, a reinsurer in the Cayman Islands
  • Acquired a Texas-domiciled U.S. life insurer
  • Hired a veteran Cayman reinsurance executive to run Malibu Life
  • Agreed to provide “flow reinsurance” to an unnamed “blue-chip annuity platform”
  • Secured equity commitments from Voya and its ReliaStar unit
  • Prepared to issue a fixed deferred annuity in the U.S. in the first half of 2026”

PillarMark has a lifetime income rider with the “potential for increasing payouts over time,” while SpireMark is a fee-based solution for RIA clients seeking “flexible income with early income opportunities,” according to a release. Both will feature “Allocation Blueprints,” a planning tool.

Sun Life and Wilton Re in asset management/reinsurance deal

Sun Life Financial Inc. and Wilton Re have established a strategic reinsurance and asset-management partnership in a deal expected to deploy $900 million in capital, according to a release.

Of the initial deployment of $900 million, the companies said they will each commit about a third of the initial deployment of $900 million. Windsor Life Re will reinsure from Wilton Re an in-force block of approximately $1.7 billion, it said.

Wilton Re will cede future business on a quota share basis to Windsor Life Re, which is anticipated to reach $10 billion in assets.

The partnership ties Wilton Re’s liability management experience with Sun Life’s insurance and asset management capabilities, the companies said in a joint statement.

Wilton Re will form Windsor Life Re, a reinsurer domiciled in the United States and Bermuda that supports growth in its Wilton Re’s U.S. in-force life and annuity block generation, the company said in the statement.

Wilton Re has experience in in-force block acquisitions, as well as deal-sourcing and underwriting expertise. Sun Life’s SLC Management will be the lead asset manager for Wilton Life Re’s investments. The partnership is expected to launch in the first half of 2027.

Cayman Islands seeks NAIC ‘qualified jurisdiction’ status

The National Association of Insurance Commissioners said it received an application for Qualified Jurisdiction status from the Cayman Islands Monetary Authority.

The application, delivered Aug. 7 and currently moving through the NAIC’s committee process, is limited at this time to Class D insurers working in nonlife property/casualty business, the NAIC said.

But in April, the Cayman Islands announced it would seek Qualified Jurisdiction status for its reinsurance sector, which would formally recognize the Cayman Islands’ reinsurance regulatory framework within the NAIC process.

Receiving the distinction would allow U.S. insurers to get credit for reinsurance from a non-U.S.-domiciled company, according to NAIC documents. The receipt of qualified jurisdiction status would also lower reinsurance collateral requirements, NAIC documents said.

Pacific Life Re announces flow reinsurance deal in Japan

Pacific Life Re, the global life reinsurance business of Pacific Life, has completed its third asset-intensive flow reinsurance transaction in Japan, according to a release. The transaction follows the company’s prior block transactions and two flow transactions in Japan.

The deal, executed with a Japanese life insurer, involved the reinsurance of whole life liabilities through another new flow counterparty. The flow format helps insurers manage capital and risk exposures, while also enhancing the competitiveness of their product offerings in the market, according to a release.

Hildene’s credit ratings posted ahead of SILAC purchase

With Hildene Holding’s acquisition of SILAC Inc. still pending, Hildene Holdings and Hildene Capital Management, LLC (HCM), have received issuer ratings of BBB and senior secured debt ratings of A- from the ratings agency, KBRA.

“The ratings are supported by Hildene’s growing scale and platform diversification across multiple segments of structured credit, asset-based finance, and insurance, underpinned by management’s expertise in complex securitized products and structured finance investing, according to a KBRA release.

KBRA said that the acquisition of SILAC, Inc., parent of SILAC Insurance Company, a provider of fixed and fixed indexed annuity products, will diversify Hildene’s AUM toward longer-duration assets.

As co-borrowers, HCM and Hildene Holding Company, LLC, are seeking a $150 million senior secured delayed draw credit facility with a three-year maturity and two 12-month extension options. Approximately $100 million will be used to fund a portion of the ~$550 million SILAC acquisition.

Athene’s financial strength affirmed by AM Best

AM Best has affirmed the Financial Strength Rating (FSR) of A+ (Superior) and the Long-Term Issuer Credit Ratings (Long-Term ICR) of “aa-” (Superior) of the members of Athene Group (Athene).

Athene is the consolidation of the organization’s U.S. operating companies, along with its affiliated reinsurance companies domiciled in Bermuda.

AM Best also affirmed the Long-Term ICR of “a-” (Excellent) of Athene Holding Ltd. (Delaware), the holding company for the U.S. and Bermuda operations, and its AM Best has Long-Term Issue Credit Ratings (Long-Term IR) and the indicative Long-Term IRs. All the Credit Ratings had a stable outlook.

AM Best assessed Athene’s balance sheet, its operating performance, business profile and enterprise risk management, as very strong or strong. The agency viewed Athene’s consolidated risk-adjusted capitalization as strongest, based on Best’s Capital Adequacy Ratio (BCAR).

“Athene has demonstrated its ability to access capital markets and maintains additional access to capital and liquidity through a liquidity facility, a revolving credit facility and the Federal Home Loan Bank, by its borrowing capacity and a shelf registration statement, as well as uncalled capital commitments from Athene Co-Invest Reinsurance Affiliates investors,” AM Best said.

© 2026 RIJ Publishing LLC. All rights reserved.
Mark Walter Brings Eyeballs to the Bermuda Triangle (I Hope)

When I heard about the SEC investigation of Mark Walter, Guggenheim Partners, Delaware Life and Clear Spring Life, I thought:

Maybe this will bring some overdue attention to the regulatory arbitrage that RIJ calls the Bermuda Triangle strategy. If it takes the reflected glory of the World Series Champion Los Angeles Dodgers to focus the nation’s attention on that strategy—of financing high-maintenance, high-yield, risky loans with low-maintenance, low-yield retirement savings—into sensational news, so be it.

Subsequent thoughts, in no particular order:

  • Isn’t lending to affiliates why “alternative asset managers” (aka buyout firms, aka private or private credit managers, former ‘Barbarians-at-the-Gate’) like Apollo, KKR, and others buy (or start or partner with) life insurers? Isn’t that why the life insurers sell fixed deferred annuities? Isn’t that why they set up affiliated reinsurers in Bermuda or the Cayman Islands to tamp down their capital requirements and finance their distribution expenses?
  • Didn’t Mark Walter only a month ago, in a ceremony in the former Rose Garden, break tradition to give Donald Trump a jewel-encrusted World Series ring along with the honorary name-jersey that sports champions customarily give presidents?
  • Didn’t the SEC investigate Walter for self-dealing back in 2018? Hadn’t the Wall Street Journal reported that he used life insurer money to buy an $85 million mansion (that the Pacific Palisades fire later destroyed)?
  • Were insurance regulators in Delaware Life and Clear Spring Life’s home state of Delaware on top of the affiliated loans? If not, why not?

For anyone new to the Walter/Delaware Life/Dodgers drama, the Wall Street Journal and other media outlets recently revealed that a whistleblower had told federal regulators that Walter’s life/annuity companies had made many more affiliated loans than it had reported on its statutory filings.

A federal investigation led to a grand jury and a subpoena earlier this year of the records of Delaware Life and Clear Spring. It turned out that not 3% but 42% of Delaware Life’s assets were invested in affiliated companies, and that the total value of affiliated transactions was $17 billion more than reported.

From Delaware Life’s latest statutory filing, p.7.2

According to its 2Q2026 statutory filing, Delaware Life had assets (excluding $18.5 billion in separate accounts) of $46.6 billion and a surplus of $3.9 billion for a middle-of-the-industry surplus ratio of about 8%. At $17 billion, transactions whose value depended on the performance of affiliated private credit assets—illiquid assets of potentially questionable value—were therefore worth more than its surplus.

Walter has since taken initial steps to bring down the percentage of affiliated assets to 39%, and then to 26%. In a slide deck that Delaware Life shared during its recent Second Quarter 2026 Investor Day presentation, the company described its Affiliated Reduction Plan & Control Remediation Plan Update. There’s a brief discussion there of what that entails (see below).

But this investigation, and the reporting on it, is in danger of missing the bigger picture. As Valmark CEO Larry Rybka spells out clearly in his white paper in today’s issue of RIJ, as does this new research paper from Yale, the ownership of life insurers and reinsurers by alt-asset managers can easily, if abused and not properly regulated, become what in common parlance we used to call a racket.

Even if an alt-asset-manager-led life insurer made only unaffiliated loans, the real problem—affiliations of life insurers and asset managers for the purpose of taking risks with retirement savings—would still exist. The conflict occurs at the institutional level, not just at the loan level. The strategy’s practitioners see synergies, not conflicts. To use tech jargon, the conflict is a feature not a bug.

This incident is also revealing the hidden affiliations between the owners of insurance holding companies. The Wall Street Journal has shed light on ties between Mark Walter and Security Benefit’s Todd Boehly, and between Sammons and Guggenheim Partners (though Sammons claims to have diversified its investment management), and between Walter and Mubadala, the Abu Dhabi sovereign wealth fund.

The Journal reported that in April 2025, Walter’s conglomerate, TWG Global, had announced that Mubadala, the Abu Dhabi fund, would help it raise $10 billion in new equity. Mubadala is an investor in Aquarian Holdings, a $27 billion asset manager that bought Investors Heritage Life in 2018, then Hudson Life, then Somerset Re, then established Neptune Reinsurance, then, in 2025, bought Brighthouse, formerly MetLife’s retail annuity business.

Federal Reserve economists have been raising flags about this phenomenon since the early 2010s, identifying private credit as “shadow banking” and offshore reinsurance “as shadow insurance.” At least six years ago, other Fed economists identified the triple play of affiliated asset managers, life insurers and reinsurers. RIJ has been writing about the phenomenon since 2020. For the latest research on these structures, see the research cited in RIJ today by Eileen Appelbaum of the Center for Economic Policy and Research.

Maybe the Dodgers angle will finally bring this complex topic, and all its implications about wealth concentration and diluted financial regulation, to the level of national debate.

© 2026 RIJ Publishing LLC. All rights reserved.
MYGAs Were the Top-Selling Annuity in 2Q2026

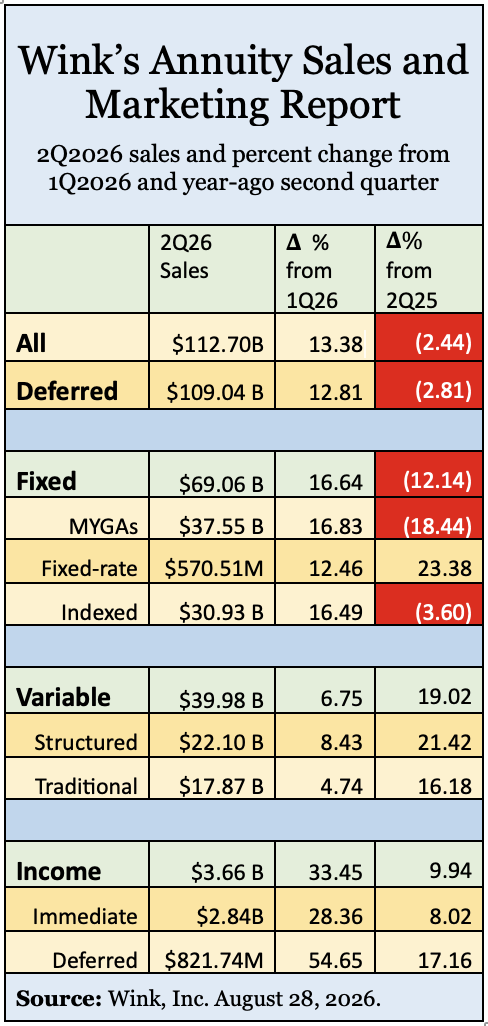
This quarter marked some substantial sales improvements from last quarter. The fall of indexed annuity sales in 2Q2026 was tough, but it didn’t have quite the same sting as the drop in multi-year guaranteed annuity (MYGA) sales for the quarter.

Every line of business experienced an increase in sales, relative to 1Q2026. Indexed annuity and MYGA volumes were down, however, when compared to this quarter, last year. There were 44 negative rate adjustments during quarter two, compared to 112 at this time last year.

Multi-year guaranteed annuities, fixed annuities and indexed annuities’ sales were directly impacted with those negative rate adjustments. The end result? Forty-one percent of annuity participants experienced declines over 1Q2026 sales, and 39% of participants experienced declines over 2Q2025. Overall, annuity sales were up over 13% from last quarter, but down over 2% from this time in 2025. We anticipate that annuity sales will fall short of 2025 levels this year.

Deferred annuities experienced much of the same, relative to all annuities. Rates are relatively good, but that isn’t enough to get agents off the beaches and into their offices to sell more annuities. The summer is always a challenging quarter, as far as sales go.

That said, sales of all deferred annuities increased nearly 13% from last quarter but dropped by nearly 3% when compared to this time, last year. The MYGA line of business was up nearly 17% from 1Q2026—and that’s great. However, sales were also down on these commoditized products- over 18% from 2Q2025.

One-year guarantee fixed annuities increased over 12% from last quarter and over 23% from this time, last year. That said, it is easy to beat a benchmark that is already low to begin with. Indexed annuities increased sales more than 16% from the prior quarter, but down nearly 4% from this time last year. Next quarter should be an improvement.

Structured annuities (Registered Indexed-Linked Annuities, or RILAs) shined this quarter with an increase in sales exceeding 8% from last quarter. Those offering the newest type of deferred annuity are killing it, and it shows; sales were up over 21% from 2Q2025. There is no questioning that structured annuity sales will set another record in 2026.

And variable annuities…they are steadily on the rise. Sales levels were up nearly 5% from last quarter and up more than 16% versus this period, last year. Income annuities of the immediate kind had a great quarter with a 28% increase from 1Q2026 and an 8% thrust forward from this period, one year ago.

Deferred income annuities’ growth would be remarkable if sales weren’t so low to begin with. The 55% increase in sales of DIAs from last quarter is a roadmap for others to follow. With sales up 17% from 2Q2025, it isn’t a bad time to be selling these guaranteed lifetime income instruments.

Although rates on MYGAs have not been as attractive as they were a few years ago, they  improved from last quarter, which set MYGAs up for a “win.” Sales levels improved nearly 17% from the previous quarter, although MYGA sales were down more than 18% from this time in 2025. Fifty percent of the top ten companies experienced challenging MYGA sales, relative to 1Q2026.

As for sales compared to this time last year, the biggest company in annuity sales increased its own sales nearly 150% from the prior 2Q, which softened the blow on the sales declines from this time in 2025. While it is tough to feel confident in any sales forecasting when there is talk of inflation, changing the Fed Funds Rate, the increasing cost of oil—it all looks like MYGA sales will come up short this year, despite continued lack of competitiveness against Certificate of Deposit (CD) rates.

Fixed annuities with a one-year guaranteed rate had some positive momentum with their sales in second quarter. However, we are talking about a product line that cannot break $600 million in a quarter. Ultimately, sales of traditional fixed annuities were up more than 12% from last quarter and up more than 23% from this same quarter, one year ago.

Having the top carrier in the space increase this quarters’ sales well into the triple digits (from this time last year) certainly helps when other companies are having a tough time closing sales due to the rate environment. We still anticipate that this product line will have an increase in sales for 2026, topping the previous year’s levels modestly.

Fixed indexed annuities

Sales of indexed annuities haven’t been this high for a couple of quarters. An increase of more than 16% left the product line sitting pretty, but then sales dropped almost 4% from the same period, a year prior.

When evaluating the top ten best-selling indexed annuity companies, one cannot help but notice the huge sales increase that the top seller had over 1Q2026. However, a comparison against indexed annuity sales last year illustrates that 60% of the top ten players had mostly double-digit losses. We are anticipating that indexed annuity sales will be down considerably for all of 2026.

Structured and traditional variable annuities

The darling of the deferred annuity market is still chugging along, making impressive increases in sales levels, while still maturing as a product line. Impressive rates on structured annuities have helped buoy these products to increases of 8% over 1Q2026 and a huge leap of more than 21% when compared to this time, last year.

When evaluating how structured annuity sales fared, relative to the previous quarter, you would be remiss to overlook the fact that only 21% of carriers in the market experienced a loss in sales. Perform that same exercise, but with sales during this time, one year ago, and only 16% of product manufacturers experienced a loss in structured annuity volumes. This was a record-setting quarter for structured annuity sales, topping the prior 4Q2025 record by 3.51%. There is no question that 2026 will set a record for structured annuity sales.

What happens when the stock market is on the rise? Variable annuity (VA) sales fare well. This quarter was no exception to that rule, with VAs clocking a nearly 5% increase in sales from the prior quarter and a jump of more than 16% from this time, last year.

Note that only 65% of participants had sales climb compared to 1Q26 and nearly half of those reporting sales experienced a decline from this quarter, last year. While many are discussing a market correction, it seems logical that sales of VAs will fall. However, for now the market still seems to be upward trending, which will no doubt result in VAs closing out the year better than 2025, but by a small margin.

Like MYGAs, single-premium immediate income annuities (SPIAs) are commoditized. When the payout is great, the sales will follow. And payouts must be good because immediate income annuities experienced more than 28% growth over the last quarter and more than an 8% progression when measured against last year, same quarter.

The amazing part? More than 40% of participants experienced sales declines, when compared to 1Q2026. Thanks in large part to the number one seller of immediate income annuities, these products will likely sell more than they did in 2025, but not by much.

Deferred income annuities (DIAs) had a great quarter, despite the fact that 61% of participants experienced a drop in sales from last quarter. That said, nearly a quarter of the companies offering these products had triple digit increases in sales from Q1. Just the two top sellers of the product line had such substantial increases in sales that they effectively canceled-out the sales declines from other carriers.

And while evaluating the nearly 55% sales surge from last quarter, one needs to remember that we are reviewing a product offering that cannot keep pace and seems to wane a little more each year. Wink projects that DIA sales will be up for 2026, but certainly will not set any records.

© 2026 Wink, Inc. Reprinted by permission of the author.

Why Alt-Asset Managers Shouldn’t Own Life Insurers

Alternative-asset-manager-owned life insurers are not simply another category of carrier alongside mutuals and publicly traded stock companies. They represent a fundamentally different ownership structure, built around a different set of interests.

A mutual insurer is owned by its own policyholders, which aligns the owner’s stake directly with the promises being made. A traditional stock insurer owned by a publicly traded parent files audited GAAP financials and reports quarterly to the SEC.

That discipline creates real incentives to keep the numbers accurate and transparent, both for company executives, who face civil and criminal exposure for misstatements, and for the Big Four accounting firms that audit those insurers and have their own franchise on the line.

An alt-asset-manager-owned insurer has neither discipline. It is privately held, reports only on a statutory basis, is often layered with fund-level leverage, and is owned by a fund with a seven-to-ten-year life built to generate a return and exit. The promise it stands behind may not come due for 30 or 40 years.

Asset manager ownership of life and annuity companies is also no longer a marginal corner of the industry. If Aquarian Capital’s pending $4.1 billion acquisition of Brighthouse Financial closes, roughly one-quarter of all U.S. life insurance general account assets will sit under alt-asset-manager control. The risks described below recur because owner and obligation are mismatched at the root.

Six Structural Risk Factors

Conflicted private-credit investment. Moody’s data indicate that the ten largest U.S. life insurers held approximately $352 billion of the industry’s $807 billion in private illiquid bonds—roughly 44% of the total. Several of those insurers are owned or backed by private-equity or other alt-asset managers, creating a significant concentration of private-market exposure within a relatively small group of carriers, which concentrates shock risk in a handful of names.

Alt-asset-manager-owned insurers also tilt toward higher-yield, less-liquid, more-opaque assets. Athene holds roughly 27% in private or illiquid credit, and Security Benefit roughly 26%, much of it loans backed by its own parent’s affiliates.

Private ratings that understate risk. Alt-asset-manager-owned insurers rely heavily on unpublished “private-letter” ratings that often assign more favorable designations than the underlying risk warrants. A preliminary Columbia Business School paper documents the pattern in detail.

Questionable capital relief from reinsurance. Private companies use 360% more leverage from affiliated reinsurance than others, according to ALIRT, and that leverage is only as good as the counterparty behind it. 777 Partners’ co-founder resigned in 2024 amid controversy; the SEC announced fraud charges in October 2025; and the firm filed for Chapter 11 on August 9, 2026, owing A-CAP $1.2 billion, down from a peak of roughly $2.3 billion. That is what happens when the counterparty turns out not to be there.

Thinner capitalization. An April 2025 ALIRT report found that alt-asset-manager-owned insurers carry roughly one-third less statutory capital than other U.S. life companies, a gap made more troubling by their reliance on affiliated reinsurance. PHLV’s $2B+ deficit vividly illustrates the risk to policyholders.

Absence of data relative to public companies. There are no SEC filings, no analyst or short-seller scrutiny, and, per the point above, increasingly no public rating on the hardest-to-value assets. A public company carries the countervailing discipline of quarterly SEC filings and Big Four audits. A privately held insurer files only statutory financial statements with its home-state regulator, where its assets are often carried at cost for statutory purposes.

Regulatory arbitrage. These companies domicile-shop for a friendlier regulatory posture. Iowa now regulates roughly $1.3 trillion in insurance assets and is the domicile of choice for Athene, Transamerica, F&G, American Equity, and the Sammons insurers, while New York’s stricter rules make it a domicile many avoid. They then reinsure much of the resulting liability offshore through structures engineered to fall just short of legal “affiliation.”

Security Benefit’s own Bermuda sidecar, SkyRidge Re, assumed roughly 80% of the carrier’s ceded reserves while claiming non-affiliated status, even though Security Benefit’s parent holds a stake in SkyRidge’s parent. The record here cuts both ways. A-CAP successfully blocked state regulators in Utah and South Carolina from suspending further sales, and yet 777 Partners — the counterparty at the center of both cases — filed for Chapter 11 on August 9, 2026, still owing A-CAP $1.2 billion.

When the underlying risk is real, but the legal case cannot be made to stick, that tells us something about the adequacy of the available tools.

Where This Leaves Us

None of this proves that every alt-asset-manager-owned carrier is mismanaged or that every sponsor is acting in bad faith. Delaware Life says it did not know. A-CAP “won” both of its regulatory fights by stopping state regulatory actions. The rating agencies, the auditors, and the state examiners all did something resembling their jobs. The pattern nonetheless keeps recurring.

Capital looks adequate until it is not. Reinsurance looks unaffiliated until the org chart says otherwise. Counterparties look solvent until they file for bankruptcy owing more than a billion dollars to the carrier that trusted them. One reading of this is that it is what a young, fast-growing corner of the industry looks like before it matures. The other is that the mismatch between an investor’s exit horizon and a 30-to 40-year policy obligation is structural rather than a growing pain. We think the second reading deserves more weight than it currently receives.

We cannot examine what we cannot see. That is ultimately the problem with alt-asset-manager ownership of life insurers. The issue is less that any given sponsor is dishonest and more that the ownership structure itself removes the tools that let anyone catch problems early: audited GAAP financials, quarterly SEC filings, public ratings, and analyst and short-seller scrutiny.

Combine that opacity with the six structural risk factors above and with the misalignment between a fund’s short exit horizon and a policyholder’s decades-long promise, and we find it hard to recommend an alt-asset-manager-owned carrier when a comparable, well-run mutual or publicly traded company is available instead.

Author’s note: This document is intended solely for registered representatives, investment advisers, and other institutional partners. The information contained herein includes discussions of sophisticated financial concepts, strategies, and institutional product data that are not suitable for retail clients. By accepting this material, you agree that you will not copy, forward, or otherwise show or disclose this document, or any part thereof, to any retail investor. Broker-dealers and financial advisors are responsible for ensuring that their use of this material complies with all applicable internal procedures and FINRA rules.

© 2026 Valmark Securities, Inc. Excerpted by permission of the author.

When the AI Bubble Bursts, Who Will Be Left Holding the Bag?

A new paper making a stir in the financial press spells out the dangers to which private equity-owned life insurance companies are exposed by private credit funds with large portfolios of loans to software and AI companies. It’s a complicated story that could have enormous consequences.

Pranjal Drall and Andrew Granato, the report’s authors, argue that some of these insurance companies could become insolvent if these loans crash. And an unanticipated consequence of a 60-year-old rule that protects insurance company policy holders from losing all of their life insurance benefits or annuity payments could leave taxpayers holding the bag.

Let’s step back to understand some of the backstory. In 2022, I wrote about private equity firms gobbling up life insurance companies, and in 2026 about the risky, high-fee investments these companies were making with people’s life insurance and annuity premiums. Private equity firms are best known for theprivate equity (PE) buyout funds they sponsor. These funds buy up anything from doctor’s practices to single-family homes to youth sports leagues. PE funds use money committed by their investors as the down payment (the equity) on these acquisitions, and they use lots of debt to acquire companies in what are known as leveraged buyouts (LBOs).

As PE firms diversify their holdings, life and annuity insurance companies are an attractive target because they amass premium income, but may not need to pay out benefits for years or even decades. PE’s interest in owning life insurance companies emerged in earnest in 2009 following the Great Financial Crisis, and accelerated in the early 2020s. While traditional insurance companies mostly invested premium income in corporate and Treasury bonds, PE firms count on earning high fees for managing risky investments made with these assets, and on profiting from the spread between what it owes policyholders and what its investments earn.

There are no legal barriers to PE-owned insurance companies using their assets to support struggling companies also owned by their PE owner, and no prohibition on selling poorly performing loans of a PE-owned company to an insurance company owned by the same PE firm. PE-owned life insurers also extract value by transferring assets and liabilities to a shadow reinsurer it owns or is affiliated with. This can reduce the insurance company’s tax liabilities, lower its capital requirements and hide the extent of the risk it is exposed to.

Private Credit Funds Make Big Bets on Software and Data Centers

Stricter financial regulations put in place following the Great Financial Crisis were intended to prevent similar catastrophes in the future. The regulations limited the amount of debt that regulated financial institutions could put on a company, crimping the ability of PE funds to use as much debt in LBOs as they wanted. Banks were restricted from making riskier loans, and this resulted in small- and medium-sized companies finding it difficult to get bank financing.

Immediately, private equity firms stepped into the breach and created private credit funds to make direct loans to companies frozen out of public financial markets. Private credit funds are sponsored by investment firms, including PE firms. They are not subject to the regulations intended to make the financial system safer. They operate in the shadows, making risky loans to companies, many of whom don’t qualify for bank loans. Today, private credit funds hold $3 trillion in largely unregulated, high risk, opaque loans — many made to companies owned by PE firms.

Private credit funds have been a hot investment for the last 16 or so years. These loans are not subject to the rules that govern corporate bonds. Because the loans are risky, lenders demand a premium and borrowers pay high interest rates — a profitable situation that rewards investors in these funds. The funds have bet big on software firms that create code and develop management tools that businesses subscribe to, providing them with multi-billion-dollar loans.

The software tools manage various business operations — customer relationships, workflow and corporate spending — and are collectively known as Software as a Service (SaaS). Private credit funds are also behind the multi-billion-dollar loans to the huge data centers that AI firms are building to train their latest AI models.

Where do these billions of dollars come from? While there are multiple sources of funding for private credit funds — including investment banks like Goldman Sachs that are barred from making these loans directly, and pension funds looking for lucrative payoffs — private equity-owned insurance companies figure prominently as a source of capital for these funds. Investments in SaaS have been the bread and butter of private credit funds. The recurring income these companies generate from business subscribers have enabled them to make payments on their massive loans; default rates have been low.

But share prices of these software companies cratered in 2026 under pressure from Claude, AI company Anthropic’s code-writing frontier model and other similar models. As a whole, these AI tools are undermining the SaaS business model and challenging the “assumptions around software growth, pricing power and borrower durability.

“ Investors in private credit funds worry that many of the SaaS companies will not be able to repay their loans. Similar doubts are being raised about the construction of super expensive data centers that private credit funds are financing amid rising concerns about an AI bubble and anxiety about what will happen if the bubble bursts. Will many of the data centers become white elephants, deserted by the AI firms that planned to use them to develop new AI models? Will the return on investment in models trained in these expensive data centers justify business spending on these high-cost AI models? Will the much cheaper Chinese AI models out compete the US models and take market share away from American AI companies? These questions are raising doubts about whether all of these loans can be repaid. And if the loans can’t be repaid, what then?

Insurance Regulations Could Bail Out Risky PE Bets

PE-owned life insurance companies will see their investments in private credit funds crushed, marked down substantially or even wiped out. Private credit default rates above 15% may lead some insurance companies to become insolvent and unable to make good on the life insurance payouts or annuity payments promised to beneficiaries.

At that point, state Insurance Commissioners will step in. Rules put in place decades ago to protect beneficiaries of insurance companies enable the commissioners to require the remaining life insurance companies in the state to pay into a special guaranty fund that will make good on the policies held by the beneficiaries of the defunct company, up to a cap of about $300,000 on life insurance and about $250,000 on an annuity. That varies by state. Insurance companies not affiliated with a PE firm and that didn’t make risky bets on private credit will be required to bail out the failed insurance companies that did. And the PE firm that owned the insolvent company will get off scot-free and not have to pay anything. That creates a moral hazard and seems to be a miscarriage of justice.

But the story doesn’t end there. In 44 states, these payments are fully creditable over five years against state taxes on premium income. That means that, ultimately, it is taxpayers in those states that provide the backstop when software and/or AI companies can’t repay their loans to private credit funds, and a PE-owned insurance company that invested in private credit funds becomes insolvent. The result is, as the report’s authors point out, “a system that socializes losses.”

© 2026 Eileen Appelbaum. Reprinted by permission of the author.

Advisors’ allocations to private capital could reach $4.2T in five years: Cerulli

U.S. financial advisors currently allocate $2.2 trillion to less-than-fully-liquid private capital, and could manage an additional $2 trillion in the next five years “if the buildout of interval fund solutions, the adoption of other less-than-fully-liquid private capital product, and the streamlined access offered by alternative asset allocation models continues to grow,” according to The Cerulli Report—U.S. Private Markets 2026.

Many advisors believe that allocations to private assets will demonstrate value-add to clients and respond to investors’ demand for income-generating investments, Cerulli surveys show.

To scale private market solutions across retail channels, partnerships between traditional and private capital managers will be key. “Traditional asset managers seek differentiated capabilities that can enhance their product offerings and support more competitive value propositions,” said Daniil Shapiro, director at Cerulli.

“Private capital managers often lack the distribution scale and brand recognition required to penetrate retail channels, particularly beyond the ultra-high-net-worth segment and into the broader affluent market.”

Distribution is expanding into models, multi-asset vehicles, and defined contribution (DC) plans, creating a greater need for collaboration among asset managers, technology platforms, turnkey asset management providers (TAMPs), trust companies, and recordkeepers, Cerulli said in a release.

© 2026 RIJ Publishing LLC.

Mapping Private Markets, the Apex of the Bermuda Triangle

In a recent report, “Understanding the Growth of Private Markets: Structural Shifts in the Investment Industry,” the CFA Institute’s Research and Policy Center has done a useful service to Bermuda Triangle watchers by mapping the world of private market assets and its stakeholders. (See chart above/at right.)

That world represents one of three three legs of what RIJ calls the Bermuda Triangle strategy, which includes, within the same holding company: an alternative asset manager (e.g., Apollo, Blackstone, KKR, Eldridge, Guggenheim Partners), one or more life insurers that issue fixed deferred annuities (e.g., Athene, F&G, Global Atlantic, Security Benefit, Delaware Life) and an affiliated reinsurer in Bermuda or the Cayman Islands.

[Long-standing, stalwart life insurers like Prudential, MassMutual, Lincoln Financial, Pacific Life and others have adopted parts of this strategy. They’re more likely to sell registered index-linked deferred annuities (RILAs). These are SEC-regulated contracts that these insurers distribute through their familiar broker-dealer partners instead of through the insurance market organizations (IMOs) that emphasize fixed annuities.

The private market investment, and the alt-asset managers, can claim to represent the apex of the Triangle, since the other two legs are there primarily to help finance private credit and related high-yield assets. The life insurers buy the asset managers’ alt-assets and the reinsurers expand the life insurers’ annuity sales capacity by assuming the cost of some of their risks and letting them conserve capital or “release” it for stock buybacks or new ventures.

So, if you want to understand the Bermuda Triangle–or the increasing distribution by alt-asset managers of their private market products through retail channels (via exchange-traded funds) or through institutional channels (via 401(k) plans, it helps to understand the apex of the triangle. This chart will help.

Understanding The Private Market Ecosystem Stakeholder chart

Start at the low end of the chart. Asset Owners and Investors (bottom row) deploy capital upward through access vehicles—limited partner commitments to venture capital (VC) and private equity (PE) fund partnerships, business development companies (BDCs), interval funds, evergreen structures, and infrastructure funds—into four private market channels.

Corporate Issuers and Private Enterprises (top) access financing downward: startups and growth firms via venture capital, mid-market firms via private credit, restructuring and buyouts via private equity, and real asset projects via infrastructure funds. The Intermediaries bar (center) represents the asset managers, banks, NBFIs, and placement agents that channel capital between the two sides. Exit routes connect private to public markets (IPOs, trade sales).

The dashed connection between Private Equity and Private Credit reflects frequent cross-channel financing. The Policymakers and Regulators frame (yellow border) represents the regulatory architecture shaping the ecosystem—rules include Basel III, accredited investor reforms, defined contribution (DC) pension access, and dedicated fund structures (e.g., European long-term investment funds [ELTIFs], long-term asset funds [LTAFs]). GP stands for general partner; HNWI stands for high-net-worth individual.

© 2026 RIJ Publishing LLC.

The Animus behind DOL’s ‘Amicus Briefs’

A human resources manager was once asked why the participants in her company’s 401(k) plan didn’t have a seat on the plan’s investment policy committee. “What do you mean?” she said. “Everyone on the committee is a participant.”

There’s an ambiguity in the regulation of 401(k) plans under the Employee Retirement Income Security Act of 1974 (ERISA). Where’s the line between plan sponsors and plan participants? And which side of the line does, or should, the Department of Labor (DOL) stand on?

Is there a contradiction between a plan sponsor’s duty to act solely in the participants’ best interests and an employer’s option not to sponsor a plan at all if the duties seem too onerous… in terms of litigation costs?

Different administrations in Washington appear to answer differently. By filing so-called “amicus briefs” on behalf of the corporate plan sponsors—the defendants—in several participant-led, ERISA-based class action suits, the Trump DOL has signaled its friendship with, logically, the corporations.

For example:

  • On July 10, a DOL amicus brief urged the U.S. Supreme Court to affirm a lower court’s dismissal a participant-led suit contending that in Anderson v. Intel, Intel Corp. acted imprudently by investing its 401(k) plan funds in hedge funds, private equity and other “non-traditional,” “allegedly risky” assets.
  • On July 21, a DOL amicus brief in Doherty v. Bristol-Myers Squibb asked the Second Circuit (Southern New York) to clarify the business requirements for corporate decisions to execute pension risk transfers (PRTs). This suit challenged Bristol-Myers Squibb’s decision to exchange its defined benefit plan assets for a group annuity issued by life insurers in Athene Holding, a segment of Apollo Global Management.
  • On July 24, a DOL amicus brief urged the U.S. Court of Appeals for the 4th Circuit (Eastern North Carolina) to affirm a district court’s decision to dismiss the claims in Stana v. SAS Institute Inc., that the employer breached its fiduciary obligations by not using forfeited funds (i.e., employer “matching contributions” forfeited by employees who separate from the employer before their contributions vest) for plan expenses.

It’s a truism that corporations’ biggest fear in sponsoring 401(k) plans, in picking service providers, and signing off on investment menus, is getting hit with federal class-action suits where participants question their decisions and demand tens of millions of dollars in compensation for alleged violations of ERISA’s requirement that sponsors act prudently and “solely” in the interests of participants.

In its amicus briefs, the Trump DOL addresses that fear, and leans in on behalf of the plan sponsors. Besides supporting the plan sponsors’ legal positions, the DOL warns that participant-led ERISA lawsuits, and the plaintiffs’ attorneys who bring them, threaten to discourage corporations from sponsoring plans at all. That reverses the Obama DOL’s approach.

These cases have other implications—pertaining to a plan sponsor’s choice of a “Bermuda Triangle” annuity issuer (in Doherty v. Bristol-Myers Squibb) and a 401(k) plan sponsors right to put alternative investments in its plan (Anderson v. Intel). But let’s look first at the Trump DOL’s shot-across-the-bow at participant-led suits in general.

‘Disincentivizing employers’

In its press releases, the Trump DOL gets right to the point. Its interventions in these cases aren’t just tactical but also strategic: to discourage future participant-led federal class-action suits against 401(k) plan sponsors.

A DOL’s press release called its amicus brief in Anderson v. Intel “one in a series filed by the DOL focused on ending the overuse of litigation against ERISA retirement plans and those who manage them.” The department’s press release about Stana v. SAS Institute said, “Continued litigation of this type could have the unintended effect of disincentivizing employers from creating retirement plans.”

In its amicus brief in Stana v. SAS Institute, the DOL took close aim at plaintiffs’ attorneys when it wrote, “private-party ERISA litigants (or, more specifically, private-party ERISA litigators) are now trying to contort these well-intentioned shields [i.e., “ERISA-imposed fiduciary duties” on plan sponsors] into cynical swords that often hurt the American worker.”

In the Bristol-Myers case, the DOL brief “argues that pension risk transfers benefit both employers and beneficiaries when not disrupted and litigating business decisions can hinder or eliminate benefits.” The department added that “continued litigation could deter employers from derisking their plans and ultimately upset the balance Congress established between federal and state regulation.”

The DOL characterizes decisions to trade a defined benefit plan for a group annuity as “business decisions” rather than participant-driven decisions, and characterizes pension risk transfers as a defined benefit (DB) plan sponsor’s effort to “derisk” a DB plan rather than a decision to reduce the sponsor’s costs in operating the plan.

Plaintiffs’ attorneys representing participants feel differently. “The DOL of old would frequently file amicus briefs on behalf of plaintiffs,” said Edward Stone, a Greenwich, CT, ERISA plaintiffs’ attorney. “We are seeing a DOL made in Trump’s image.  It has surrendered its ERISA watchdog role and morphed into a big player in the game of regulatory Jenga. It will inevitably lead to huge policyholder losses and get out of jail free cards for those foxes guarding the henhouse of retirement security.”

The future of private market assets in 401(k)s

The DOL’s intervention in Anderson v. Intel struck one knowledgeable observer as aligned with the Trump administration’s August 2025 executive order blessing alternative assets, including private equity, private credit, retirement income-generating tools, and even cryptocurrency, in 401(k) investment menus.

In that case, first filed in slightly different form a decade ago, former participants sued Intel for keeping hedge fund and private equity investments in its customized target-date fund series even as these investments hurt the funds’ performance. A federal appellate court has affirmed a lower court’s dismissal of the participant’s suit.

The Circuit Court judge ruled that the plaintiffs hadn’t provided a suitable benchmark against which to measure the performance of the Intel TDFs with private market assets. (The case is a bit unusual: Intel had used alternative investments in its defined benefit plan. When designing the target-date fund for its 401(k), the computer chip maker put alternative assets there as well.)

Mark Fortier was an executive at AllianceBernstein, the asset manager that succeeded Intel as investment manager of Intel’s target-date fund. Alternative asset managers, he said, might try to use the Intel ruling, along with DOL’s amicus brief, to show plan sponsors that they can include private market assets in their target date funds as long as they carefully look for and find an appropriate benchmark.

“The [DOL] amicus briefs [in the Intel case] give alternative asset managers marketing material to give sponsors,” Fortier told RIJ. “The asset managers like that story,” he said. “They can say, ‘Don’t worry, a prudent [due diligence] process will set you free.”

But the ambiguous nature of private market assets—are they volatility-reducing diversifiers or yield enhancers—might hinder the search for a suitable benchmark for their expected performance in target-date investments that include an allocation to them, Fortier believes.

“This is a subtle issue that the Intel suit doesn’t address,” he told RIJ. “What is the asset class that you’re trying to benchmark?” Do private market assets/alternatives deliver a higher return for the same risk as public market assets, as the alt-asset managers say? Or do they deliver the same returns for a lower risk, as the hedge fund managers say?

You can’t have it both ways, he said: “The “no free lunch” advocates like myself don’t buy it.” And a plan sponsor can’t choose an appropriate benchmark until it determines what alternative assets are supposed to do.

Amicus v. animus

ERISA was passed in 1974, near the end of a decade of civil unrest in the U.S. and of new “civil rights” legislation that recognized minority rights and that was aimed at placating, rather than punishing, much of the unrest. That legislation spawned thousands of pages of regulations, which put teeth in the laws.

Champions of a myriad of newly-articulated rights—not only of people of color but of voters, women, the environment, the aged and disabled, animals, tenants, the incarcerated, and pension plan participants—were soon able to wield those regulations as legal weapons against large corporations in class-action suits that organized previously diffuse interests into powerful “interest groups.”

From the beginning—no later than the 1968 presidential election—the wave of civil rights reform sparked a counter-reformation from both Democratic and Republican administrations. Their animus was directed at “regulations” and “red tape” in general, but it often included criticism of the litigation targeting politically-influential corporations, filed by plaintiffs’ attorneys whose fees were contingent on victory in court, that the regulations made possible.

The DOL’s recent ERISA briefs signal the Trump administration’s amicus with that animus.

© 2026 RIJ Publishing LLC.

Indexed annuity updates from Corebridge and Delaware Life

Corebridge enhances Power Series

Corebridge Financial, whose merger with Equitable nears completion, has added Protected Growth Benefit and “preset allocation options” to select versions of The Power Series of Index Annuities. The changes will enhance “the accumulation and diversification capabilities” of the company’s index annuities, a release said.

Protected Growth provides a guaranteed minimum accumulation benefit (GMAB). “While there are no fees for this optional product feature, interest crediting rates are lower when Protected Growth is elected,” according to the release. The Protected Growth Benefit rate for contracts with a 7-year surrender period is currently 26.25% and 17.5% for contracts with a five-year surrender period.

A contract with a $100,000 premium would have a guaranteed minimum contract value of $126,250 after seven years or a guaranteed minimum contract value of $117,500 after five years, depending on the term of the contract. The Protected Growth Benefit is available only on Power Index 5 Plus and Power Index Plus and is not available in California or New York.

Contract owners can pick any of five pre-set, blended indexing strategies – U.S. Stability, Global Stability, Balanced, U.S. Growth, and Global Growth – that include allocations to the S&P 500, Russell 2000, PIMCO Global Optima Index, MSCI EAFE, ML Strategic Balanced Index and Franklin Quality Dividend.

Pre-set allocation options are available in select products within The Power Series of Index Annuities family. There are no fees associated with this product feature. For more information, visit What We Offer on corebridgefinancial.com.

Delaware Life introduces TrackGuard+

Delaware Life Insurance Co. has launched TrackGuard+, a bonus fixed index annuity (FIA) that adds “a high upfront premium bonus” and “enhanced in-contract liquidity” to several index crediting strategies and the customary principal protection.

TrackGuard+ features:

  • A 21-26% bonus on the first-year premium. The bonus varies by state and is subject to a recapture schedule if the contract is surrendered during the surrender period. The client keeps all the interest credited to the bonus from contract issue even if the bonus is later recaptured.
  • Available indexes are the S&P 500 Dynamic Intraday TCA, Nasdaq-100 Volatility Control 12%, BlackRock U.S. Equity Bitcoin Balanced Risk 12%, Barclays Aries, and the S&P 500.
  • Beginning in the second contract year, for 0.95% fee, clients can carry forward any unused free withdrawal percent from the prior year, stacking on top of the standard 7% annual allowance for up to a maximum of 28% penalty-free access in a single year. The benefit applies even after a prior-year withdrawal.
  • Starting in the fifth contract year, policyholders are guaranteed at least 100% of premium (less withdrawals and net of market-value adjustments, recaptured bonus, and contingent deferred sales charges) on surrender. The benefit increases to amounts exceeding 100% of premium in later years.
  • At the end of year 10, the Premium Guard benefit ensures the account value is at least equal to premiums plus premium bonus (less prior withdrawals and recaptured premium bonus). The Premium Guard Credit will be applied pro-rata across the current allocations after any applicable fees are taken.

© 2026 RIJ Publishing LLC.

CANNEX’s new CEO: Gary Baker

CANNEX, a leading provider of pricing, data and analytics for annuities in North America, and for banks’ term deposits and guaranteed interest contracts (GICs) in Canada, has named Gary Baker as its new Chief Executive Officer.

Previously the Chief Operating Officer of CANNEX, Baker succeeds Lowell Aronoff, who cofounded CANNEX in 1984. Aronoff will become the chairman of a newly created board of directors.

Baker brings more than 30 years of financial services experience focusing on retirement products, including prior executive roles at Mass Mutual and GE Capital, and has spent the last 16 years helping shape CANNEX’s growth.

“The pace of technological change in our industry is faster than at any point in CANNEX’s history, and our clients expect us to move with it,” said Baker. “We are accelerating our investment in AI-enabled infrastructure to build the next generation of data and analysis solutions in support of regulatory standards in the U.S. and Canada.

“This is a natural evolution of the strong foundation Lowell and our late cofounder, Alex Melvin, built over the past 40 years, and I’m energized to lead CANNEX into this next phase.”

“Over the past 16 years, Gary has been an incredible leader within CANNEX,” said Aronoff. “He understands what makes CANNEX unique and how to leverage our strengths to capitalize on the opportunities we see to grow the business at this critical moment.”

© 2026 RIJ Publishing LLC.