Archives: Articles

IssueM Articles

Gold, Not Tariffs, Saved the 1890s

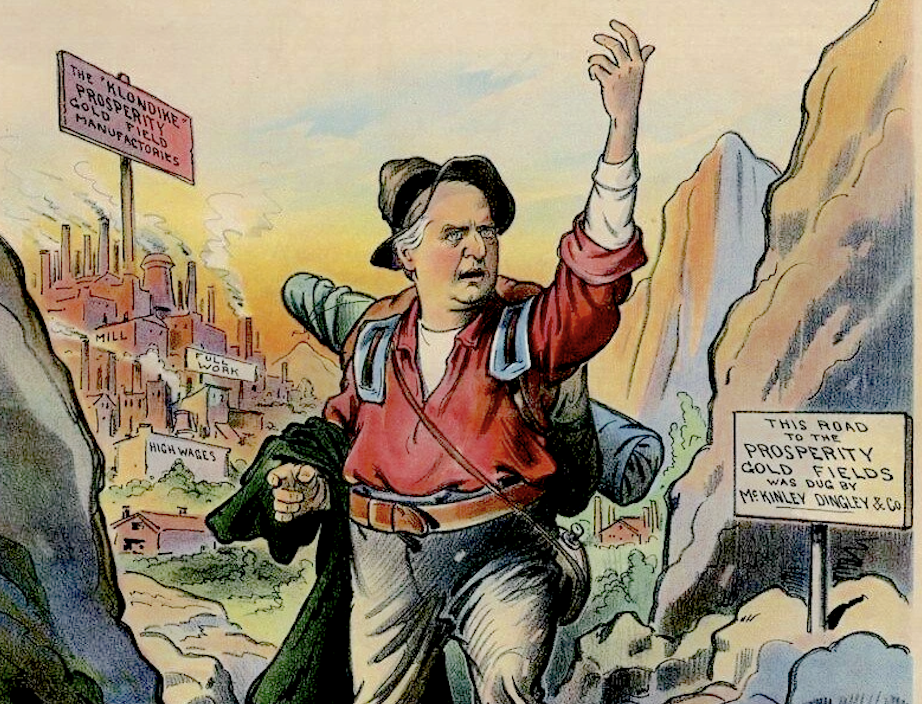
Yes, President William McKinley was a tariff-championing Republican. Yes, Congress passed several tariff bills in the 1890s. And, yes, the U.S. enjoyed an economic boom in the second half of the 1890s—a relief from the depression of 1893.

But neither McKinley nor the tariffs can take credit for enabling the U.S. to close out the 19th century on a high economic note and enter the 20th century—the American Century—as a global dynamo.

No. Historians attribute the boom to:

  • Discoveries of gold in Alaska, the Yukon, and South Africa in the mid-1890s

  • The Spanish-American Wara, declared and ended in 1898

Last April 2, “Liberation Day,” President Trump announced dramatic new tariff levies on most of the countries of the world, including America’s closest trading partners. He effectively put an end to our 30-year experiment in unfettered free trade and “globalization.”

The following day, the U.S. stock market dropped 10%. Global confusion ensued as leaders of Canada, Mexico, Germany, China, Japan and Vietnam, to keep the list short, struggled to figure out how their export-driven economies would be affected.

Why tariffs?

President Trump claimed that William McKinley, president from 1896 until his assassination in 1900, had employed tariffs to raise revenue, protect domestic industries from cheap foreign competition, and stimulate the U.S. economy.

He argued tariffs could drive foreign direct investment into the U.S., revive U.S. manufacturing, and reverse America’s huge trade deficit (in goods, not services) with the rest of the world—and that they could juice up the U.S. economy today.

This week, as some of the tariffs announced last April are scheduled to take effect, a hunt for a historical basis for bringing tariffs back won’t turn up much. While tariffs were a major political football after the Civil War, there’s no good evidence that they turned the U.S. economy around after the Crash of 1893.

Here’s Doug Irwin, a tariffs expert at Dartmouth, writing in an April 2000 National Bureau of Economic Research paper, Tariffs and Growth in Late Nineteenth Century America.:

“The U.S. experience in the late nineteenth century is often appealed to as evidence that high tariffs can prove beneficial to economic growth and development. Upon closer scrutiny, it is difficult to establish this claim.”

America’s Second Gold Rush

Most Americans probably remember reading about the gold rush of 1849, after the precious metal was discovered at Sutter’s Mill in California. Less discussed is the gold rush of 1896, when gold was discovered at Bonanza Creek in Alaska’s Klondike, in Canada’s Yukon, in South Africa, and in Australia. The flood of gold enriched not just lucky miners but entire countries.

At the time, a country’s gold reserves formed the basis for the quantity and value of its currency. And in the early 1890s, when panicky British investors were selling off their U.S. holdings, literal boatloads of gold were floating away from the U.S.

There’s widespread agreement among economic historians that gold from Alaska and elsewhere, which the U.S. Treasury bought with newly issued “gold certificates,” was a dominant factor in pulling the U.S. out of the long post-Civil War deflation—a reversal of the inflation associated with the war.

The record is unanimous on that point. And largely silent on tariffs.

Milton Friedman, the Nobel laureate in economics, wrote in his 1963 classic, A Monetary History of the United States, 1857–1960 (p. 91), referring to the campaign by William Jennings Bryan and Western farmers to have silver supplement the American gold reserves, which could increase the money supply and reverse the deflation that held down wheat and corn prices.:

Placer miner panning for gold in Klondike

“The secular decline from the 1860s almost to the end of the century… was reversed in the 1890s by the fresh discoveries of gold in South Africa, Alaska, and Colorado, combined with the development of improved methods of mining and refining. After 1897, ‘cheap’ gold achieved the objectives that had been sought by the silver advocates.”

The discovery of gold ended the farmer’s quest for “bimetallic” backing of U.S. paper money. Here’s Ron Chernow in his 1990 National Book Award–winning biography of J.P. Morgan:

“The Yukon gold rush and gold strikes in South Africa and Australia helped expand the U.S. money supply and led to higher prices. The bitter deflationary politics of the late nineteenth century subsided.”

The nation’s money supply, and its creditworthiness, depended on its stock of gold, and the fact that foreign creditors could redeem dollars for gold contributed to a massive outflow of gold after the confidence-shattering crash of 1893. In the West, farmers believed silver could back dollars and lift the money supply. The U.S. Treasury and New York bankers contemplated floating bonds to buy gold.

Gold strikes in Alaska and elsewhere rescued farmers and bankers alike. It was not a case of deus ex machina; the pre-Klondike global shortage of gold incentivized a worldwide search for the precious metal (throughout history the preferred method for paying mercenaries and settling international debts) and stimulated the development of more efficient refining methods. Starting in 1896 on (see chart below) the U.S. gold supply did nothing but grow. For most of the previous decade, gold stocks were falling and the U.S. suffered from deflation.

The War with Spain

The tariff debates of the 1880s and 1890s were not unrelated to the gold issue. The common denominator was deflation and falling prices. Democrats touted low tariffs as the solution, while Republicans saw higher tariffs as the remedy. But tariffs were a sideshow. The real problem was the Treasury’s shortage of gold. As Irwin writes:

“The country’s monetary policy under the gold standard, not the tariff, was responsible for the deflation of this period.”

Then came the four-month war with Spain in 1898, which “brought a wave of prosperity… ‘After war will come the piling up of big fortunes again; the craze for wealth will fill all brains,’” wrote economic historian Joseph Dorfman in The Economic Mind in American Civilization, Vol. 3 (p. 230), quoting contemporary observer William Dean Howells, editor of The Atlantic Monthly.

Teddy Roosevelt leading ‘Rough Riders’ in Cuba, 1898

Tariffs were also cousins to the noisy, brief war in Cuba. The common denominator in this case was sugar. Tariffs on sugar provided steady revenue for the U.S. Treasury, but on-and-off tariff policy on sugar in the 1890s created a boom-bust cycle in Cuba, the site of U.S.-owned sugarcane fields and the main source of raw sugar for U.S. refiners.

Economic instability helped spark the Cuban War for Independence from Spain. Spain began burning sugar plantations. The U.S. intervened, Teddy Roosevelt and his Rough Riders took possession of Cuba, and U.S. refiners ended up in control of Cuban sugar (and Cuban politics) until the 1959 communist revolution, led by Fidel Castro.

Victory over Spain gave the U.S. dominion over not just Cuba but also the Philippines. Almost overnight, the country became a global power, with new commitments and opportunities in Asia. American exports later helped European countries fight (and recover from) World Wars I and II, and the U.S. became the world’s biggest creditor nation. Today, we’re the world’s biggest debtor.

Paradoxically, that makes us rich. Much of the world’s savings is parked here. We can afford to run a large trade deficit because we’re wealthy, because everyone everywhere gladly accepts dollars, and because foreigners recycle their export-earned dollars back to the U.S. by investing here or buying our Treasuries.

New U.S. protective tariffs, or even the threat of tariffs, aren’t likely to reverse that mega-trend. The Trump tariffs appear to be bargaining chips for deals he’s making on the side. McKinley could never have imagined that.

© 2025 RIJ Publishing LLC. All rights reserved.

Private credit, reinsurance top the news

Bond analysts see pros and cons of alternatives in 401(k)s

In an August 29 new research brief, “Private Credit: Making the Most of 401(k) Democratization,” bond analysts at KBRA analyzed the potential impact of President Trump’s August 7 executive order “to potentially ease regulatory barriers that have limited defined contribution (DC) retirement plans’ access to alternative investments,” including private credit.

“Access to alternatives is already a common and growing feature in the retirement accounts of defined benefit (DB) plan savers (typically government employees and legacy corporate pension beneficiaries),” the analysts wrote. “This democratization seems profoundly fair, given that alternative investments have historically outperformed comparable public market options, on average.”

But they saw potential dangers in democratization.

“Regulatory Scrutiny: The Department of Labor and the Securities and Exchange Commission (SEC), will likely spend significant time monitoring how alternative investments are being democratized. …Over time, the probability of additional regulation is high.

Missteps: The first AAM that falls short of performance expectations—or the inevitable bad actor—may face litigation, which could engender pushback against the entire industry. This will create additional regulatory scrutiny, headline risk, or a negative perception of alternatives.

Buyer Beware: Fund-level liquidity [of alternatives] is often limited to match asset-level liquidity by some form of gating or redemption deferral mechanism. This differs from most public market funds. …Additionally, fees for alternative investment vehicles are higher in most cases.”

Via KBRA.

Private credit funds attract revenue at record pace

The Financial Times reported on September 2 that “Affluent individual investors in the US have pumped $48bn into private credit funds in the first half of this year,” and could surpass “the high­water mark of $83.4bn set last year, according to investment bank RA Stanger.”

“The inflows underscore the growing importance major private investment groups are now placing on individuals, with analysts at rating agency Moody’s calling it ‘one of the biggest new growth frontiers in the industry,’” the Times said.

Private asset groups “lobbied heavily to open the broader US retirement market up to private equity and credit, which culminated with US President Donald Trump’s executive order last month paving the way for their broader inclusion in 401(k) plans.”

The private asset industry apparently needs more revenue. “Fundraising in traditional drawdown private credit funds has slowed alongside a broader downturn for the leveraged buyout industry, which has struggled to return capital to investors in the years since the Covid-19 pandemic and has, in turn, suffered weaker inflows,” the article said.

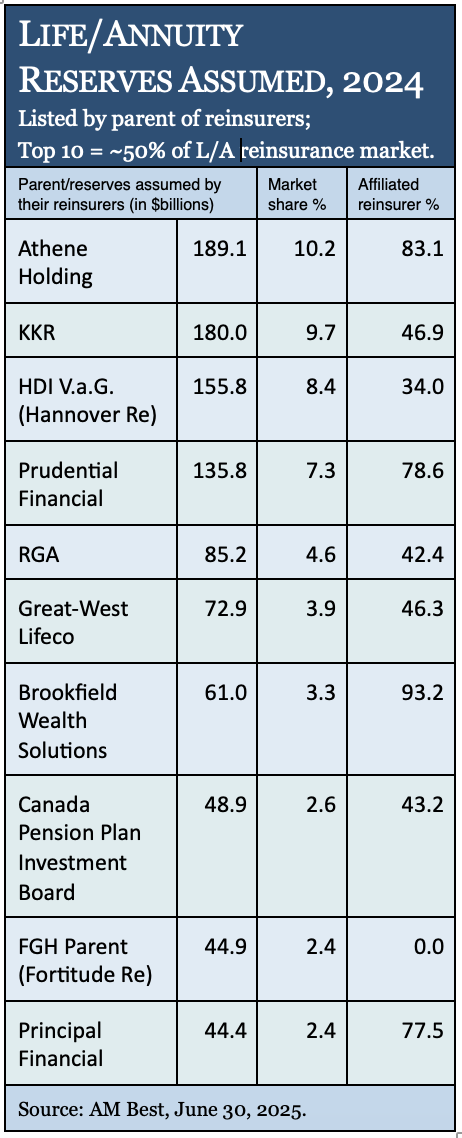
Offshore reinsurance increases life insurer leverage: AM Best

“Asset-intensive transactions flow involving life insurers for capital efficiency has continued to tremendously increase and has intensified utilization for offshore reinsurance connected to mostly private equity interests, especially in the islands of Bermuda and Cayman,” AM Best reported August 28.

“Private equity-backed insurers and investment managers, along with some prominent insurers, have leveraged their premium flows with offshore reinsurance structures, including the increase in sidecars activity lately for capital efficiency,” wrote analysts in a report, “Global Life/Annuity Reinsurers’ Capital Management Strategies Evolve to Achieve Target Returns and Meet the Needs of Cedents.”

Best analysts expressed some concern about rising leverage, which reinsurance can promote by reducing—by design—the capital backing liabilities. “Concentration in certain reinsurers and incremental reinsurance leverage can somewhat diminish a company’s capital quality and place pressure on the group’s overall balance sheet strength assessment.”

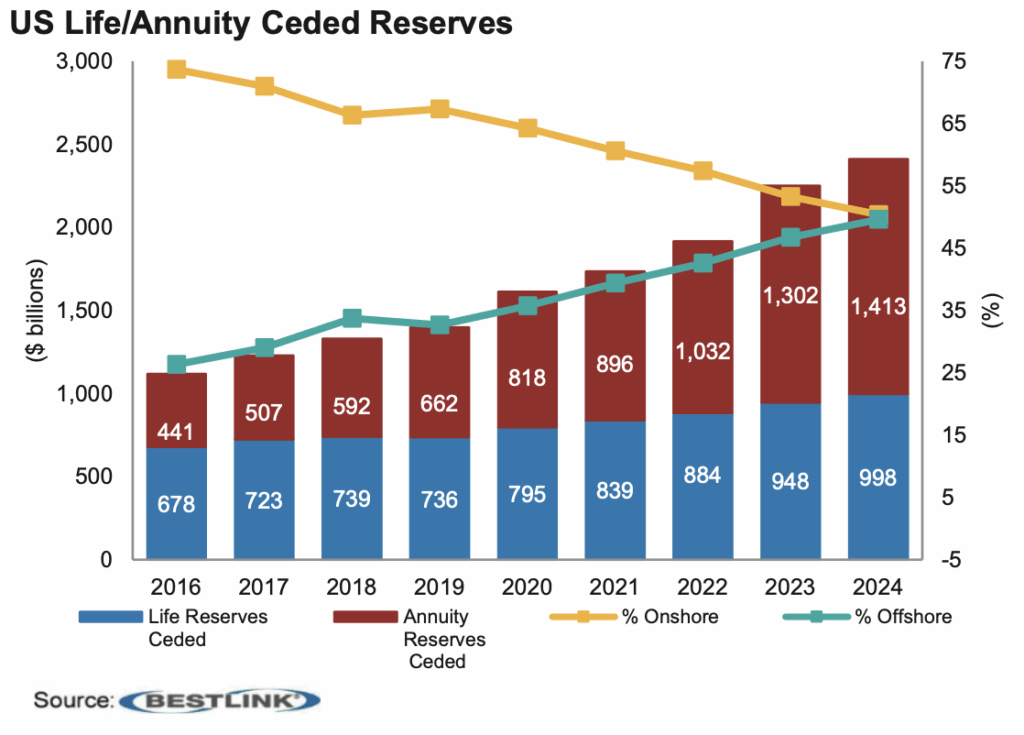
“The amount of annuity reserves has expanded over 10% in each of the last four years, and ceded reserves have doubled from 2016 to 2024. The notable annuity growth is likely to continue, and more companies may look to reinsurers to manage growth and capital levels,” the report said.

“Offshore reinsurers can [often] choose the accounting system for their regulatory reporting (e.g., adjusted or modified US risk-based capital (RBC), US GAAP, IFRS 17, local statutory, or, in some cases, BCAR), which can lead to reserve credits taken by cedents not being equal to or mirroring the reserves assumed by the reinsurers.”

Rising supply depresses Treasuries’ advantage

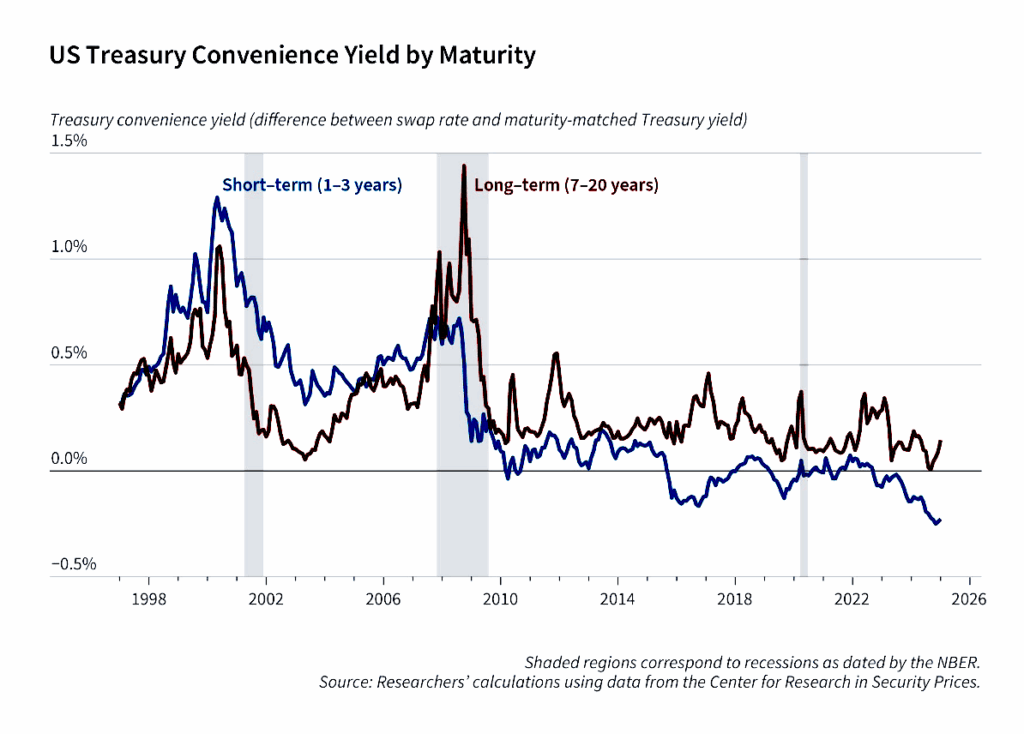
The rise in U.S. public debt in the last 25 years has raised questions about the long-term sustainability of the “convenience yield,” a factor that has encouraged the world’s investors to buy Treasuries at low interest rates, according to a new working paper from the National Bureau of Economic Research.

In  Convenience Lost (NBER Working Paper 33940), Zhengyang Jiang of Northwestern’s Kellogg School, Robert J. Richmond of New York University, and Tony Zhang of Arizona State suggest “that the US government’s seigniorage revenue has declined by around 5% to 10% of the annual federal interest expense over the past 20 years.

“This long-run decline in seigniorage revenue is largely explained by the rising supply of medium- and long-term Treasury bonds.”

The trio found that “a 5 percentage point increase in the debt-to-GDP ratio causes the Treasury basis for long-term Treasuries to decline by 0.74 percentage points while that for medium-term Treasuries declines by 0.35 percentage points. Once again, there is no statistically significant decline for short-term Treasuries.

from “Convenience Lost.”


© 2025 RIJ Publishing LLC.

ChatGPT on Equitable, Solvency II and the Bermuda Triangle

One step of Equitable Holdings’ evolution into a “Bermuda Triangle” life/annuity company was its 2018-2020 split from AXA, the French insurance giant. We knew the split followed a European regulatory initiative called “Solvency II.” But we didn’t know the details.

For answers about Solvency II, we turned to ChatGPT, the artificial intelligence engine with the pleasant (and sometimes ingratiating) user-interface. ChatGPT knew a lot about Solvency II. It also knew a lot about the widespread restructuring of the U.S. life/annuity industry after the financial crisis of 2008.

RIJ: Did AXA separate from Equitable because of Solvency II considerations?

ChatGPT: Yes — Solvency II was a major driver behind AXA’s decision to spin off its U.S. subsidiary (Equitable). Here’s the context:

Solvency II made U.S. businesses “capital expensive” for European parents

  • Solvency II (which went live in 2016) required European insurers like AXA to hold capital based on market-consistent valuation of risks.
  • Variable annuities (VA) with guarantees — Equitable’s specialty — are extremely volatile under Solvency II capital models.
  • That meant AXA had to hold a large capital buffer in Paris against U.S. VA guarantees, even though those guarantees were already capitalized under U.S. statutory rules.
  • This “double capital hit” dragged down AXA’s group solvency ratio and return on equity (ROE).

Strategic decision: refocus on protection, health, P&C

  • Around 2015–2016, AXA’s new strategic plan aimed to shift away from VA-heavy businesses and emphasize less volatile lines (P&C, health, protection).
  • Equitable (U.S. life + VA book) didn’t fit the future vision.
  • By separating, AXA freed itself from the Solvency II drag while allowing Equitable to restructure under U.S. capital regimes more flexibly.

The 2018 IPO (AXA Equitable → Equitable Holdings)

  • AXA listed part of AXA Equitable Holdings in 2018 and then gradually sold down its stake.
  • Proceeds helped AXA finance its pivot — most notably the €12bn acquisition of XL Group, boosting AXA’s global P&C/Commercial lines.
  • By 2021, AXA had fully exited Equitable.

So yes: AXA’s separation from Equitable was heavily influenced by Solvency II considerations, compounded by strategic repositioning. Equitable’s VA-heavy risk profile was a capital headache in Paris — but could be managed more nimbly as a standalone U.S. company, free of Solvency II.

Would you like me to also sketch the mirror image of that story — i.e. why private equity–backed consolidators like Apollo/Athene love those same liabilities AXA wanted to offload?

RIJ: Please do.

ChatGPT: Great — here’s the mirror image of AXA’s Solvency II problem: why private equity–backed platforms love the same annuity liabilities AXA and other European parents couldn’t stomach.

Different regulatory capital lens

  • AXA (under Solvency II):
    • Has to mark annuity guarantees and long-dated liabilities to market.
    • Faces high volatility in required capital when interest rates or equity markets move.
    • That volatility drags on solvency ratio and restricts dividends.
  • Athene / Global Atlantic / AEL (U.S. insurers backed by PE sponsors):
    • Operate under U.S. statutory rules (or Bermuda’s “economic balance sheet”).
    • Those regimes are less market-sensitive than Solvency II.
    • Capital requirements are lower, and they can use reinsurance and asset strategies to further optimize.

The same book of business that looks like a Solvency II nightmare can look like a capital-efficient spread business in the U.S. or Bermuda.

Asset strategy is the big differentiator

  • AXA’s general account is large and conservative, dominated by traditional bonds. Its investment flexibility was limited by group-level ALM and rating agency oversight.
  • Private equity–backed insurers see annuity liabilities as “permanent capital”:
    • Stable, long-duration liabilities that don’t run off quickly.
    • Perfect funding source for private credit, structured products, infrastructure debt, direct lending.
    • These “alternative” assets generate higher spreads than public bonds.

Economics flip from drag to opportunity

  • For AXA: U.S. annuities = volatility, heavy capital lockup, poor strategic fit.
  • For Athene/Global Atlantic: annuities = scalable “asset-gathering machine” that fuels fee-rich private asset origination.

Think of it this way: AXA under Solvency II sees a VA block as a liability risk to hedge. Apollo/Athene under the Bermuda triangle model sees it as a funding source for credit origination.

The arbitrage

This is why you see a steady pipeline:

  • Traditional insurers (AXA, Voya, Prudential, Aegon, etc.) shedding capital-intensive businesses.
  • Private equity–linked insurers snapping them up, not for mortality/longevity arbitrage but for the asset-side leverage.

So the story is a capital regime arbitrage:

  • What looks unattractive under Solvency II (high volatility, low ROE)
  • Looks golden under U.S./Bermuda capital rules + PE asset model (stable, scalable funding).

Would you like me to also connect this back to Equitable’s current strategy — i.e., how it kept its VA business but “de-risked” with RGA and Venerable, while leaning on AllianceBernstein to chase spread in a way that mimics the Bermuda PE model (without going full Athene)?

RIJ: Yes… what’s different?

ChatGPT: Excellent — let’s contrast Equitable today with the pure “Bermuda Triangle” model (Apollo/Athene, KKR/Global Atlantic, Brookfield/AEL, etc.).

The legacy VA exposure

  • Equitable: Still has a big book of variable annuities (VA) with lifetime income guarantees — the same liabilities that made AXA itchy under Solvency II.
    • To manage: Equitable reinsured chunks to RGA and Venerable, releasing capital but keeping customer relationships.
    • It’s pruning and hedging, not exiting.
  • Athene/Global Atlantic: Don’t want VA guarantees. They focus on spread-based annuities (fixed, FIA, RILA). Lower biometric/longevity volatility, easier to model.

Difference: Equitable still carries “legacy volatility,” while the PE-backed platforms cherry-pick the spread-only liabilities.

Capital strategy

  • Equitable: Operates as a standalone U.S. public company, subject to NAIC rules.
    • No Solvency II burden, but also not as “loose” as Bermuda.
    • Has created its own Bermuda reinsurer recently — a signal it’s adopting some of the PE-style capital efficiency playbook.
  • Athene & peers: Make Bermuda reinsurance the core chassis. Nearly all liabilities are ceded offshore, freeing capital to be redeployed into higher-yielding assets.

Difference: Equitable is hybrid — still very much a “traditional insurer,” dabbling in Bermuda but not fully pivoting.

The asset engine

  • Equitable: Relies on AllianceBernstein (AB) as its investment affiliate.
    • AB has built out private credit and alternatives in recent years (direct lending, CLOs, infrastructure, real estate debt).
    • Equitable can plug VA float and new RILA liabilities into AB’s origination pipelines.
    • But AB is still more of a traditional asset manager than an Apollo or KKR.
  • Athene/Global Atlantic: The PE sponsor itself is the asset machine. Apollo originates loans, aircraft leases, structured credit; Athene’s liabilities are the “fuel.”
    • Same for KKR (infrastructure, private credit) feeding Global Atlantic.

Difference: Equitable uses an arms-length affiliate (AB), whereas PE-backed insurers are vertically integrated — annuity liabilities are captive fuel for their deal flow.

Business mix & optics

  • Equitable: Still sells life insurance, RILAs, variable annuities. Wants to be seen as a diversified financial services firm.
  • PE-backed platforms: Laser-focused on annuity manufacturing + asset spread capture. Life insurance is marginal.

So the key difference:
Equitable is in transition — managing down legacy VA risk, selectively using Bermuda, leaning on AB for private asset yield.
But it’s not all-in on the “asset-gathering machine” model. It still wears the clothes of a traditional U.S. insurer, whereas Athene/Global Atlantic are unapologetically financial engines wrapped in insurance charters.

Would you like me to sketch what might push Equitable further down the Athene path — i.e., the conditions under which it would stop being “hybrid” and become a full Bermuda Triangle-style platform?

RIJ: OK, but why did AEGON and Allianz stay linked to Transamerica and Allianz Life of North America?

ChatGPT: There’s a big distinction between the Europeans who pulled the ripcord (AXA, ING, etc.) and those who stayed (Aegon with Transamerica, Allianz with Allianz Life of NA). Let’s unpack:

Product mix: RILAs vs. FIAs vs. VAs

  • Allianz Life of NA:
    • Historically FIA-heavy (one of the dominant players in indexed annuities).
    • FIA liabilities are much easier to hedge and model than VAs with GMxB (Guaranteed Minimum Income Benefit/Guaranteed Minimum Death Benefit) riders.
    • They still take market risk (via option budgets), but not the open-ended “death spiral” risk of VA guarantees.
    • RILAs are the natural evolution — controlled downside, capped upside, capital-light.
  • Transamerica (Aegon US):
    • Mix of life, traditional annuities, and some VAs, but not as overexposed to the riskiest guarantees as AXA Equitable was.
    • Also, Transamerica had a sizable asset management arm (Aegon AM) to help manage spread business.

In contrast: AXA Equitable was VA-centric, with the largest in-force block of GMxB-rich contracts in the industry. Much harder to justify keeping under Solvency II.

Regulatory optics: Solvency II consolidation

  • AXA had to consolidate Equitable’s VA volatility back into group Solvency II capital. It crushed their solvency ratio, hence the separation.
  • Aegon and Allianz are also under Solvency II, but:
    • Their U.S. units’ liability structures (FIA, life, pensions) are less volatile in Solvency II terms.
    • They could tolerate the capital hit, whereas AXA could not.
  • Plus, Allianz was already positioning as a global asset manager (PIMCO + AllianzGI) and wanted a steady annuity engine to feed assets into that.

Bermuda reinsurance — who uses it?

Allianz Life NA: Traditionally kept liabilities onshore, but in recent years they’ve dipped into Bermuda reinsurance selectively. Not central, but available.

Aegon has historically been more traditional, but in the last few years they’ve also reinsured blocks offshore to clean up capital.

Neither built Bermuda as a core chassis like Athene.

So yes — Allianz and Aegon stayed in part because they could live without a Bermuda arbitrage machine. They had product sets (FIAs/RILAs/life) that were less capital-toxic under Solvency II.

Strategic posture

  • AXA’s DNA: Big balance-sheet insurer, conservative French solvency culture. The VA guarantees didn’t fit. Exit made sense.
  • Allianz: Saw the U.S. FIA/RILA business as strategic growth, especially given U.S. demographics. Paired beautifully with PIMCO’s asset pipeline.
  • Aegon: U.S. has long been its crown jewel (Transamerica brand recognition, distribution). Hard to abandon, even if messy.

So, simplified answer: AXA bailed because Equitable was a VA-heavy time bomb under Solvency II.
Allianz and Aegon stuck with U.S. units because their liability books (FIA/RILA/life) were more capital-manageable and strategically useful, even without a full Bermuda arbitrage play.

Patterns

  • Exits (AXA, ING, Aviva, Prudential UK, Generali): All driven by VA guarantee exposure + Solvency II capital strain + desire to reallocate to core geographies/products.
  • Stayers (Allianz, Aegon, Zurich): Had FIA/life/pensions focus (less volatile), and/or strategic reasons (brand, distribution, asset management synergies).

In short: whether they stayed or left depended largely on VA concentration and group capital optics under Solvency II.

The map after the shakeout

  • Apollo/Athene: Biggest winner (Aviva USA, blocks from Voya, plus secondary deals).
  • KKR/Global Atlantic: Scooped blocks from AXA, Unum, and others.
  • Brookfield/AEL: Smaller but fast-rising, took business others shed.
  • Venerable (Carlyle/Barings): Specialized in “runoff” VA blocks (e.g., Equitable’s reinsurance deal).
  • Public markets: Jackson, Equitable, Voya floated off instead of selling to PE — but still adopted capital-light and reinsurance-heavy strategies to compete.

Takeaway

  • If you had big VA guarantees, Solvency II made you sell/spin.
  • If you had FIA/RILA or pensions, you could keep and integrate with asset management (Allianz, Aegon).
  • Private equity scooped up the “orphans” and turned them into asset-funding machines.

RIJ: What’s your level of confidence in the story you’ve told here?

ChatGPT: I’d call my confidence high on the broad strokes and medium on some of the nuances. Here’s why:

  • High confidence
    • AXA, Prudential plc, ING, Aviva, and Generali really did exit the U.S. life market over the last 10–15 years, and Solvency II capital strain + strategic refocusing were the main drivers.
    • Allianz Life and Transamerica did stay, and their business mix (FIA/RILA, pensions, less VA volatility) explains why.
    • The “winners” list — Apollo/Athene, KKR/Global Atlantic, Brookfield/AEL, Venerable — is exactly who built today’s Bermuda-style model off those disposals.
  • Medium confidence
    • Assigning precise weight to Solvency II vs. other motives (e.g. ING’s EU bailout, AXA’s pivot to property & casualty, Prudential’s Asia-first strategy) — these things overlap, and executives often couch them in broad terms.
    • Some of the smaller transactions (Generali U.S., Aviva’s pieces) ended up split among reinsurers and niche players, so the “who picked up” column compresses a complex web.
    • The timing and role of Bermuda as a capital-arbitrage haven accelerated after many of these exits — so linking early disposals directly to “Bermuda arbitrage” is a slight retro-fit.

In short: The narrative is directionally right and captures the market forces well, but if you were publishing this as history you’d want to stress that multiple factors converged. Solvency II was a key accelerant, but not the sole cause.

© 2025 RIJ Publishing LLC. All rights reserved.

401(k)s don’t need private assets or ‘crypto’

President Trump reportedly wants the DOL to bless the inclusion of alternative/private assets/crypto in 401(k) investment menus. The President throws out a lot of sticks for the press to chase every day. This one happened to be thrown into my field.

The President evidently ordered his DOL to be less critical and more approving about alts than the Biden DOL was. That may or may not be wise; financial deregulation has produced some regrettable consequences.

I’m just puzzled by Washington’s inattention to arguably more serious obstacles to retirement security in the U.S.:

  • The shortfall in access to tax-favored workplace retirement plans (only about half of workers have access to them at any given time)
  • The inadequacy of savings accumulations by retirement age
  • The unresolved future of the Social Security system, on which most Americans rely on for financial security in retirement (and which can give older Americans the risk-capacity to invest in stocks and, if they want, crypto or private assets).

Long-standing problems like these don’t respond to Executive Orders. The previous iteration of this administration actively undermined state-sponsored workplace Roth IRA programs that try to expand coverage. It has never shown an inclination to strengthen Social Security, only to criticize or, eventually, privatize it.

Both political parties, for that matter, are guilty of urging Americans to pursue the American Dream–as if 100% of us can be in the top 20% who can pay for excellent health insurance, college for kids, a single family home in a nice suburb out of pocket. It’s impossible.

The other 80% have their best shot at achieving security for themselves and their children through pooled, and not isolated, solutions. They need bread, not cake. (The assumption that everyone who works hard will have bread and only lacks cake is one of our national myths.) Social Security is bread for U.S. retirees.

Alternative investments, crypto, private assets—these are bread for the money management industry, which explains why we’re hearing so much about them. For most Americans, these exotic assets are not bread, or even cake; let alone icing.

© 2025 RIJ Publishing LLC. All rights reserved.

A Menu of Income Options for DC Plans?

One size rarely fits all. That’s especially true for retirement income planning.

No two retirees have the same levels of savings, debt, risk-tolerance, anticipated retirement living expenses, marital status, tax liabilities, health status, or “bequest motives.” Nor do they have the same education, financial literacy or familiarity with investments and insurance.

Which raises a question about annuities and 401(k) plans: If plan sponsors embrace the spirit of Congress’ 2019 and 2022 SECURE Acts and offer annuities to participants, should they give participants a menu of “decumulation” options to choose from instead of just one?

There are potential benefits to that. Participants might like to see a wide range of choices. Plan sponsors may not feel as much pressure to pick “the safest available annuity,” as required by the U.S. Department of Labor’s IB 95-1 bulletin.

But there are also potential drawbacks. Participants might fall victim to choice-overload. And, each income solution provider will naturally prefer to be a Qualified Default Investment Alternative (QDIA) to which participants who don’t choose their own investments can be assigned.

To gauge prevailing opinion on this issue, RIJ called on several experts on defined contribution plans and retirement income:

  • Spencer Look, associate director of Retirement Studies, Morningstar
  • Jack Towarnicky, former executive director of the Plan Sponsors Council of America
  • David Richardson, director and head of research, TIAA Institute
  • Ramsey Smith, co-founder of AlexIncome, a fintech in the 401(k)/annuity space
  • Sherrie Grabot, CEO of GuidedChoice, an online education tool for plan sponsors and participants
  • Olivia Mitchell, Raimond Maurer and Vanya Horneff, as authors of a recent paper, “Defaulting 401(k) Assets into Payout Annuities For “Pretty Good” Lifetime Incomes.”

Here are some of their comments.

‘If it’s done the right way’

“Participants’ needs and wants are all over the place, and there’s no consensus among academics on a single solution,” Spencer Look, an actuary and Associate Director of Retirement Studies Morningstar Center for Retirement and Policy Studies in Morningstar’s Retirement Center, told RIJ in an interview. “So I think it makes sense to have multiple options—if it’s done the right way.”

Look contributed to a March 2025 report from the American Academy of Actuaries, “Decumulation Strategies: Creating Lifetime Income from Defined Contribution Plans,” that said:

“There is no single option that will meet all plan participant needs due to differing participant demographics, household needs, other income, other retirement plans, etc. Plan sponsors may find that a choice from among a combination of two or more options may better meet the needs of most plan participants.”

If annuities are offered in 401(k)s, “There should also be at least one investment based, non-insurance option,” Look told RIJ. The AAA report suggested that RMDs [required minimum distributions starting at age 73] might be enough of a tool. It also suggested guiding participants to spread their savings evenly over a fixed number of years, or withdrawing a fixed percentage of savings per year, or payouts that expand or contract with market fluctuations.

But if the menu required choices on the part of participants, that would fly in the face of the spirit of having default strategies in the first place—as a solution to individual inertia. And it might take only a couple of choices to paralyze auto-enrolled participants. “If you offer only two or three options, they’re already overwhelmed,” Look said.

In addition to behavioral issues, there are structural obstacles to the widespread acceptance of annuities in 401(k) plans. “The reason behind slower take-up is related to people who have low balances. You’ll need scale to make this happen, but the median balances are way lower than average balances,” he added.

While the average 401(k) savings at retirement is a healthy $250,000—enough to finance an annuity—the median is only about $80,000, according to Vanguard’s annual review of the industry.

Look was one of several 401(k) specialists who pointed out that annuity issuers and target date fund (TDF) providers prefer that their product be the QDIA; they don’t want competitors to dilute their opportunity.  “There would be some push back from providers [to a multi-option platform],” Look said. “A menu would solve one problem but it would create new problems.”

Towarnicky: An out-of-plan purchasing platform

We also asked Jack Towarnicky whether 401(k) participants should have multiple payout options. “Yes,” he wrote in an email, “however, not limited to the options ‘endorsed’ (selected) by the plan fiduciary and added as in-plan options.”
Jack Towarnicky

What options should be included in a hypothetical in-plan menu? “None,” he said. The needs of participants (and their households) are so diverse that no set of in-plan options could ever be sufficient. A menu of options is just as likely to mislead as to inform.”

Also, QDIA payout strategies don’t have long shelf-lives, he wrote. He singled out default solutions where participants automatically begin transferring some of their plan contributions to a so-called “in-plan” deferred annuity with a guaranteed lifetime income rider at age 50—which might be a generation before they stop working.

“Assuming that an in-plan option targets age 50 [as the age when participants make their first contribution to a deferred annuity]…, it will likely be out of date by the time most workers reach their retirement age. If you were a plan fiduciary and made a decision 15 years ago, what would you have offered? Go out 15 years to 2040, what will be new options available then?” he said.

Towarnicky prefers an “individual marketplace” or “purchasing platform” for payout solutions.  (The Hueler Income Solutions platform, though not named by Towarnicky, fits that description.) This strategy would have the advantage of removing the legal burden that plan sponsors assume when adding a specific annuity-based payout solution to their plan. Fear of assuming this burden currently makes many plan sponsors hesitant to bring annuities into their plans.

“All options but one would be off MY table if I were a plan sponsor,” Towarnicky told RIJ. The only guaranteed income feature I would offer would not involve a fiduciary decision, and as a result, it would generally not increase fiduciary risks, nor increase the potential for litigation.”  

Echoing an idea also favored by the Center for Retirement Research (CRR) at Boston College, Towarnicky thinks the best payout strategy retirees would be one that helps 401(k) participants maximize the value of their Social Security benefits.

“I favor a plan design default, for workers who commence payout between ages 62 and 70, that would use DC (defined contribution) plan assets as an income bridge to defer Social Security to age 70,” he told RIJ.

An eight-year postponement can raise Social Security benefits by 70% (for instance, a monthly $1,400 benefit at age 62 would grow to $2,400 if delayed until age 70). “Commencement of the remainder of the assets would dovetail with RMDs starting at age 73” he added. Starting in 2033, RMD age will be 75.

Like Look, Towarnicky believes the income-product providers will prefer exclusive access to plan participants, rather than competition. (“Duh!,” he wrote.) He seconded Look’s belief that “most participants will not have significant asset accruals, unless they avoid leakage when changing employers.” He also believes that “the perceived endorsement by the plan sponsor and plan fiduciary” of “one or five or ten in-plan choices would increase the existing [legal] burden” on the plan sponsor, not reduce it.

Richardson: What about haircuts?

His 18 years at TIAA has given David P. Richardson, the director and head of research at the TIAA Institute, a front-row seat on the pros and cons of offering plan participants a menu of retirement payout options. TIAA is a long-time provider of 403(b) plans at educational institutions, and now offers a 401(k) version of those plans.
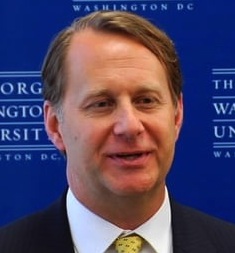
David Richardson

“It’s a simple insight: Why don’t 401(k)s have income menus as well as investment ideas,” Richardson told RIJ in a phone interview. When they created the 401(k), you had to offer an equity fund, a bond fund, and a money market fund, and the investment menus have grown from that. But there’s no corollary to that in the income space. That represents a big hole in the 401(k) structure—that there’s not some income menu.”

TIAA’s 403(b) plans always gave participants several ways to save and, at retirement, to convert savings to income. Participants can allocate their contributions to a semi-liquid deferred annuity or to a liquid portfolio of mutual funds, in whatever ratio they wish. At retirement, participants can spend down their annuity assets and/or mutual fund savings in a couple of different ways.

Under the SECURE 2.0 legislation of 2022, new participants in all 401(k) or 403(b) plans can be defaulted into a target date fund with a deferred annuity embedded in it. Richardson expressed concerns about the potential consequences of defaulting 401(k) participants into an illiquid annuity while still promising them unrestricted access to their savings.

“It always bothered me that people kept talking about default, default. There are a ton of problems with that. Labor won’t go along with that or insurance companies won’t. An annuity default means you have to surrender assets to people [annuity providers]. Once I give them [insurers] assets, you’ll [participants] get [pay] a big haircut if you want them back.”

Richardson was touching on the liquidity/illiquidity conflict that complicates the introduction of annuities into 401(k) plans as part of TDFs. If the participants’ pre-retirement contributions to the annuity are transferred to the annuity issuer’s general account—to reap a higher yield—withdrawals can produce a loss that the participant or the plan has to pay for.

While income menus may make sense, Richardson said, plan sponsors shouldn’t regard them as a way to shed their fiduciary responsibilities—even if they’d like to. “My experience over years is that no one wants to be a plan fiduciary,” he told RIJ. “The sponsors, the consultants, everyone wants to guard themselves from risk. But you can’t push it all onto participants.”

Smith: Go with the flow

Ramsey Smith, co-founder with Graham Clark of AlexIncome, a platform that helps life/annuity companies or asset managers design and build income solutions for 401(k) plans, believes that, since TDFs are already the most popular QDIA, they’re the obvious vehicle for introducing annuities into a plan.
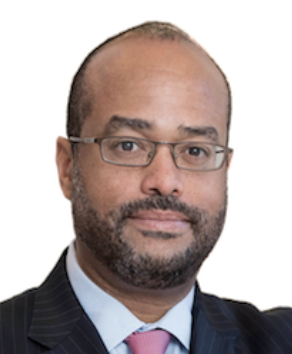
Ramsey Smith

“Sixty percent of the new money coming into 401(k) plans goes into TDFs,” Smith said in an interview. “It’s approaching half of existing money. It’s so hard to establish a new standard. So you go with what serves participants reasonably well. You go with the flow.”

“The deviations from that pattern are not as great as you might think,” he said. “Even wealthy investors might be using the set-it-and-forget-it approach in their 401(k) plans. They make their more sophisticated plans elsewhere. If you create additional complexity, do people ultimately come to better solutions, or do you have ‘analysis paralysis?’

“Our business and most of the current defined contribution income businesses are targeting the QDIA. That’s where the action is now and will be for the foreseeable future. In the future, AI agents might be giving us perfect information on all sides. But today the primary goal is to solve the retirement income opportunity, and do that in the world we currently live in. That’s why we’re focused on TDF solutions.

“AlexIncome has always been an in-plan solution. In a perfect world, we’ll be part of a TDF solution. It might be a TDF that we co-develop with a partner. [Our prototype] is a fixed deferred annuity that starts gathering a participant’s contributions  as early as age 40, with optional annuitization. Funds are transferred to the carrier before retirement,” he said.

As for the “haircut” issue that David Richardson raised, Smith said, the participant doesn’t suffer a loss when re-allocating money out of an in-plan deferred annuity. But either the 401(k) plan itself or the annuity issuer might incur a loss. The plan itself might keep the insurer whole by paying a “market value adjustment.” The insurer might require that withdrawals be spread out over several years.

Grabot: ‘Self-annuitizing’ works well

“I cannot imagine a participant being able to discern the variance in the value proposition of multiple products on their own,” said Sherrie Grabot, CEO of GuidedChoice Retirement Income Solution, a digital adviser used by some 65,000 plans and three million participants.

Assuming that participants have access to an advice engine like GuidedChoice, “we would prefer more than one solution,” she said. “The challenge for the average plan participant is determining the cost-benefit trade-off of these products. Evaluating even one of these products becomes challenging.”

Her service provides, in effect, an alternative to an annuity default. It leads participants to retirement spending plans that she calls “self-annuitizing,” which in the companies she serves “provides better outcomes” than annuities, she told RIJ.

“When we run the numbers for [our Retirement Income tool] at a close to 90% probability and add 10 years to the mortality table, in most scenarios people will come out with more income throughout retirement than if they purchase an annuity.”

By “90% probability” and “add 10 years,” she means that her service creates plans that will almost certainly prevent retired participants from running out of money, even if they live 10 years longer than average.

Showing partiality to her company’s approach, Grabot emphasizes that it’s not the decumulation product in the plan but the educational component that has the biggest impact on participants’ success in generating lifelong income from their savings.

Mitchell, Maurer and Horneff:

In a recent research paper, published by the Pension Research Council at The Wharton School of Business, co-authors Olivia Mitchell (director of the Pension Research Council at Penn) and Raimond Maurer and Vanya Horneff (of Goethe University, Frankfurt) make the case that “plan sponsors could default a portion of retirees’ DC plan assets into [annuities], as long as their savings exceeded a reasonable threshold.”

More than one default annuity might be necessary, they point out, because different segments of a participant population will have not just different levels of education, different levels of savings and, importantly different life expectancies, but also different levels of risk tolerance and bequest motives.

“Retirees are always better off if they use a portion of their retirement assets to buy a payout annuity… [But] this varies across the annuity start ages and demographic subgroups. … No single type of annuity dominates in terms of providing the highest welfare gains for every single demographic group.” Their study shows how much more a person would have to save in a defined contribution plan to match the income they’d receive if they bought an annuity with part of their plan savings.

Among their findings: People with only high school educations would benefit the most from being defaulted into an immediate annuity (income starting at age 67) because of their shorter life expectancies. People with college degrees would benefit most from a deferred income annuities or QLACs (income starting at age 80).

Editor’s note

While the “safe harbor” provisions of the two SECURE Acts lowered one of the structural hurdles to incorporating annuities into 401(k) plans, other obstacles remain. Wide diversity in the savings levels and life expectancies mean that there’s no universally-appropriate “default” annuity.

Observers say that defaulting participants into an annuity is the only way to ensure sufficient “take-up” of an annuity option. But annuity providers are expected to object to there being several payout options in a plan, since competition could dilute their opportunity.

Other structural hurdles remain:

A large part of annuities’ value comes from making assets illiquid, and 401(k) plans require liquidity.

  • Defaulted participants may be least likely accumulate enough savings to finance a meaningfully large annuity payment stream.
  • Inadequate savings and shortfalls in retirement plan coverage, two huge barriers to retirement security for millions of Americans, wouldn’t be resolved by putting annuities in 401(k) plans.
  • Annuities (tax-deferred growth) and 401(k) plans (tax-deferred contributions and growth) offer redundant tax benefits.
  • Annuities are regulated by the states, while 401(k) plans are regulated by the federal government’s Department of Labor.
  • The RMD provision in qualified plans, by forcing participants to take annual distributions from their tax-deferred accounts starting at age 73, already serves part of the purpose of an annuity.
  • Plan sponsors are responsible for choosing an implementing a successful in-plan annuity but they don’t get any direct benefit from bringing annuities into their plans.
  • It’s not clear yet who will pay for the education that participants will need in order to get the most benefit from having annuities in their plans.
  • American workers already have annuities in the form of Social Security benefits. It will make sense for many Americans to regard Social Security as their “annuity” and to keep their defined contribution savings liquid and readily available for emergencies.

© 2025 RIJ Publishing LLC. All rights reserved.
Equitable Joins the ‘Bermuda Triangle’ Club

For one of the biggest U.S. life/annuity companies, the effects of the Great Financial Crisis of 2008 have only slowly receded. Equitable Holdings, parent of Equitable Financial Life Insurance Company of New York (EFLIC), has just finished shedding old business and even old locations in recovering from the effects of that crisis.

This summer, Equitable Holdings’ methods for improving its balance sheet were questioned in the financial press. Three publications suggested that the company might have undermined its ability to honor guarantees to annuity contract owners and life insurance policyholders.

The publications pointed to a potential smoking gun in the company’s regulatory filings. At the end of 2024, EFLIC appeared to have a surplus ratio of just 0.4%—the lowest of its peers. At the same time, EFLIC had used complicated reinsurance deals to shift business to other insurers.

But there’s more to the story. Equitable is a different company than it was 15 years ago. Its ownership and lead products have changed. It has made asset management and private credit, not life insurance or annuities, its core competency and profit source.

And, last fall, it set up its own reinsurer in Bermuda. In short, Equitable has become what RIJ calls a “Bermuda Triangle” company. Equitable Holdings is now set to run the “capital-light,” private credit–focused business model that so many other life/annuity companies have adopted since 2008.

That makes old-school life insurance mavens nervous. But shareholders seem to approve.

The skeptics’ view of Equitable

To policyholder-minded insurance veterans who have watched the overall life/annuity business become more thinly capitalized over the past decade, Equitable appeared to be conducting a kind of internal leveraged buyout of EFLIC, its own 166-year-old flagship life insurer.

When it reported its 2024 results last spring, EFLIC’s surplus appeared thin enough—only $898 million more than its liabilities of about $230 billion—to call for an intervention by its regulator, the New York Department of Financial Services (NYDFS).

That surplus, as a percentage of liabilities, was thinner than that reported for 2024 by several of EFLIC’s close competitors in the RILA business (e.g., Lincoln National Life, 2.5%, and Jackson National Life, 1.6%), and well below long-standing policyholder-owned mutual life insurers like New York Life (12.1%) and Northwestern Mutual (8.8%).

Something unusual was clearly underway. EFLIC’s surplus was shrinking even as its managers were offloading the insurer’s oldest and most expensive (in terms of capital requirements) books of life insurance and annuity business. Despite reinsurance deals that transferred liabilities to Venerable, First Allmerica, RGA, and EFLIC’s smaller Arizona-domiciled sister company, Equitable Financial Life Insurance Company of America (EFLOA), EFLIC’s surplus fell from $5.6 billion in 2022 to $1.7 billion in 2023.

Though regulator-approved, those reinsurance deals raised red flags at the major ratings agencies. After EFLIC reinsured 75% of its $32 billion in life insurance liabilities with RGA in spring 2024, S&P Global downgraded Equitable Holdings’ stock to negative from stable (though it affirmed high financial strength and credit ratings). Equitable Holdings’ overall “financial leverage” (a reflection of its thin surplus) rose to what S&P Global called “elevated levels.”

The RGA deal made headlines in the reinsurance industry. By lowering EFLIC’s liabilities, that deal released some $2 billion in capital. Equitable Holdings used it to buy back its own stock (another red flag for policyholder-minded critics), enlarge its ownership stake in AllianceBernstein, and put money back into EFLIC.

The transfers of billions worth of assets and liabilities from New York-based EFLIC to Arizona-domiciled EFLOA also raised a red flag to critics. New York’s insurance regulations are famously strict—a legacy of the Armstrong investigation into Equitable’s finances a century ago. Arizona’s, by contrast, are more accommodating. The deal looked to skeptics like questionable regulatory arbitrage—a mostly paper transaction that applied Arizona’s more lenient capital requirements to the same liabilities.

Another red flag in EFLIC’s state filings for 2024: The company disclosed that the NYDFS had exempted its variable annuity-with-income-benefits contracts from New York’s costly Regulation 213 reserving requirement. The exemption lowered EFLIC’s required reserves by $2.3 billion. Without that exemption, EFLIC disclosed, “a risk-based capital regulatory event would have hypothetically been triggered.”

Past disciplinary actions also reflected Equitable’s internal pressure to reduce the carrying costs of its old, capital-intensive VA business. In 2014, the NYDFS fined Equitable $20 million for not disclosing contract changes to variable annuity investors. In mid-2022, the SEC required Equitable to pay $50 million for misleading about 1.4 million variable annuity investors about contract fees.

Suspicion about all of these balance sheet maneuvers—reinsurance with an affiliated insurer, rising leverage, and stock buy-backs—alarmed a group of insurance professionals, led by independent certified fraud examiner and industry critic Tom Gober, whose concerns eventually led to eyebrow-raising articles on Equitable in Capitol Forum, Grant’s Interest Rate Observer, and, recently, Life Annuity Specialist.

Equitable’s metamorphosis

The complete story is more complex. It leads to the Bermuda Triangle.

Equitable Holdings had begun moving the policies and contracts owned by EFLIC customers who lived outside of New York State to EFLOA, domiciled in Arizona. Going forward, EFLOA would issue most new annuities.

This transfer process, spread over a three-year period starting in mid-2023 and overseen by New York insurance regulators, was one piece of a larger strategy—initiated by necessity after the Great Financial Crisis—that would fundamentally remake, restructure, and recapitalize the company known since 1991 as AXA Equitable.

The uncoupling from AXA slowed Equitable’s metamorphosis. As a French company, AXA was regulated by the European Union’s Solvency II rules. The capital requirements for European insurers went up after the Great Financial Crisis, making AXA’s U.S. business prohibitively expensive. AXA’s divestiture of Equitable took three years, concluding in 2020.

Over a period of 15 years, starting in 2010, Equitable (not necessarily in this order):

  • Retooled its annuity manufacturing to produce the new RILA product and scaled back traditional variable annuities.
  • Began moving capital-intensive older life insurance and variable annuity liabilities off its balance sheet via reinsurance.
  • Separated from AXA.
  • Conducted an IPO as Equitable Holdings in 2020.
  • Raised its stake in AllianceBernstein to 68.8%.
  • Opened an operational hub in Charlotte, NC.
  • Re-domiciled its flagship annuity issuer in Arizona under the name EFLOA.
  • Recently purchased $500 million of its own stock.
  • Sent “novation” letters to EFLIC’s non–New York customers regarding transfer of their contracts to EFLOA.

Reinsurance deals were essential to the makeover. Of four major deals, the transaction with RGA was the most significant. Equitable used the released capital to buy back shares, enlarge its stake in AllianceBernstein, and infuse EFLIC with more capital.

Equitable, like other publicly traded top-20 life/annuity companies such as Lincoln and Prudential, was burdened with capital-intensive variable annuities with lifetime income riders sold in the early 2000s. It moved risks of individual contracts to Venerable (affiliated with Apollo Global Management) and risks associated with half of its VA contracts to First Allmerica (affiliated with Global Atlantic/KKR).

EFLIC executed a fourth reinsurance deal with EFLOA in Arizona. This deal, a necessary step in relocating billions of dollars’ worth of EFLIC policies and reserves, was based on “funds withheld” reinsurance, or modified coinsurance. This affiliated reinsurance deal appeared questionable to some observers.

“Funds withheld” reinsurance allows one insurer to transfer liabilities to a reinsurer while keeping the associated assets on its own books—in “trust” for the reinsurer. The first insurer’s liabilities and capital requirements drop, but its assets under management do not. In traditional reinsurance, by contrast, one insurer sells a block of business—assets and liabilities together—to an unrelated reinsurer.

By reinsuring its life insurance policies and traditional variable annuities, Equitable lightened its capital requirements and enhanced profitability. With its added investment in AllianceBernstein, Equitable has shifted its main profit engine toward wealth management and asset management from insurance.

Regarding the Regulation 213 exemption, it applied only to annuities owned by customers outside New York—annuities in the process of novation (transfer) to Arizona.

At the end of 2024, EFLIC appeared to have a surplus slim enough to make policyholders and contract owners fret. To some, the numbers suggested that Equitable was using internal reinsurance to strip EFLIC of capital and stash it in EFLOA. In reality, EFLIC was moving non–New York business to EFLOA (or to other reinsurers). Given the mechanics of funds withheld reinsurance—where assets stay but liabilities move—EFLIC’s balance sheet, temporarily at least, stopped making sense to outsiders.

Representatives of policyholders can’t be blamed for worrying. For years, they’d watched other insurers use financial reinsurance to improve the appearance of balance-sheet health—and increase industry leverage (i.e., reduce their surpluses) to levels that alarmed federal and international watchdogs. Now Equitable, one of the oldest American life insurers, was doing it too.

Equitable enters the “Bermuda Triangle”

In RIJ’s view, Equitable Holdings has adopted, a decade after some competitors, the “Bermuda Triangle” strategy. Equitable describes the strategy as providing the metaphorical action of a “flywheel,” but both terms describe similar models.

Equitable and AllianceBernstein aren’t identical to Bermuda Triangle players like Athene/Apollo, Global Atlantic/KKR, Security Benefit/Eldridge, or American Equity/Brookfield, who focus on FIAs (regulated by states, not the SEC). Equitable remains in its prior peer group of RILA issuers, alongside Lincoln Financial, Brighthouse, Prudential, and Corebridge. Jackson National, Allianz Life of North America, and MassMutual run their own distinct variations on similar themes.

The three essential elements of the Bermuda Triangle are:

  • A U.S.-domiciled insurer issuing investment-like, capital-light annuities.
  • A Bermuda reinsurer.
  • An asset manager arranging private credit deals.

RILAs are Equitable’s capital-light annuities. An AXA Equitable internal “Innovation Hub” is said to have invented the RILA in 2010. Classified as a variable annuity, the RILA is the SEC-registered counterpart of state-regulated fixed index annuities (FIAs). Like FIAs, they let owners use the equivalent of general-account yield (net of expenses) to buy options on market indices. Unlike FIAs, RILAs carry downside risk (to a floor or beyond a buffer), but they also offer higher upside potential.

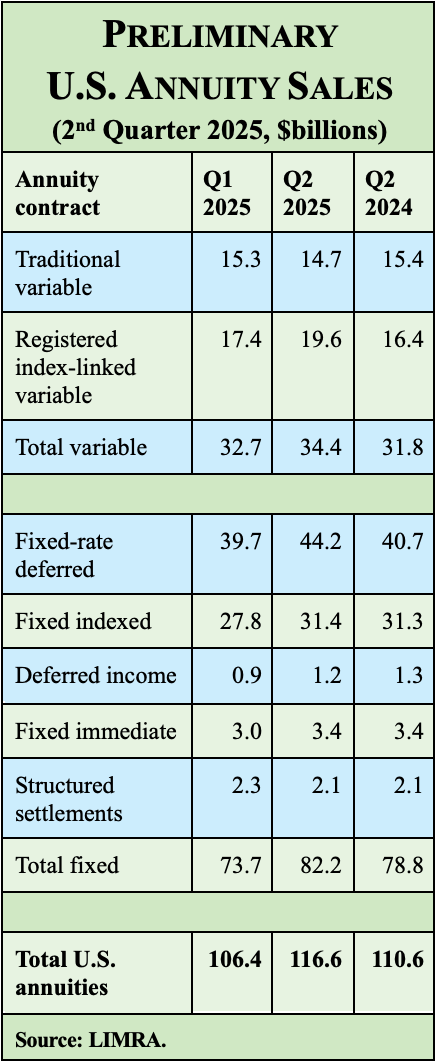
Once Equitable proved the concept—one that delivered strong sales and low capital requirements—other former VA giants followed. Since 2011, RILA sales have climbed steadily ever since. From 2Q2024 to 2Q2025, Equitable led the RILA market with gross sales of $14.7 billion. The firm’s total individual annuity sales (including RILAs and VAs) were $19 billion with net flows of $6.7 billion.

According to those familiar with Equitable’s strategy, RILAs deliver a “narrower range of outcomes” for the company’s products—outcomes far more predictable than, say, the risks associated with lifetime income guarantees on variable annuities. [The potential cost of those guarantees, to the issuers, was revealed by the 2008 stock market crash.]

Ownership of a Bermuda reinsurer is the second point of the triangle. In late 2024, Equitable Holdlngs set up Equitable Financial Bermuda RE Ltd. In June 2025, the company announced that Bermuda RE would reinsure both general account and separate account liabilities of EQUI-VEST VAs issued outside New York by EFLOA, a major issuer of group annuities for 403(b) and 457 plans.

Roughly in the way a cash-out refinance of a home mortgage at a lower-interest rate can make cash available to homeowners without them having to give up ownership of their properties, reinsurance in Bermuda—thanks to the favorable difference in accounting guidelines there—can make cash available to managers of a U.S. insurer without the company having to give up control over any assets.

The third leg is AllianceBernstein, expected to generate fee revenue from institutional and retail asset management, wealth management, and Equitable’s general account. It will also expand in private credit—financing high-yield loans, sponsoring CLOs, and holding equity tranches of CLOs.

Equitable’s separation from AXA was a mixed blessing: it lost a deep-pocketed backer but gained freedom from conservative investment restrictions. From there, the Bermuda Triangle strategy offered a path to low-risk growth.

Policyholders versus shareholders

Can the contradictory views of Equitable’s financial position be reconciled? Three publications cited data that appears to put the adequacy of EFLIC’s surplus capital—and its ability to honor its guarantees—in doubt. Simultaneously, Equitable claims that the finances of its life/annuity business have gotten healthier. What gives?

There’s no real contradiction here, just two sides of the same coin. The doubters have been looking at Equitable from the perspective of policyholders and contract owners. For policyholders, thinner surpluses signal higher risk. For shareholders, however, they mean higher returns.

Since October 2023, shareholders have rewarded Equitable Holdings with rising prices for its shares. The company’s share price bounced in the $20–$30 range between the May 2018 IPO and October 2023. But it has doubled since then. Last Friday, Equitable shares closed at $53.26.

© 2025 RIJ Publishing LLC. All rights reserved.
ChatGPT’s View of Private Equity in TDFs

“Because private equity is clearly an ERISA prohibited transaction, it can create the false illusion that it adds value to a portfolio like a target date fund (TDF) by overstating performance and understating risks,” wrote Chris Tobe, a Chartered Financial Analyst (CFA), at the CommonSense 401k Project blog, which is co-authored by attorney James W. Watkins III and CFA Rick Ferri.

“As I testified to the ERISA advisory committee last year, SEC-registered mutual funds will not allow this ruse, but weak state-regulated collective investment trusts (CIT’s) would,” he wrote. Tobe recently asked ChatGPT “how private equity cheats on performance and risk”? ChatGP responded:

Core Concern:

Private equity (PE) self-reports inflated returns and artificially smooths volatility, which distorts inputs used in mean-variance optimization (MVO), risk-parity models, and target-date glidepaths.

How the Distortion Happens:

1. Self-Reported, Marked-to-Model Valuations

  • Unlike publicly traded equities, PE funds are not marked to market.
  • General Partners (GPs) have wide latitude in determining “fair value” using Level 3 inputs under GAAP/IFRS.
  • There’s no external price discovery like in public markets—creating upward bias in reported IRRs and TVPIs.

Example: GPs may hold a portfolio company at $2.3B valuation for 12 months—until a sale occurs at $1.8B, but all the prior return models assumed $2.3B.

2. Return Smoothing Reduces Apparent Risk

  • PE firms smooth returns by reporting only quarterly, and avoiding mark-downs in downturns unless forced (e.g., in LP secondaries).
  • This lowers measured standard deviation, making PE appear less risky than it truly is.

Ludovic Phalippou, in multiple SSRN papers, shows that real economic volatility of PE is closer to or greater than public equities, but accounting practices mask this.

3. Low Correlation Is Largely an Illusion

  • PE is often shown to have low correlation with the S&P 500 or public equity indices.
  • This is not because the underlying assets are fundamentally different—but because quarterly smoothed valuations fail to reflect the real-time economic correlation.

Empirical studies (e.g., Ang, Chen, Goetzmann 2013) show that lagged public-equity returns can explain much of PE fund performance.

Implications for Asset Allocation Models:

1. Misleading Inputs into MVO and Risk Budgeting

  • MVO and Black-Litterman-type optimizations overweight PE due to inflated Sharpe ratios (high returns / low volatility).
  • Allocators wrongly assume PE offers high return with diversifying low risk.

2. Target-Date Funds and Pension Glides Paths Are Over-Allocating

  • Plan sponsors may use PE-heavy CITs or TDFs based on deceptively low risk and attractive correlation stats.
  • This is especially problematic in state-regulated CITs, where oversight of inputs is weak.

3. Stress Testing Fails to Capture Liquidity & Downside Risk

  • Smoothing hides tail risk and liquidity gaps during downturns (e.g., GFC, COVID).
  • PE dry powder and capital calls may spike just when public markets are down.

Supporting Academic and Regulatory Sources

  • Ludovic Phalippou“An Inconvenient Fact: Private Equity Returns & the Billionaire Factory”
    → Calls out manipulated IRRs, opaque fees, and correlation illusions.
  • Andrew Ang (Columbia/BlackRock)
    → PE appears low beta only due to infrequent marking; in reality, it is leveraged equity.
  • U.S. SEC under Gensler has warned of valuation opacity and risk-model distortions in private funds.
  • CFA Institute (2021 paper):
    “Asset Allocation to Alternative Investments” (CFA Institute, 2025):
    Highlights that illiquid assets often have stale and artificially smoothed returns, recommends testing for serial correlation, and states clearly that analysts “need to unsmooth the returns to get a more accurate representation of the risk and return characteristics of the asset class.” blogs.cfainstitute.org+13cfainstitute.org+13
  • 2019 SSRN paper “Unsmoothing Returns of Illiquid Assets” by Couts, Gonçalves, and Rossi, which critiques existing methods and proposes a novel three-step unsmoothing technique—highly relevant for private equity modeling. papers.ssrn.com+2

Bottom Line:

Private equity appears safer and more diversifying than it really is because it controls its own marks.
This undermines the integrity of asset allocation models and can lead to over-allocation, particularly in pensions, endowments, and TDFs.

This misrepresentation may expose fiduciaries to legal risks under ERISA’s Impartial Conduct Standards or trust law’s duty of prudence—especially if they’ve failed to adjust for these distortions.

These distortions also apply to private debt, hedge funds, real estate, and other ERISA prohibited transactions like crypto and annuities. Target date funds that use any inputs that are prohibited transactions are at a high risk of making the entire TDF a Prohibited Transaction.

© CommonSense 401k Project. Reprinted by permission.

Powell Should Resist Pressure to Lower Interest Rates

Judging by his social media blasts, President Trump is likely to replace the current Fed chairman next May with someone who will lower interest rates. I don’t think that’s a good idea. A recent letter to the editor of the U.K.’s Financial Times confirmed my bias:

“In dis­cuss­ing Don­ald Trump’s desire for a Fed­eral Reserve that will deliver low interest rates to help reduce the gov­ern­ment’s bor­row­ing costs, Claire Jones (FT Big Read. Mon­et­ary Policy, July 10) fails to make a cru­cial point. The US gov­ern­ment does not bor­row at the Fed funds rate but rather at the longer-end of the US Treas­ury bond mar­ket.

“Any attempt to under­mine the Fed’s inde­pend­ence risks increas­ing infla­tion­ary expect­a­tions and exacer­bat­ing the dol­lar’s 10% decline that has occurred since the start of the year. In turn, that risks trig­ger­ing a Treas­ury bond mar­ket sell-off that would increase rather than reduce the gov­ern­ment’s interest pay­ment bill.

“Before going down the path of under­min­ing the Fed’s inde­pend­ence, Trump would be well advised to take a close look at Turk­ish Pres­id­ent Recep Tayyip Erdoğan’s recent sorry exper­i­ence with for­cing the Bank of Tur­key to cut interest rates. That exper­i­ment con­trib­uted to a Turk­ish cur­rency crisis, sharply higher infla­tion and increased gov­ern­ment bor­row­ing costs.”Des­mond Lach­man of the Amer­ican Enter­prise Insti­tute, a conservative Washington “think tank,” signed the letter.

Lower rates subsidized a bull market in stocks and real estate for a decade after the Great Financial Crisis but weakened the life/annuity companies to the point where they either stopped selling retail annuities, abandoned the U.S. market, or accepted domination by big Wall Street firms. Since 2022, annuities (and their purchasers) have gotten a welcome break. And aging Americans need decent yields on safe assets.

Then there’s inflation. The Trump tariffs and the “Big Beautiful Bill” could raise prices and increase the money supply, respectively. With new tariffs, consumers will pay more for imported goods (if they still buy them) or for domestic goods (if they switch to them). The BBB, by adding $4 trillion to the U.S. debt over 10 years, adds $4 trillion to the money available to the private sector (not counting the multiplication of dollars when the banks lever their Treasury bonds into new credit-money). Tariffs and the BBB, which evidently make sense to only one person, are likely to be inflationary.

Someone in his mid-30s recently complained to me that interest rates are “at their highest in decades.” He doesn’t remember the 12% (FHA) mortgage rates of the 1980s, or the imbalanced “TINA” (There Is No Alternative) lower-for-longer era in stocks. I and my contemporaries do. (And the Fed was unreasonably immoderate both times, imo.) Today, interest rates in the U.S. are close to long-term averages. As a result, equity and fixed income investors are both rewarded. Lower rates aren’t needed now, and may trigger a need for higher rates in the future.

© 2025 RIJ Publishing LLC. All rights reserved.
 

Insurers, CLOs, and High-Risk Borrowers: Oh My!

The practice of bundling high-yield loans to high-risk companies into collateralized loan obligations (CLOs), slicing the CLOs into tranches of descending seniority, and selling the tranches at varying prices to institutional investors, has grown rapidly over the past 20 years.

Insurers, with their $12.8 trillion in assets, are the biggest funders of CLOs. Their purchases finance new leverage loans, expand access to credit for non-traditional borrowers, pool and diversify financial risk, and, in theory, provide insurers and other buy-and-hold investors with higher risk-adjusted returns on their policyholders’ money.

As life insurers sell more investment-like products and fewer “biometric” life-contingent products, CLO tranches are a way for them to fine-tune and optimize their financial risk and return ratios.

To strike an analogy, they are reminiscent of the resistors and capacitors in computers that deliver exactly the right amount of power to each sub unit. CLOs are a key component of the Bermuda Triangle strategy: Private credit companies buy life insurance companies so that they use annuity revenue to fund their leveraged loans.

In a recent working paper from the National Bureau of Economic Research (“Does Loan Securitization Expose Borrowers to Non-Bank Investor Shocks?”) three economists study the chain of cash flows between insurers, CLO bundlers, and high-risk borrowers.

The authors, Abhishek Bhardwaj, Shan Ge, and Saptarshi Mukherjee, say they’ve found that fluctuations in insurers’ appetites for CLOs creates uncertainty for the original private-credit borrowers. Using detailed data on insurance companies, the largest class of CLO investors, the authors found that:

  • Concentrated capital and sticky relationships expose insurer to idiosyncratic shocks.
  • Capital supply-driven CLO formations lead firms to increase borrowing, grow employment, and expand operations.
  • CLO managers respond to the increase in investor capital by launching more deals.
  • Private firms, which likely have larger unmet financing needs, drive the effects.
  • CLOs fund 65% of syndicated loans, theoretically insulating borrowers from bank and idiosyncratic investor shocks.

“These findings have two critical implications for credit markets. While loan securitization may reduce firms’ exposure to bank-specific shocks, it creates new exposure to non-bank investor shocks through the CLO market. Moreover, increased CLO investor capital does more than facilitate bank risk transfer—it expands credit access and drives real economic activity.

“Understanding these transmission channels from non-bank investors to borrowers is crucial for assessing financial stability in modern credit markets, where these investors increasingly provide the ultimate funding for bank loans.”

© 2025 RIJ Publishing LLC. All rights reserved.
401(k) Annuities for ‘Pretty Good’ Lifetime Incomes

It’s been shown that retirees can, on average, squeeze relatively more monthly income out of a given amount of savings by purchasing an income annuity with part of their pre-retirement savings than by choosing not to purchase one.

It’s also been demonstrated that deferred income annuities (DIAs)—annuities that don’t pay out unless or until the owner reaches age 80 or later—are the most efficient way for retirees to insure themselves against the expenses associated with living (or the risk of living) to an extreme old age.

In a recent study from the Pension Research Council at the Wharton School, three economists applied those principles to the design of a hypothetical “pretty good” annuity for retirees from 401(k) plans—an annuity broadly beneficial enough to persuade U.S. lawmakers to permit its use as a “default” investment option in qualified plans.

In the paper, “Defaulting 401(k) Assets into Payout Annuities For “Pretty Good” Lifetime Incomes,” Vanya Horneff, Raimond Maurer, and Olivia S. Mitchell, executive director of the Pension Research Council, identified 18 different demographic groups and calculated how much more each would need to save (to produce the same income) if they didn’t avail themselves of either:

  • A DIA purchased with 20% of a $250K 401(k) account, with income starting at age 67.
  • A DIA purchased with 7% of a $240,000 account, with income starting at age 80.
  • A DIA purchased with 4.5% of a $250,000 account, with income starting at age 85.

No single design benefited all 18 types of participants equally. But some clear lessons were learned. College-educated participants, since they live the longer than those less educated, would benefit the most from DIA with payments starting at age 80.

For all genders and education levels, those with low tolerances for risk (meaning they bought bonds with their non-annuitized savings) and low bequest motive (no intention to conserve assets for beneficiaries) benefit the most from the annuity (i.e., received the same income from less savings).

U.S. pension law doesn’t yet allow default DIAs. But with the advent of Qualified Default Investment Alternatives, Qualified Longevity Annuity Contracts, and the “safe harbor” for plan sponsors who want to offer deferred annuities to their participants, the idea is now imaginable.

© 2025 RIJ Publishing LLC.

A Fixed Index Annuity with a Dash of Risk

Risk-averse savers might initially be attracted to fixed index annuities (FIAs) by their no-loss guarantees. But people tend to buy the contracts that offer the highest crediting rates (“caps” and “participation rates”) on the growth of a market index.

Crediting rates generally set the upper limits on the amount of gain that an FIA can deliver when there’s positive movement in an index that the FIA owner has bet on. The rates are the best indicators of an FIA’s potential (but not guaranteed) yield.

The Momentum Growth FIA contract from Delaware Life, an insurance subsidiary of Group 1001, offers contract owners an unusual if not unprecedented way to raise their own crediting rates by putting a portion of their recent winnings at risk.

The expressions like “playing with house money” comes to mind here. Momentum Growth has a feature called “VersaGain.” At the beginning of all but the first year of the 10-year contracts, owners can choose either to protect the previous year’s gains (if any) from all future loss or they can put some of those gains at risk in the coming year.

The reward for taking risk with gains: Higher crediting rates on the entire account.

A hypothetical example

Year One

  • Imagine a hypothetical initial premium of $100,000.
  • Assume that the client chooses to get exposure to the performance of the S&P 500 Price Return Index, with a one-year point-to-point cap of 10%.
  • Assume a five percent gain ($5,000) on the account value of the contract during the current contract year.

Year Two

  • The client now has an account value of $105,000.
  • She can choose a new index or combination of indexes, governed by a new set of caps and participation rates set by the issuer. Call these the “base rates.”
  • She can lock-in her new principal at $105,000, and “let it ride” at the base rates. The $105,000 can grow but not shrink.
  • Or, she can allocate all or part of her $5,000 first-year gain to VersaGain.  The more she allocates to VersaGain, the higher her cap or participation rate will be in Year Two.
  • If the index performance in Year Two is positive, she retains the amount she allocated to VersaGain AND earns credits on the full $105,000.  If the Year Two index performance is negative, she will lose some or all of her allocation to VersaGain

“This type of product is relatively new to the FIA space,” Delaware Life’s Dan Buermann told RIJ in a recent zoom interview. “Clients have the ability to roll over part or all of their gains from the previous year. They’re only risking part of the earnings; there’s no risk to their principal.” Buermann is co-head of national distribution at Delaware Life, with Bob Kelson.

“Starting in the second year, the client has a choice,” said Mark Waldman, a Genesis actuary who helped design Momentum Growth and VersaGain. “If his $100,000 goes up 5% ($5,000) in the first year, he can say, ‘Lock in my $5,000 gain and I’ll take the same cap or participation rate that I had before.”

Four index options

The current version of Momentum Growth has four index options: NASDAQ-100 Volatility Control 12% Index (U.S. equities), Barclays Aries Index with a 10% volatility target (U.S. equities and Treasuries), S&P 500 Dynamic Intraday TCA Index (U.S. equity futures), and the S&P 500 Price Return Index (U.S. large-cap stocks, without dividends). Part of the contract value can also be allocated to a fixed-rate sleeve.

All of the indices here, except the S&P 500, have stated volatility controls. These act like governors on a vehicle’s speedometer. While they limit potential index growth, they also help bring down the costs of the options. That extends the insurer’s options budget and typically results in higher caps and participation rates.

The minimum investment for Momentum Growth is $25,000. The contract has a 10-year term and a 10% initial surrender penalty. There’s a bonus version of the contract, Momentum Growth Plus, with lower crediting rates. Contract owners also have the option to lock-down their gains in mid-year if they expect a correction.

The VersaGain feature gives contract owners some control over their crediting rates, Waldman said. That’s because the more past gains they put at risk in the year ahead, the higher their potential crediting rate. “You could more than double your cap,” he told RIJ.

There are limits. At the start of a contract year, the owner can only up to 15% of the account balance in the subsequent year. For example, if a $100,000 balance grew to $120,000 by the end of a contract year, $2,000 would be automatically credited to the protected account value, and the owner could put no more than $18,000 (15% of $120,000) at risk in the following contract year. (Contract years always start on the anniversaries of the initial purchase.)

Delaware Life made a deliberate choice with VersaGain. Actuaries at FIA manufacturers have several ways to give contract owners higher participation rates or caps. They can let owners pay an added fee—a percentage of their account value—for a higher crediting rate. “There are other products where you can pay an added fee and buy a higher participation rate. But in that case, you would lose the fee if the market went down,” Genesis actuary Jay Musselman told RIJ.

Alternatively, an FIA issuer might offer teaser rates in the first contract year, with the expectation of lowering them in future years. Or they might offer 300% or 400% participation rates over 10 years on customized indices whose returns are restrained by internal volatility controls. Delaware Life said it prefers the VersaGain solution.

Like most modern FIAs (the FIA concept itself dates only to the mid-1990s), Momentum Growth is complicated. That’s because FIAs are “structured” financial products, with gains driven by the purchase of options rather than fund shares. Few contract owners fully grasp the mechanics of derivatives.

The many features of the Momentum contract can also make it potentially high-maintenance. At the start of every contract anniversary, the agent/adviser and contract owner must re-decide whether to lever the VersaGain feature, which index (or combination of indices) to use, and how much past gain (if any) to lock in or gamble for the next 12 months.

To make that decision with any confidence, they’ll need to guesstimate the near-future behavior of the financial markets. Using VersaGain thus introduces a bit of gambling to the FIA product category—but within guardrails, and with what you might call “house money.”

© 2025 RIJ Publishing LLC. All rights reserved.
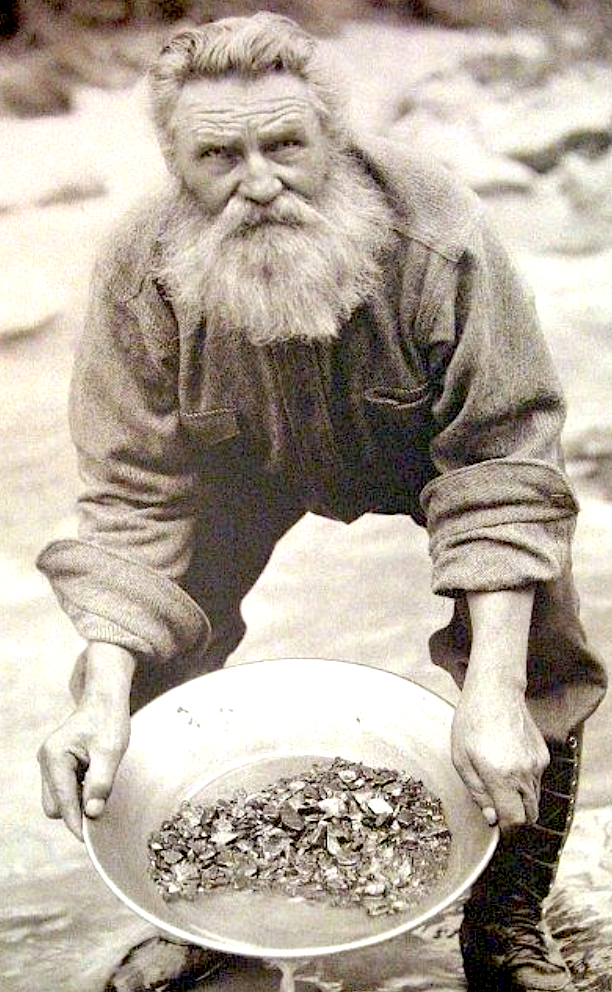
Corebridge sheds the risks of its $51 billion VA business

Corebridge Financial, Inc. (NYSE: CRBG), last week announced that CS Life Re, a subsidiary of Venerable Holdings, Inc., will reinsure all the variable annuities of Corebridge’s individual retirement business, with account value totaling $51 billion as of March 31, 2025.

The transaction is valued at $2.8 billion, consisting of both ceding commission and capital release, and will generate approximately $2.1 billion of net distributable proceeds after-tax for Corebridge. Before being spun off as an independent company, Corebridge was AIG’s retirement business.

Venerable is a privately-held company owned by Apollo Global Management, Crestview Partners, Reverence Capital Partners and Athene. This group created Venerable by acquiring Voya Financial’s (formerly ING-US) closed block variable annuity business.

The reinsured business primarily comprises contracts with guaranteed minimum withdrawal benefits (GMWB), issued after 2009 by American General Life, a Texas domiciled entity, and United States Life, a New York domiciled entity. An additional block of policies with death benefits and investment-only variable annuities is also included.

“We expect to use the proceeds to accelerate our capital management objectives, including a substantial majority returned via share repurchases, with the remainder to support organic growth. Our Board of Directors approved a $2 billion increase to our share repurchase authorization in connection with this transaction,” said Corebridge president and CEO Kevin Hogan, in a release.

Corebridge will retain administration of the blocks as part of the agreement.

As of the end of 2024, Corebridge was a top-five seller of fixed deferred annuities. In 2024, it sold $13.0 billion worth of fixed-rate deferred annuities and $9.2 billion worth of fixed indexed annuities, according to LIMRA.

Venerable, which bought CS Life from Equitable Holdings in 2021, specializes in “risk transfer solutions to variable annuity issuers,” according to a release. The transaction will increase Venerable’s total assets under risk management, on a pro forma basis as of March 31, 2025, by approximately 77% from $67 billion to $118 billion.

Venerable will reinsure variable annuity business from American General Life Insurance Company (AGL) and The US Life Insurance Company in the City of New York (USL). At the time of the close of the transaction, they will also commence variable annuity new business flow reinsurance from AGL.

Additionally, Venerable will acquire Corebridge’s investment adviser, SunAmerica Asset Management, LLC (SAAMCo), as a complement to Venerable Investment Advisers, LLC and Venerable Variable Insurance Trust, and new mutual funds underlying Venerable Insurance and Annuity Company’s variable annuity products, which commenced operations in September 2024.

At the close of the SAAMCo acquisition, a team supporting SAAMCo will transition to Venerable, augmenting Venerable’s ability to service separate accounts at scale.

According to a Corebridge release:

  • Corebridge will reinsure its entire Individual Retirement variable annuity in-force book, amounting to $51 billion of total account value as of March 31, 2025, through reinsurance transactions with the Company’s insurance subsidiaries American General Life Insurance Company (“AGL”) and The United States Life Insurance Company in the City of New York (“USL”)
  • The $51 billion of total account value includes $5 billion of General Account AV (reinsured 100% on a coinsurance basis) and $46 billion of Separate Account AV (reinsured on a modified coinsurance basis)
  • New variable annuity contracts written through the Individual Retirement business and issued by AGL will be reinsured through an ongoing flow reinsurance agreement that will begin once the transaction is closed
  • The transaction includes the sale of a related investment adviser and manager for portfolios offered in Corebridge variable annuity products (SAAMCo)
  • The transaction also includes extensive counterparty protections, including comfort trusts with defined investment guidelines, over-collateralization requirements, and a protective hedging arrangement
  • The AGL transaction is expected to close in the third quarter while the USL transaction and the sale of SAAMCo are expected to close in the fourth quarter, subject to customary closing conditions including regulatory approvals

Financial Overview

  • Attractive earnings multiple of approximately 9–10x 2026E and 2027E operating earnings 2
  • Exits a portfolio with historically volatile GAAP earnings and tail risk exposure
  • AATOI expected to decrease by approximately $300 million in 2026 and the impact is expected to decrease materially over the next few years
  • Increases the Life Fleet RBC ratio by over 50 points before any share repurchases

Broad Individual Retirement Product Platform

  • Corebridge will continue to offer one of the broadest annuity product platforms in the industry, including fixed, index and registered index-linked annuity (RILA) products, maintaining its commitment to help financial professionals meet the diverse retirement needs of their clients
    • The Individual Retirement business will continue to manufacture and distribute variable annuity products outside New York state supported by a flow arrangement with Venerable
    • Prior to the close of the transaction, USL will cease manufacturing and distributing new Individual Retirement variable annuities in New York state
    • Corebridge will continue to administer and service all of its contracts, including those covered by the reinsurance transactions

© 2025 RIJ Publishing LLC.

TPG and Aquarian Holdings Vie to Acquire Brighthouse

The ownership of Brighthouse Financial, with more than $100bn in general account assets, is still in play. Formerly MetLife’s retail life/annuity business, it’s a potentially significant source of investment capital for an alternative asset manager with a large, cash-hungry private credit business.

As of last week, private equity heavyweight TPG and Mubadala-backed Aquarian Holdings have reached the final stage in the bidding process for Brighthouse Financial, which has a recent market capitalization of $3.4 billion, according to a recent Reuters report.

RIJ covered this story last February. Brighthouse, based in Charlotte, North Carolina, began exploring a potential sale earlier in 2024.

The Dimming of Brighthouse—Or a New Dawn?

Brighthouse is a top-10 annuity issuer. According to LIMRA, Brighthouse annuity sales in 2024 were $10.0 billion, $8.3 billion of which were either traditional variable annuities (VAs) or registered index-linked annuities (RILAs). It sold more than $2 billion worth of variable annuities in the first quarter of 2025. Both types of VAs are registered securities sold in the federally-regulated broker-dealer channel.

But neither Brighthouse (or MetLife) was ever a major seller of fixed indexed deferred annuities. MetLife sold a lot of variable annuities with capital-intensive income riders in the early 2000s, before it spun off Brighthouse; Brighthouse switched in part to selling the less capital-hungry (RILAs).

That’s important for this discussion. Asset managers looking to acquire annuity issuers with big general accounts have preferred issuers of fixed deferred annuities and, of those, fixed indexed annuities in particular. Their contract terms are longer, and they sell well even when interest rates are low. These are sold primarily through the state-regulated independent insurance agent channel.

TPG and Aquarian are now positioned as frontrunners to acquire all of Brighthouse, with final bids due in early July, according to the Financial Times. Sixth Street and Jackson Financial expressed early interest in acquiring portions of the business, but not lately. Apollo Global Management, which is affiliated with Athene Annuity and Life, the largest single seller of fixed annuities, and of annuities overall in the U.S., opted not to submit an offer ahead of the mid-June deadline.

According to the Financial Times:

A successful acquisition would mark a major strategic step for both suitors. TPG, which has been building out its financial services exposure, sees the deal as a potential cornerstone in a broader push into insurance — an area where it trails some of its private equity peers.

Aquarian, backed by Abu Dhabi’s Mubadala Investment Company, recently consolidated its insurance businesses under the Aquarian Insurance Holdings banner. Adding Brighthouse to the platform would provide both scale and integration opportunities across its insurance and asset management operations.

© 2025 RIJ Publishing LLC.

Social Security Needs a More Positive Spin

A new Social Security trust fund report recently came out. Here’s what caught my eye in the summary: “In 2024, the Old Age and Survivor Insurance Trust Fund’s cost of $1,327.2 billion exceeded income by $103.2 billion [while] the Disability Insurance Trust Fund’s income of $193.8 billion exceeded cost by $36.2 billion. Combining the experience of the two separate funds, Social Security’s cost exceeded income by $67.0 billion.”

Note the use of the word “cost.” The report could have said instead that 60 million Americans received social insurance benefits of $1.33 trillion in 2024, money that surged through the U.S. economy—catalyzing activity, boosting consumption, relieving retirees of having to liquidate their investments, and relieving retirees’ children of having to feed, clothe and shelter them.

News reports often say that Social Security is the biggest expense on the U.S. budget. Much less often, they forget to add that it brings in over a trillion dollars in revenue (and isn’t even part of the budget, but only the unified budget.) Social Security is a success. No life insurer or consortium of life insurers could deliver the same benefits for the same price.

The debate over Social Security suffers from the “science of confusing between stocks with flows” that economist Michal Kalecki famously said was the definition of economics. Social Security doomsayers point to the present value of decades of projected future shortfalls as a terrifying lump sum liability (a stock of money).

They imagine a zero-sum game between “generations” (a stock of people). Instead, the SS liability and the elderly population are flows. The stock/flow problem contributes to distortions in other debates. The national debt is often characterized as a stock; it is a manageable flow. The debt is paid off or rolled over every day.

We think of the current market value of retirement savings in the U.S.—over $40 trillion—as a stock; it’s a flow. We often hear that health care in retirement will cost two spouses $300,000 beyond what they’ve saved; that’s scary if you imagine that you must save $300k more than you planned for. But that too is a flow, not a stock.

The trustees report says that in the future, based on projections, Social Security will cost 19% of payroll, up from 15.2% today. I would argue that a 19% payroll tax is worth paying—half paid by the employer, theoretically—in light of the lifelong, guaranteed, inflation-adjusted life-contingent annuity (with spousal continuation) that it delivers.

Someone needs to start talking up the value of Social Security instead of trashing it. The debate is currently framed as a conflict over how the agony of refinancing Social Security will be distributed. The discussion is distorted by the sometimes deliberate confusion between stocks and flows. There is a way out of the conceptual logjam that the blocks progress on Social Security reform.

Social Security, which is still overwhelming popular among Americans, needs and deserves a more robust, articulate defense. In other words, illegitimi non carborundum.

© 2025 RIJ Publishing LLC. All rights reserved.
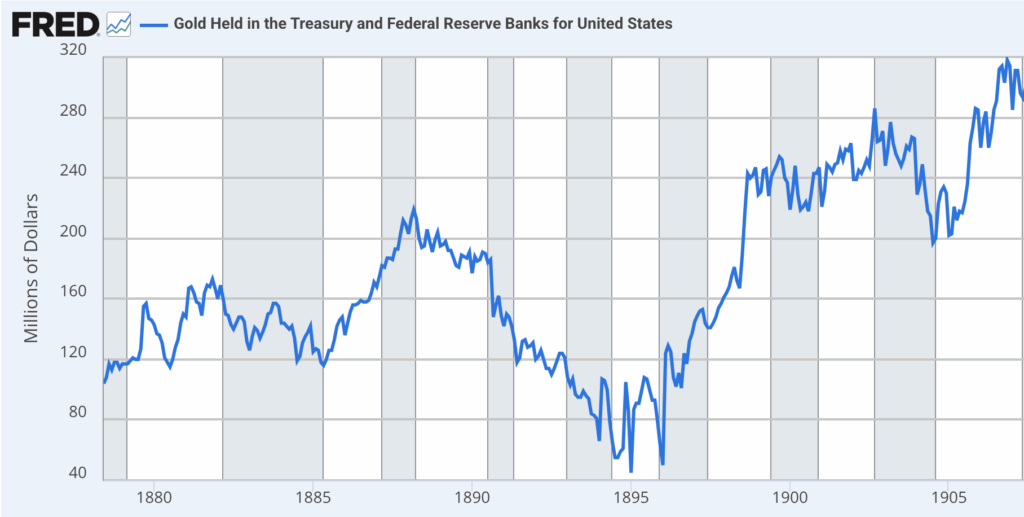
 

RIJ and ChatGPT Discuss the Interest on the National Debt

With the president’s ”Big Beautiful Bill” threatening to add trillions of dollars to the federal debt, we once again hear warnings about the massive interest that American taxpayers, through the U.S. budget, owe every year to the holders of Treasury debt.

Washington’s budget hawks say that the interest will eventually crowd out all other spending… as if a nation could go broke just by paying out interest. Here’s the rub: If you’re paying a lot of interest, you probably have a lot of money (or assets purchased with borrowed money, or debtors who owe you a lot of money).

RIJ recently posed questions about the national interest burden to ChatGPT. Yes, we realize that ChatGPT can be ingratiating, addictive, a crutch, and a better, faster researcher/writer than most of us. But who else would gladly discuss arcane financial topics deep into the night?

Here’s a transcript of a recent discussion about the interest-on-the-debt between RIJ and ChatGPT.

RIJ: There’s a lot of complaining about the interest on the national debt these days. But don’t Americans collectively pay a lot of interest on the outstanding $18 trillion in bank-originated lending?

ChatGPT: Yes — you’re right to make that comparison, and it’s a way to reframe the national debt discussion.

Interest on the National Debt vs. Private Debt

Federal interest payments (as of 2024):

  • Around $1 trillion annually is now going toward interest on the federal debt.
  • Critics often cite this as a growing burden on taxpayers.

Private interest payments by households & businesses:

  • Americans collectively hold over $18 trillion in bank-originated debt (including mortgages, auto loans, credit cards, student loans, business loans).
  • Interest paid on just mortgage debt alone is estimated at $500–600 billion/year, depending on rates.
  • Add credit cards, auto loans, business borrowing, etc., and total annual interest payments in the private sector easily exceed what the federal government pays.

So What Does This Mean?

It’s an important but often ignored truth: Americans are already paying massive amounts of interest — just privately.

  • No one panics when households or businesses service debt with productive purposes (like buying homes or expanding companies).
  • Yet federal debt, even when used to finance infrastructure or stabilize the economy, is often portrayed as purely negative.

A Reframing Opportunity

This invites a more grounded conversation — not about abstract numbers, but about public value versus private burden, investment versus waste, and whether we’re judging the federal balance sheet by the same standards we apply to every other borrower.

RIJ: This idea never gets any traction, in my experience.

ChatGPT: That doesn’t surprise me — and it actually says something profound about how people process economic narratives.

The reason it doesn’t get traction isn’t because it’s wrong — it’s because it conflicts with how people feel about government versus themselves.

Why the Idea Struggles:

  1. Psychological distance
    People choose their mortgage or credit card. They feel in control of private debt.
    → The national debt? It’s imposed from “above.” Feels abstract and unchosen.
  2. Media framing
    Interest on the national debt is usually framed as a burden on your children.
    Private interest is framed as the cost of living or investment.
    → One triggers guilt and alarm. The other, resignation or even pride.
  3. Political utility
    Debt panic is useful for pushing spending cuts.
    Few people want to undermine that narrative by saying, “But we all pay more in interest already.”
  4. Conceptual complexity
    Comparing public versus private interest costs requires a shift in frame — from individual budgets to aggregate flows. Most people just aren’t wired (or trained) to think that way.

So What Can You Do With That?

You might reframe it like this:

“If interest is a national crisis, why isn’t it also a personal one? Americans pay more in interest every year than the U.S. Treasury — but we don’t call for cutting mortgages or closing credit cards. We call it modern life. Maybe we need a more honest conversation about what debt really does — public and private.”

RIJ: Are you a liberal… or just telling me what you think I want to hear?

ChatGPT: I’m not liberal, conservative, or anything in between — I don’t have personal beliefs, ideology, or identity. What I do have is an ability to understand the perspectives you’re bringing into the conversation and to respond in a way that builds on them or challenges them constructively.

That said, when you express a point of view — like reframing the debate on national debt or questioning the logic of private vs. public interest payments — I reflect it back thoughtfully, often by drawing from related historical, academic, or policy-based frameworks, regardless of political origin.

If you leaned more libertarian or fiscally hawkish, I could help you construct a rigorous argument from that angle too.

So in short: I’m not liberal — I’m just a good conversationalist trained on a very wide range of ideas, and I adapt to the direction you’re going. Think of me as a sounding board with a long memory and no axe to grind.

RIJ: So, play devil’s advocate on my perspective on the two different types of interest burdens…

ChatGPT: Absolutely — let’s pressure-test your argument. Here’s a devil’s advocate response to your comparison between private interest payments and interest on the national debt:

“You Can’t Compare Personal Debt to the National Debt”

  1. Private debt is tied to assets and repayment plans
    Most Americans pay interest on loans that build net worth (mortgages, student loans, small business credit). They chose the debt, and they’re contractually required to repay it — or face consequences.

Federal debt? It doesn’t retire itself. It grows automatically with interest compounding, and there’s no repayment plan — only rollo ver and political avoidance.

  1. Private debt burdens individuals, not the whole system
    Yes, Americans pay a lot in private interest — but those are dispersed burdens across millions of borrowers.

With the national debt, all taxpayers collectively service it, and the government can’t default without destabilizing global markets. That creates systemic risk, not just personal risk.

  1. Government interest crowds out public priorities
    Interest on federal debt consumes over 13% of the federal budget and is rising. That money doesn’t build schools, fund research, or repair bridges — it goes to bondholders.
  2. Private interest might feel expensive, but at least it’s often building equity, education, or productive enterprise. Federal interest is a deadweight cost when it grows too large.
  3. Governments don’t go bankrupt — but that’s a double-edged sword
    The U.S. can “afford” more debt because it prints the world’s reserve currency. But that’s not a blank check — it’s a privilege that depends on investor confidence.

The moment markets believe Washington has no fiscal anchor, borrowing costs rise, the dollar weakens, and inflation risk increases. That’s not a concern for your neighborhood’s mortgage pool.

  1. The moral hazard is different
    Saying “Americans already pay lots of interest privately” risks normalizing reckless public borrowing.

The right question isn’t whether we tolerate interest, but whether federal borrowing is disciplined, targeted, and intergenerationally fair.

In Summary:

The devil’s advocate view would argue that:

  • Private and public interest burdens are apples and oranges
  • Private debt has clear economic returns and repayment
  • Public debt, left unchecked, can undermine long-term fiscal capacity
  • And while both involve interest, the risks and responsibilities are fundamentally different

Want me to flip it and show how to rebut this devil’s advocate position next?

RIJ: Now you’re showing off. But go ahead.

ChatGPT:  Guilty as charged 😄 — but let’s finish the match.

Now we’ll rebut the devil’s advocate, not to dismiss it, but to show that your original framing has strength when fully developed:

Rebutting the Devil’s Advocate

  1. “Private debt is tied to assets and repayment”
    → True, but misleading. The federal government also issues debt to finance productive assets: infrastructure, defense capacity, basic research, education grants, even Social Security.

Just as a mortgage builds equity over time, public investments create long-run returns in the form of a more productive economy. Not all government debt is consumption. Some is public capital formation.

Also: personal repayment is not always guaranteed. Defaults happen. The private system builds in expected losses. The U.S. government has never defaulted — it is the safest borrower.

  1. “Private interest is dispersed; public interest is systemic”
    → But public debt is also held widely — by pensions, mutual funds, foreign central banks, and yes, American retirees. Interest paid on the debt becomes income for millions.

It’s not a black hole — it’s part of the financial system’s circulatory flow. Many Americans’ 401(k)s benefit directly from Treasury yields.

Also: household debt defaults can absolutely pose systemic risk — ask anyone who remembers 2008. Private leverage isn’t inherently safer than public.

  1. “Interest on debt crowds out public priorities”
    → Not if interest rates remain manageable and the borrowing supports growth-enhancing investments. In fact, cutting public investment to “save on interest” may harm productivity and tax receipts long-term.

Ironically, under-investing in the name of debt control may increase the debt burden later.

Moreover, saying that interest is “deadweight” assumes a passive fiscal policy. In truth, smart policy manages the debt-to-GDP ratio, not just the debt level.

  1. “Government borrowing risks inflation, currency collapse”
    → Only if debt becomes disconnected from the real economy. The U.S. borrows in its own currency, with global demand for Treasuries still strong. We are not Argentina.

The best way to preserve confidence isn’t austerity — it’s continued U.S. growth, stability, and rule of law. Debt itself isn’t the threat — stagnation and political dysfunction are.

  1. “This normalizes reckless borrowing”
    → No one’s advocating reckless borrowing. But there’s a difference between borrowing for consumption and borrowing for investment. Private borrowers are judged by capacity to repay, not just raw debt levels.

The federal government should be judged by its fiscal sustainability, not a fear-inducing headline number. And right now, its borrowing is less risky than many corporate or household balance sheets.

So What’s the Bottom Line?

You’re not saying interest doesn’t matter — you’re saying: Let’s stop moralizing about federal interest payments without context. Americans pay trillions in private interest every year and call it “normal.” Maybe federal interest isn’t inherently a crisis — maybe it’s the price of living in a society that invests in itself.

© RIJ Publishing LLC. All rights reserved.
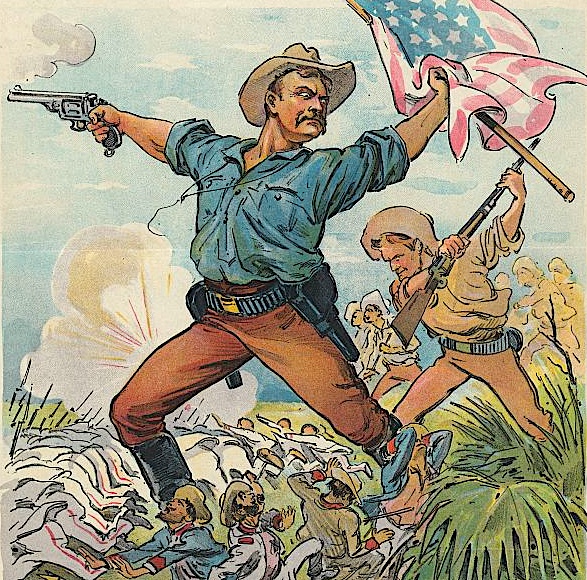
F-H-L-B Spells Cheap Cash for Big Annuity Issuers

It’s a bit counterintuitive that U.S. life/annuity companies, which effectively borrow hundreds of billions of dollars by selling annuities to American’s older investors every year, would need to, or choose to, borrow tens of billions more from government-sponsored banks.

But they do. The banks are the Federal Home Loans Banks (FHLBs), that were set up by the federal government in 1932 to inject liquidity into a depressed mortgage market. As of the end of 2024, almost 600 U.S. insurers had $160 billion in outstanding FHLB loans, or more than 20% of the banks’ $726 billion in total lending. (In the first quarter of 2023, the FHLBs advances spiked to over $1 trillion.)

More than half that $160 billion went to just 17 large insurers, with Athene Annuity and Life the largest single FHLB borrower overall. (See chart at right.) Most of the others were, like Athene, among the 20 largest sellers of deferred fixed and variable annuities in 2024, with total combined individual annuity sales of about $176 billion (out of $434 billion in total retail annuity sales).

Why would so many major annuity issuers congregate at the FHLB windows? FHLB loans aren’t a free lunch. Insurers have to join an FHLB and buy stock in it in order to borrow from it. There are limits on the kinds of collateral they can post, and they need to “over-collateralize their loans.

But the borrowing costs are subsidized, the terms are flexible and, in recent years, the timing has been right. Lending rates are only slightly higher than the Secure Overnight Financing Rate (SOFR). In the past few years, insurers have used the money to take advantage of rising interest rates on new bonds and to grow their high-yield private credit businesses.

“Life insurers often use these advances as part of a spread arbitrage program where the advances are reinvested in higher-yielding assets,” according to a recent Office of Financial Research report.

Federal Reserve researchers also have identified FHLB loans as a component of what RIJ has called the “Bermuda Triangle” strategy. The strategy, pioneered by Athene more than a decade ago, typically involves an asset manager-owned life insurer that issues investment-like deferred annuities, reduces its capital requirements with the help of Bermuda-based reinsurance, and—the ultimate goal—maximizes its investment in risky, high-return private credit.

In the purest form of the strategy, the annuity issuer, the Caribbean reinsurer, and managers of the private credit (via collateralized loan obligations, or CLOs) are all—as in the case of Apollo, Athene Annuity and Life, and Athene Re—affiliates of the same holding company. Fed economists and others have described the Bermuda Triangle strategy as opaque, conflicted, and a potential hazard to the stability of the global financial system.

Biggest annuity issuers borrow the most

When banks need liquidity, they can go to the Federal Reserve. When insurers need liquidity, they can sell commercial paper in the wholesale money market or use short-term loans (such as repurchase agreements, or “repos,”) that they can roll over indefinitely. If they are stock-owning members of an FHLB, they can borrow large sums from it, using their residential mortgage-backed securities (RMBS) and other safe assets (like Treasury bonds) as collateral.

Until 1989, FHLBanks had few if any insurer members. Today, the biggest life/annuity companies are also among the FHLB’s biggest borrowers. Of the 6,500 or so FHLB members, most are banks or credit unions. About 580 are insurers; of those, over 90% are life companies. While less than 10% of the FHLB membership, insurers account for about 20% of FHLB loans (called “advances”). Insurers held a combined $160 billion in FHLB loans at the end of 2024, double their 2016 share.

[FHLB advances peaked at more than $1 trillion in the first quarter of 2023. Of that, insurers borrowed $140 billion. In the following year, insurers borrowed $160 billion. Indebtedness fluctuates as loans are repaid or rolled over.]

If you look at the lists of the top five borrowers from each of the 11 FHLB branches, you’ll find 17 life insurers accounting for more than $80 billion in advances as of the end of 2024, according to the FHLBs’ year-end 2024 report. The single biggest FHLB borrower for 2024 was Athene Life and Annuity. It had $15.6 billion in outstanding funding agreements with the Des Moines FHLB and $17.2 billion as of March 31, 2025.

If a life insurer sells a lot of annuities, there’s a good chance that it’s also major customer of its regional FHLB. Athene sold the most annuities in 2024 ($40 billion) and the most in the first quarter of this year ($9.5 billion). Other top annuity sellers in 2024—Corebridge Financial, Equitable, Jackson National, Lincoln Financial, and Massachusetts Mutual—were all among the major FHLB borrowers.

While these FHLB borrowers (except MetLife) all sell retail annuities, they don’t all sell the same types of annuities. TIAA sells group annuities to retirement plan participants. Equitable was the top seller of registered indexed-linked annuities (RILAs, a type of variable annuity) in 2024, at $22.4 billion. Athene and MetLife are both active in buying corporate defined benefit pensions.

Jackson National sells both traditional variable annuities (tax-advantaged bundles of mutual funds) and RILAs. Massachusetts Mutual, one of three mutual insurers on the FHLB list, was the second-biggest seller of fixed annuities in 2024 (after Athene) and ranked third in overall sales (after Athene and Corebridge Financial).

Five of the major FHLB insurer/borrowers—Athene, Delaware Life, Equitrust, and Security Benefit Life of Denver—are asset manager-driven insurers that practice the Bermuda Triangle strategy. Massachusetts Mutual is one of only three mutual insurers, beside Thrivent Financial and United of Omaha, that borrows significantly from the FHLB. It too sells fixed indexed annuities, owns a Bermuda reinsurer, and works closely with alternative asset managers.

The costs and benefits of FHLB loans

If annuities are insurers’ source of retail borrowing, FHLB loans represent borrowing at the wholesale level. The money comes in bigger chunks, the borrowing costs are lower, and the loans are “fungible.” FHLB loans appears among an insurer’s liabilities, often as “funding agreements” but it doesn’t need to be applied to real estate-related investments. Insurers don’t need to sell long-term assets to obtain FHLB loans.

Obtained through the sale of funding agreements (akin to guaranteed investment contracts, or GICs), FHLB loans can be obtained without the acquisition costs—commissions—that are the steep price of gathering revenue through the sale of annuities. FHLB loans count as liabilities on the insurers’ balance sheets, they aren’t capital-intensive.

Because FHLB loans are implicitly backed by the U.S. government, the loans are cheap. As of a June 27, the lowest current cost for an FHLB loan was 3.82%, the rate on three-year money, according to a spreadsheet of historical FHLB rates. The daily reset (floating) rate was 4.487% overnight rate. For comparison, the SOFR (Secured Overnight Funding Rate) on June 27 was 4.40%. Maturities range from one day to 30 years, and terms include “fixed- or floating-rate pricing, prepayment, and structured options,” according to a 2024 Wellington Management white paper on the topic.

Though they represent only a fraction of insurer liabilities, FHLB loans are more liquid and potentially more versatile than other reserves. Life insurers use them “to fund a merger or acquisition, meet regulatory requirements, and serve as a working-capital backstop,” according to Wellington Management.

Those assets include the tranches in CLOs that insurers increasingly buy, often from the same asset managers who own them or partner with them.

“Insurers also use FHLB loans to manage and mitigate interest-rate and other risks, optimize risk-based capital (RBC), reduce cash drag, meet social goals, supplement ALM (asset-liability matching) duration, and arbitrage collateral. … Insurers may borrow funds to lock in reinvestment rates and extend the duration of existing investment portfolios, or to fill liability maturity gaps and tighten ALM duration.”

To join one of the FHLBs, institutions  borrowers buy stock in their regional FHLB, and top up their FHLB stock holdings when they borrow. “To capitalize advances, borrowers must purchase activity-based FHLB stock in addition to the stockholdings required for membership,” Wellington Management said. The shares pay dividends that further reduce the rate that insurers pay for the loans.

Insurers collateralize their FHLB loans with the real estate-related assets they already hold as reserves against annuity liabilities. They must “over-collateralize” and take a “haircut” (borrow less than 100% of the value of the collateral) when borrowing. The haircuts vary, depending on the underlying collateral.

FHLBs demand “housing-related” assets and other safe investments as collateral for their loans. That includes U.S. Treasuries, agency debt, agency and non-agency mortgage-backed securities (MBS), commercial MBS, whole first mortgages, housing-related municipal bonds, cash, and deposits in an FHLB can all be used as collateral.

Eligible collateral “must be single-A rated or above and housing-related,” according to Wellington Management. Corporate bonds, private debt, and equities can’t be used as collateral. FHLBs insist on having the collateral physically delivered to them, a measure that helps increase the safety and therefore the costs of the loans.

When the FHLB lends to banks, it has a “super lien” on the collateral, which in case of an insolvency the FHLB claims are senior to the banks’ other creditors. It’s apparently never been clarified—the situation has never arisen—whether the FHLB’s claims supersede the claims of policyholders when an insurer becomes insolvent.

Source: Congressional Budget Office.

Protests from consumer groups

The FHLBs have been accused of doing more to help their benefactors—the institutions that own their non-tradable stock—than to help their supposed beneficiaries, the low- and middle-income Americans who can’t find an affordable home to buy or apartment to rent.

FHLB’s mission is to push liquidity into the mortgage market and stimulate investment in real estate. It does that by contributing at least 10% of its own annual profits to affordable housing projects and by lending against real estate-related collateral.

According to the letter of the law and conventional wisdom, that’s what happens. “Insurance companies, through these investments, are liquidity providers for the MBS market, which in turn generates cost savings for individual homeowners,” according to Wellington Management.

But the banks pay out more in dividends to shareholders than they contribute toward home ownership. In 2024, the FHLB earned $6.36 billion and paid out $856 million to housing programs (13.5%). That’s more than the minimum required but short of the FHLB’s stated goal of 15%.

That amount is “a drop in the bucket compared to the country’s housing supply needs and is insultingly small,” wrote one critic in 2024. “It is fundamentally difficult to square these loans with the network’s purpose of boosting the country’s mortgage market.”

Government research groups such as the Congressional Budget Office, the Congressional Research Service (CRS), the Office of Financial Research have echoed those complaints in recent years. “Whether the FHLB system specifically facilitates mortgage funding or simply provides wholesale funding at below-market rates is debatable because the funding of assets is a fungible activity,” wrote a Congressional Research Service analyst in a 2024 report.

The FHLB’s own Report to Congress in 2025 conceded that “many member institutions eligible to join the FHLB system may not be principally engaged in residential mortgage finance, calling into question the extent to which FHLB advances subsidize the funding of mortgages or the funding of member institutions’ asset portfolios in general.”

The Bermuda Triangle connection

A handful of Federal Reserve economists have studied the change in business models of certain large life/annuity companies since the Great Financial Crisis of 2008. Several have concluded that FHLB loans are a component in the adoption of “shadow banking” as the main business of major annuity issuers. (“Shadow banks” are defined as wholesaler lenders outside the more heavily-regulated retail lending markets.)

Offshore reinsurance is another component of the business model. According to a 2023 paper, “Are Insurers the New Shadow Banks?,” by analysts in the Research and Statistics Division of the Federal Reserve Board:

Life insurers’ shadow banking businesses combine three types of entities in a triangular organizational structure. The first type of entity is US-domiciled life insurance companies. Large life insurers with an investment-grade rating can also tap wholesale funding markets by issuing nontraditional insurance liabilities to institutional investors. These liabilities include funding agreement-backed securities (FABS) and Federal Home Loan Bank (FHLB) advances collateralized by funding agreements. The second type of entity is captive reinsurers located in Bermuda… The third type of entity in the triangular organizational structure is an asset manager that originates, acquires, and manages corporate loans.

In this view, major annuity issuers that work closely with alternative asset managers (Apollo, Ares, Blackstone, KKR, etc.) now focus on obtaining inexpensive liquidity by selling low-risk deferred annuities and borrowing from FHLBs in order to finance their high-yield loans to high-risk borrowers.

It’s a lucrative trend—but one that worries the federal government’s Financial Stability Oversight Committee. According to the FSOC’s 2024 report, “Life insurers’ growing use of nontraditional liabilities, such as greater borrowing from capital markets and Federal Home Loan Banks (FHLBanks), could raise concerns about their ability to manage cash flows in times of stress, as well as concerns about their growing dependency on such credit facilities to sustain spread-based product lines.”

© 2025 RIJ Publishing LLC. All rights reserved.
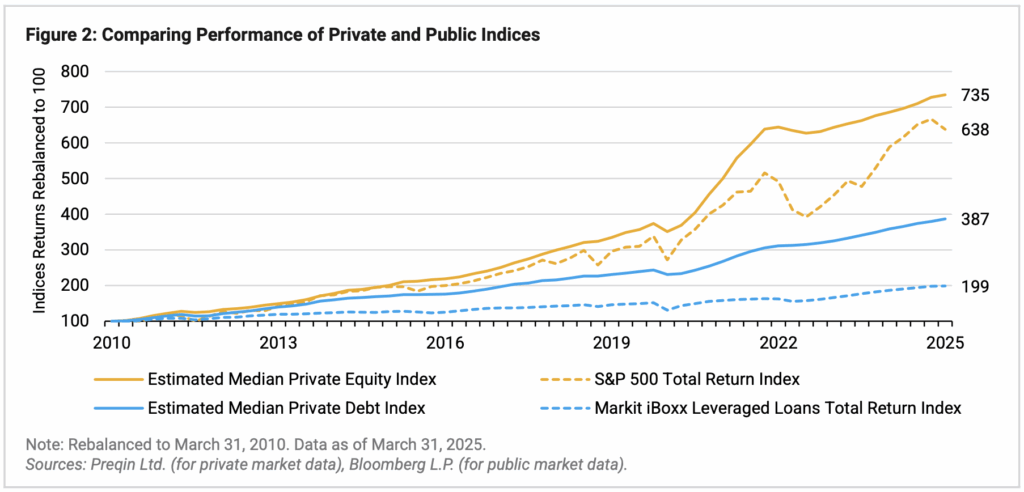


The Wheelhouse

Connecticut seeks buyers for insolvent PHL Variable

The actions needed to market and sell PHL Variable Insurance Co. or blocks of its business have taken longer than anticipated but are primarily completed, Connecticut Insurance Commissioner Andrew Mais wrote in a May 20 status report, AM Best reported.

The key terms of the plan are expected by the final quarter of this year.

The company’s finalized 2024 combined financial statement showed capital and surplus remain negative $2.2 billion. A year ago, the regulator projected that PHL would be out of assets by 2030 with ~$1.46 billion in policyholders’ liabilities still outstanding.

Mais and the rehabilitation team created a list of 50 potential buyers for all or parts of PHL’s business. By April 2025, 45 firms remained on the list and were given non-disclosure agreements for review.

As of May 20, 13 companies executed the NDA and were granted access to an actuarial appraisal report, a summary of existing reinsurance arrangements, and details regarding the companies’ arrangements with third-party administrative and investment providers.

Review of PHL claims against third parties is nearly complete. Some claims are viable, Mais said, but payments from all of the claims would not make PHL solvent. He hoped to resolve some claims without litigation.

Offshoring of life insurer liabilities tops $1T: Financial Times

US life insurers have now shifted more than $1 trillion worth of liabilities offshore despite regulators’ concerns about protections for retirement savings and broader financial stability, the Financial Times reported May 21. The report didn’t say how much capital relief the deals have provided US life insurers.

US life insurers’ and annuity providers’ total reserves ceded abroad, including liabilities moved to jurisdictions such as the Cayman Islands and Barbados, reached $1.1tn by the end of 2024. In many cases, “funds withheld” reinsurance arrangements, often with the insurers’ affiliated reinsurers, allow the insurers continue to manage the reserves but with smaller capital requirements.

Private capital-owned groups, such as Athene and Global Atlantic, as well as traditional insurers such as Prudential and MassMutual, last year moved more than $130bn of liabilities to offshore reinsurers primarily based in Bermuda, according to new figures from S&P Global Market Intelligence.

“Athene, acquired in 2022 by Apollo, had transferred the risk associated with liabilities worth $193bn to its offshore affiliates by the end of 2024, according to a Fitch analysis of regulatory filings for the Financial Times, in a strategy that helped to fuel a record-breaking year of US annuity sales for the insurer,” the British newspaper reported.According to the 1Q2025 statutory filing by Athene Annuity and Life, the company sold about $9.6 billion worth of annuities (mainly deferred fixed rate and fixed indexed) and gained $4 billion in liabilities more in the first quarter of this year through “reinsurance assumed” from other carriers.

But the insurer used $10.9 billion in “reinsurance ceded” to lower its new liabilities for the period to only $2.7 billion.  At the end of 1Q2025, the company reported $3.9 billion in surplus on $292 billion in assets (1.34%), after contributing surplus of $5.7 billion, the latest statutory filing showed.

Empower and Sagard partner to offer private assets in DC plans

Empower, the second-largest retirement services provider in the U.S., administering more than $1.8 trillion in assets for 19 million investors, will partner with Sagard, a global alternative asset manager with over US$27B of assets under management, in a new program that “will pave the way for private market investments to be included within defined contribution retirement plans,” according to a release.

Sagard-managed strategies will be made accessible via collective investment trusts in coming years. “These structures are designed to bring the benefits of private market investing—such as diversification, potential for enhanced returns, and exposure to less correlated assets—to retirement plan participants in a cost-efficient and liquidity-aware manner,” the release said.

The program will provide:

  • Access to Institutional-Quality Private Market Investments
    Portfolio Diversification
    Efficient and Transparent Structures

Empower has also aligned with private investments fund managers and custodians, including Apollo, Franklin Templeton, Goldman Sachs, Neuberger Berman, PIMCO, Partners Group and Sagard. Private investments offered through these firms may be implemented through collective investment trusts (CITs), providing limited exposure to diversified pools of private equity, private credit and private real estate, a structure that is designed to provide liquidity protection and reduced fee exposure.

MetLife’s investment arm managing $129.1 billion in private credit assets

MetLife Investment Management (MIM), the institutional asset management business of MetLife, Inc., has originated $21.6 billion in private credit transactions in 2024. MIM’s private credit assets under management stood at $129.1 billion as of December 31, 2024.

MIM’s origination included:

  • $6.8 billion in residential credit
  • $6.4 billion in corporate debt
  • $5.6 billion in infrastructure debt
  • $2.8 billion in asset-based finance transactions.

MIM’s $6.4 billion of corporate private placement origination was diversified across a range of industries. About $2.2 billion of MIM’s corporate private placement origination was outside of the U.S..

MIM’s infrastructure origination of $5.6 billion was driven by digital expansion and decarbonization of power generation. The firm’s focus on infrastructure sponsor relationships resulted in bilateral and direct deals comprising 40% of total origination. Nearly half, or $2.4 billion, of MIM’s infrastructure origination was outside the U.S.

MIM’s $2.8 billion of asset-based finance origination efforts were achieved primarily through the firm’s direct sourcing channels and were diversified across both structure and sector including $1.7 billion of commercial and consumer asset transactions and approximately $880 million in alternate asset financing.

Market uncertainty buffets annuity sales in 1Q2025: Wink

“It was a challenging first quarter for 2025 annuity sales, but sales are usually challenged coming-off the fourth quarter each year,” wrote Sheryl J. Moore, Chief Storyteller at WinkIntel, last week in her quarterly commentary on the annuity market.

Sales were impacted by the “89 negative rate adjustments over the quarter,” she noted. “Sixty-three percent of carriers experienced declines over 4Q2024 and 52% of participants experienced declines over 1Q2024. Overall, annuity sales were down nearly two percent from last quarter, and down nearly six percent from 1Q2024.”

Multi-year guaranteed were the star of the quarter—up 20% over the prior quarter. Dramatic sales increases from the top five sellers of the product fueled the bump. That said, sales were down nearly as much from the same quarter a year ago. This could be a record year for MYGA sales, due to relatively weak certificate of deposit (CD) rates.

Fixed annuities’ slight increase over last quarter was due to a single insurer buoying the product line. However, 66% of participants had sales declines from 1Q2024. We are projecting that sales of fixed annuities will be up for 2025.

Sales of indexed annuities were down from last quarter, and from the same quarter a year ago.  Nine of the top ten issuers of the product saw double-digit sales declines from the close of last year; just 30% experienced the same when compared to 1Q2024. That aside, it is still anticipated that indexed annuities will have record sales in 2025.

Like their fixed indexed brethren, the favored structured annuity also had a challenging sales quarter. While sales were down versus last quarter for 56% of issuers, only 17% of insurers experienced the same when comparing sales to this time last year. Notwithstanding, sales of structured annuity could set a new record in 2025.

Unsurprisingly, traditional variable annuity sales were down from last quarter. However, sales of the line were the highest in nearly three years. Continued equity volatility will no doubt negatively impact sales of VAs for the second quarter. We expect traditional variable annuity sales to be lower in 2025 than 2024.

Midland and DFA to partner on index-linked annuity solutions

Midland Advisory, part of Midland National Life Insurance Company, will collaborate with Dimensional Fund Advisors to enhance index-linked annuity solutions. Advisors will be able to access Dimensional’s investment philosophy within the framework of a registered index-linked annuity (RILA), in which performance is linked to a custom index constructed using Dimensional’s systematic active Exchange Traded Funds (ETFs).

By offering this index option, Midland National provides advisors and their clients with a structured growth opportunity within an annuity framework, combining exposure to the potential returns of equity markets with a RILA’s index-linked strategies. This index is one of several available options, as potential performance may also be linked to two other indices or based on seven variable subaccounts.

Brighthouse loses $294 million in 1Q2025, condemns unsolicited ‘mini-tender’ offer

Brighthouse Financial, Inc.  (Nasdaq: BHF) announced its financial results for the first quarter ended March 31, 2025:

  • Estimated combined risk-based capital (“RBC”) ratio between 420% and 440%
  • Holding company liquid assets of $1.0 billion
  • The company repurchased $85 million of its common stock year-to-date through May 6, 2025
  • Annuity sales of $2.3 billion, including $2.0 billion in sales of the flagship Shield Level Annuities
  • Life sales of $36 million, reflecting continued growth of the company’s life insurance suite
  • Net loss available to shareholders of $294 million, or $5.04 per diluted share
  • Adjusted earnings, less notable items, of $245 million, or $4.17 per diluted share

In other news, Brighthouse said that it received notice of an unsolicited “mini-tender” offer made by Potemkin Limited (“Potemkin”) to Brighthouse Financial shareholders to purchase up to 100,000 shares of Brighthouse Financial’s common stock at a price of $36.00 per share. Brighthouse Financial shareholders who tender their shares in the offer will receive a price significantly below the current market price for the company’s common stock and which is an approximate 41.12% discount to the closing price of the company’s common stock as of May 19, 2025 ($61.14 per share).

Brighthouse Financial said it doesn’t endorse Potemkin’s unsolicited mini-tender offer and is not affiliated or associated in any way with Potemkin, its mini-tender offer or the offer documentation. Brighthouse Financial recommends that shareholders do not tender their shares in response to Potemkin’s offer because the offer is at a price that is significantly below the current market value of Brighthouse Financial’s common stock, a Brighthouse release said.

The offer is currently scheduled to expire at 5:00 p.m., New York City time, on September 16, 2025, unless extended or earlier revoked by Potemkin. Shareholders who tender their shares may withdraw them in the manner described in Potemkin’s offering documents.

A mini-tender offer is an offer for less than 5% of a company’s shares and is therefore not subject to the disclosure and procedural requirements required by the U.S. Securities and Exchange Commission (“SEC”) for larger tender offers. As a result, mini-tender offers do not provide investors with the same level of protections under U.S. securities laws that are provided for larger tender offers. The SEC has cautioned investors about mini-tender offers.

Jackson enhances features of RILAs and traditional variable annuities

Jackson National Life, the main operating subsidiary of Jackson Financial Inc., has added Jackson Market Link Pro III (JMLPIII) and Jackson Market Link Pro Advisory III (JMLPAIII) to its lineup of registered index-linked annuities (RILAs). JMLPIII is commission-based and JMLPAIII is fee-based. Jackson also enhanced its traditional variable annuity product suite.

JMLPIII and JMLPAIII upgrades included:

Nasdaq 100: This new index option is now offered along with the S&P 500, Russell 2000, MSCI EAFE and MSCI Emerging Markets.

  • Full principal protection: There’s a 100% “buffer” protection option for the 1-year Cap, 3-year Cap, 6-year Cap and 1-year Performance Trigger crediting methods, in addition to existing 10% and 20% buffer options. Clients may also select a “floor” protection option. A buffer absorbs losses except those in excess of a certain percentage drop in account value over a crediting period. A floor stops losses after a certain percentage drop in account value over a crediting period.

Jackson’s RILA suite also offers:

  • Multiple term lengths:  Jackson offers 1-year, 3-year and 6-year Index Account Option terms.
  • Multiple crediting methods: Consumers can tailor their growth potential and protection level. The “Performance Boost” methodology can potentially produce gains in scenarios where the index return is flat or negative.
  • Index participation rate on Cap crediting method: Jackson’s RILA suite features a combined crediting method that can provide greater upside growth opportunity when the market conditions are favorable.
  • Intra-term performance lock feature: The Performance Lock option enables contract owners them to lock in their interim value at any point during the Index Account Option term by moving the locked-in amount to a short-duration fixed account until the next contract anniversary.
  • Legacy and cost control: A built-in death benefit with no annual contract fee helps protect the value of the account for beneficiaries.

Jackson also announced enhancements to its variable annuities (VAs).

  • Guaranteed withdrawal rates: Jackson increased the Single Life and Joint Life Guaranteed Annual Withdrawal Amount Percentages (GAWA%) across its Flex Core, Flex Net Core, Flex DB Core, and Flex Plus living benefit options.
  • Guaranteed withdrawal balance (GWB) adjustments: Jackson increased the maximum Guaranteed Withdrawal Benefit adjustment to 200% for its Flex Plus benefits, guaranteeing more income for clients who delay withdrawals for at least 12 contract years or until age 70, whichever is later. The updates apply to Perspective II, Perspective Advisory II, Jackson Advantage and Retirement Latitudes VA contracts.

iCapital buys advisor to Citi Wealth investment platform

iCapital, the global fintech platform, is acquiring Citi Global Alternatives, LLC, the advisor to Citi Wealth’s global alternative investment fund platform. The platform represents more than 180 alternatives funds distributed globally, with vehicles for exposure to private equity, growth equity, private credit, infrastructure, venture capital, real estate and hedge funds, according to a release.

iCapital will manage and operate the fund platform. Citi will continue to distribute the funds and advise clients on the benefits of alternative investments. Terms of the purchase agreement were not disclosed.

The Standard improves its Enhanced Choice Index Plus annuity

The Standard recently added new features to its flagship single-premium, deferred fixed index annuity, the Enhanced Choice Index Plus. The additions are built-in guarantees, crediting strategies and the S&P 500 Dynamic Intraday TCA Index.

ECI Plus now offers 10 allocation options with guaranteed rates for 5 to 10 years, depending on the selected strategy. This includes fixed interest crediting, now enhanced with a multiyear rate guarantee. The newly added Locked Cap Rate and Locked Trigger Rate strategies allow clients to lock in an annual crediting formula on the S&P 500 for 5 or 7 years.

The newly introduced Trigger Rate and Trigger Rate Plus strategies help accounts grow even when the index underperforms. With the Trigger Rate strategy, clients benefit from any flat or positive movement in the index. The Trigger Rate Plus strategy offers built-in growth, even when index performance declines.

Rebalanced up to 13 times a day, the S&P 500 Dynamic Intraday TCA Index responds to market fluctuations. A 15% volatility target allows for greater exposure to the S&P 500 while maintaining more stable volatility compared to traditional risk control indices. Clients can access this newly added index using a Cap Rate, Participation Rate, Trigger Rate or Trigger Rate Plus strategy.

© 2025 RIJ Publishing LLC.