Archives: Articles

IssueM Articles

When the AI Bubble Bursts, Who Will Be Left Holding the Bag?

A new paper making a stir in the financial press spells out the dangers to which private equity-owned life insurance companies are exposed by private credit funds with large portfolios of loans to software and AI companies. It’s a complicated story that could have enormous consequences.

Pranjal Drall and Andrew Granato, the report’s authors, argue that some of these insurance companies could become insolvent if these loans crash. And an unanticipated consequence of a 60-year-old rule that protects insurance company policy holders from losing all of their life insurance benefits or annuity payments could leave taxpayers holding the bag.

Let’s step back to understand some of the backstory. In 2022, I wrote about private equity firms gobbling up life insurance companies, and in 2026 about the risky, high-fee investments these companies were making with people’s life insurance and annuity premiums. Private equity firms are best known for theprivate equity (PE) buyout funds they sponsor. These funds buy up anything from doctor’s practices to single-family homes to youth sports leagues. PE funds use money committed by their investors as the down payment (the equity) on these acquisitions, and they use lots of debt to acquire companies in what are known as leveraged buyouts (LBOs).

As PE firms diversify their holdings, life and annuity insurance companies are an attractive target because they amass premium income, but may not need to pay out benefits for years or even decades. PE’s interest in owning life insurance companies emerged in earnest in 2009 following the Great Financial Crisis, and accelerated in the early 2020s. While traditional insurance companies mostly invested premium income in corporate and Treasury bonds, PE firms count on earning high fees for managing risky investments made with these assets, and on profiting from the spread between what it owes policyholders and what its investments earn.

There are no legal barriers to PE-owned insurance companies using their assets to support struggling companies also owned by their PE owner, and no prohibition on selling poorly performing loans of a PE-owned company to an insurance company owned by the same PE firm. PE-owned life insurers also extract value by transferring assets and liabilities to a shadow reinsurer it owns or is affiliated with. This can reduce the insurance company’s tax liabilities, lower its capital requirements and hide the extent of the risk it is exposed to.

Private Credit Funds Make Big Bets on Software and Data Centers

Stricter financial regulations put in place following the Great Financial Crisis were intended to prevent similar catastrophes in the future. The regulations limited the amount of debt that regulated financial institutions could put on a company, crimping the ability of PE funds to use as much debt in LBOs as they wanted. Banks were restricted from making riskier loans, and this resulted in small- and medium-sized companies finding it difficult to get bank financing.

Immediately, private equity firms stepped into the breach and created private credit funds to make direct loans to companies frozen out of public financial markets. Private credit funds are sponsored by investment firms, including PE firms. They are not subject to the regulations intended to make the financial system safer. They operate in the shadows, making risky loans to companies, many of whom don’t qualify for bank loans. Today, private credit funds hold $3 trillion in largely unregulated, high risk, opaque loans — many made to companies owned by PE firms.

Private credit funds have been a hot investment for the last 16 or so years. These loans are not subject to the rules that govern corporate bonds. Because the loans are risky, lenders demand a premium and borrowers pay high interest rates — a profitable situation that rewards investors in these funds. The funds have bet big on software firms that create code and develop management tools that businesses subscribe to, providing them with multi-billion-dollar loans.

The software tools manage various business operations — customer relationships, workflow and corporate spending — and are collectively known as Software as a Service (SaaS). Private credit funds are also behind the multi-billion-dollar loans to the huge data centers that AI firms are building to train their latest AI models.

Where do these billions of dollars come from? While there are multiple sources of funding for private credit funds — including investment banks like Goldman Sachs that are barred from making these loans directly, and pension funds looking for lucrative payoffs — private equity-owned insurance companies figure prominently as a source of capital for these funds. Investments in SaaS have been the bread and butter of private credit funds. The recurring income these companies generate from business subscribers have enabled them to make payments on their massive loans; default rates have been low.

But share prices of these software companies cratered in 2026 under pressure from Claude, AI company Anthropic’s code-writing frontier model and other similar models. As a whole, these AI tools are undermining the SaaS business model and challenging the “assumptions around software growth, pricing power and borrower durability.

“ Investors in private credit funds worry that many of the SaaS companies will not be able to repay their loans. Similar doubts are being raised about the construction of super expensive data centers that private credit funds are financing amid rising concerns about an AI bubble and anxiety about what will happen if the bubble bursts. Will many of the data centers become white elephants, deserted by the AI firms that planned to use them to develop new AI models? Will the return on investment in models trained in these expensive data centers justify business spending on these high-cost AI models? Will the much cheaper Chinese AI models out compete the US models and take market share away from American AI companies? These questions are raising doubts about whether all of these loans can be repaid. And if the loans can’t be repaid, what then?

Insurance Regulations Could Bail Out Risky PE Bets

PE-owned life insurance companies will see their investments in private credit funds crushed, marked down substantially or even wiped out. Private credit default rates above 15% may lead some insurance companies to become insolvent and unable to make good on the life insurance payouts or annuity payments promised to beneficiaries.

At that point, state Insurance Commissioners will step in. Rules put in place decades ago to protect beneficiaries of insurance companies enable the commissioners to require the remaining life insurance companies in the state to pay into a special guaranty fund that will make good on the policies held by the beneficiaries of the defunct company, up to a cap of about $300,000 on life insurance and about $250,000 on an annuity. That varies by state. Insurance companies not affiliated with a PE firm and that didn’t make risky bets on private credit will be required to bail out the failed insurance companies that did. And the PE firm that owned the insolvent company will get off scot-free and not have to pay anything. That creates a moral hazard and seems to be a miscarriage of justice.

But the story doesn’t end there. In 44 states, these payments are fully creditable over five years against state taxes on premium income. That means that, ultimately, it is taxpayers in those states that provide the backstop when software and/or AI companies can’t repay their loans to private credit funds, and a PE-owned insurance company that invested in private credit funds becomes insolvent. The result is, as the report’s authors point out, “a system that socializes losses.”

© 2026 Eileen Appelbaum. Reprinted by permission of the author.
Advisors’ allocations to private capital could reach $4.2T in five years: Cerulli

U.S. financial advisors currently allocate $2.2 trillion to less-than-fully-liquid private capital, and could manage an additional $2 trillion in the next five years “if the buildout of interval fund solutions, the adoption of other less-than-fully-liquid private capital product, and the streamlined access offered by alternative asset allocation models continues to grow,” according to The Cerulli Report—U.S. Private Markets 2026.

Many advisors believe that allocations to private assets will demonstrate value-add to clients and respond to investors’ demand for income-generating investments, Cerulli surveys show.

To scale private market solutions across retail channels, partnerships between traditional and private capital managers will be key. “Traditional asset managers seek differentiated capabilities that can enhance their product offerings and support more competitive value propositions,” said Daniil Shapiro, director at Cerulli.

“Private capital managers often lack the distribution scale and brand recognition required to penetrate retail channels, particularly beyond the ultra-high-net-worth segment and into the broader affluent market.”

Distribution is expanding into models, multi-asset vehicles, and defined contribution (DC) plans, creating a greater need for collaboration among asset managers, technology platforms, turnkey asset management providers (TAMPs), trust companies, and recordkeepers, Cerulli said in a release.

© 2026 RIJ Publishing LLC.

Mapping Private Markets, the Apex of the Bermuda Triangle

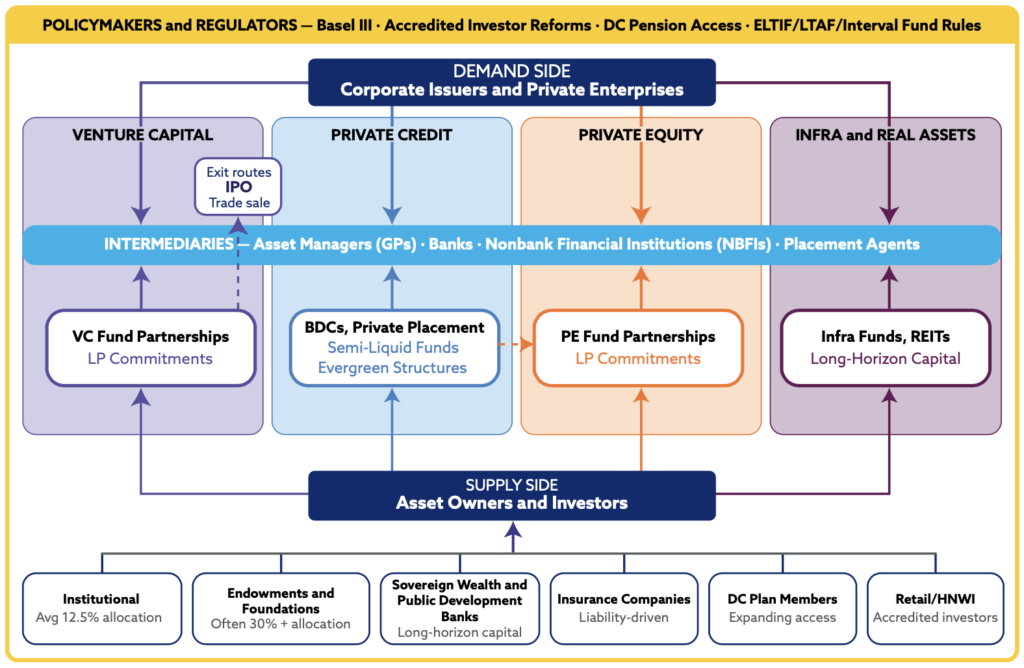
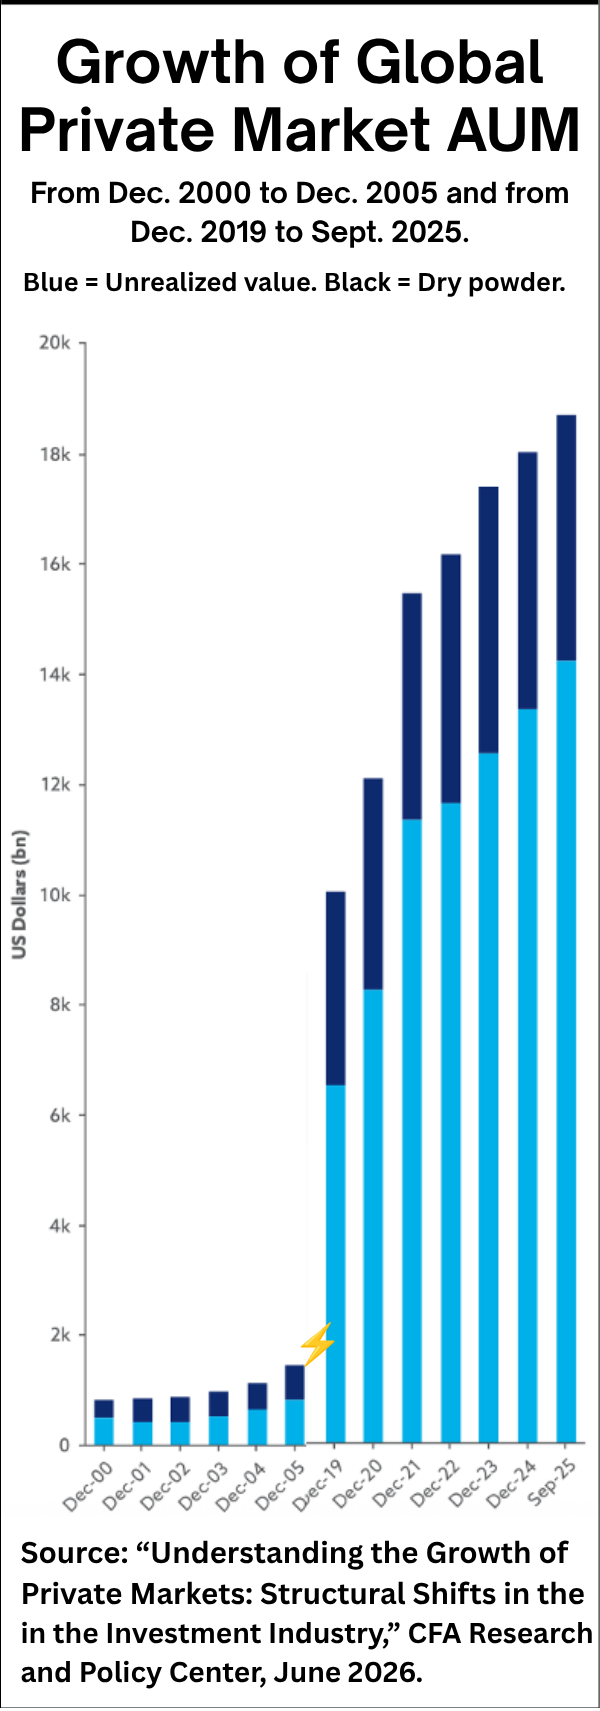
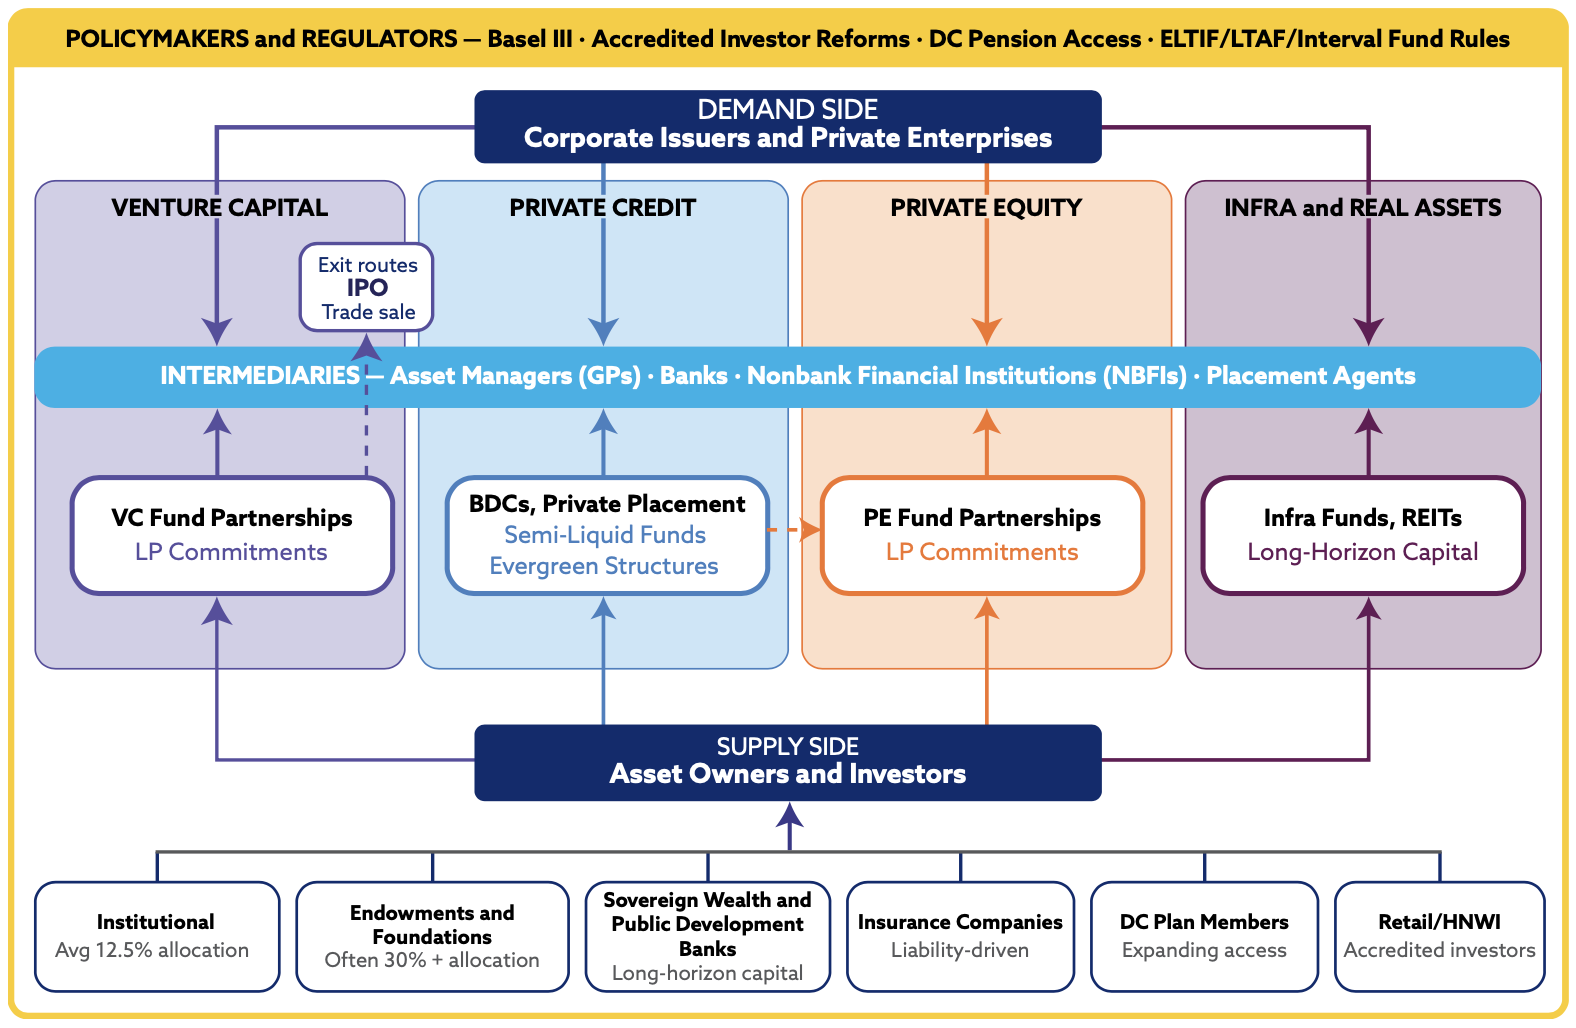
In a recent report, “Understanding the Growth of Private Markets: Structural Shifts in the Investment Industry,” the CFA Institute’s Research and Policy Center has done a useful service to Bermuda Triangle watchers by mapping the world of private market assets and its stakeholders. (See chart above/at right.)

That world represents one of three three legs of what RIJ calls the Bermuda Triangle strategy, which includes, within the same holding company: an alternative asset manager (e.g., Apollo, Blackstone, KKR, Eldridge, Guggenheim Partners), one or more life insurers that issue fixed deferred annuities (e.g., Athene, F&G, Global Atlantic, Security Benefit, Delaware Life) and an affiliated reinsurer in Bermuda or the Cayman Islands.

[Long-standing, stalwart life insurers like Prudential, MassMutual, Lincoln Financial, Pacific Life and others have adopted parts of this strategy. They’re more likely to sell registered index-linked deferred annuities (RILAs). These are SEC-regulated contracts that these insurers distribute through their familiar broker-dealer partners instead of through the insurance market organizations (IMOs) that emphasize fixed annuities.

The private market investment, and the alt-asset managers, can claim to represent the apex of the Triangle, since the other two legs are there primarily to help finance private credit and related high-yield assets. The life insurers buy the asset managers’ alt-assets and the reinsurers expand the life insurers’ annuity sales capacity by assuming the cost of some of their risks and letting them conserve capital or “release” it for stock buybacks or new ventures.

So, if you want to understand the Bermuda Triangle–or the increasing distribution by alt-asset managers of their private market products through retail channels (via exchange-traded funds) or through institutional channels (via 401(k) plans, it helps to understand the apex of the triangle. This chart will help.

Understanding The Private Market Ecosystem Stakeholder chart

Start at the low end of the chart. Asset Owners and Investors (bottom row) deploy capital upward through access vehicles—limited partner commitments to venture capital (VC) and private equity (PE) fund partnerships, business development companies (BDCs), interval funds, evergreen structures, and infrastructure funds—into four private market channels.

Corporate Issuers and Private Enterprises (top) access financing downward: startups and growth firms via venture capital, mid-market firms via private credit, restructuring and buyouts via private equity, and real asset projects via infrastructure funds. The Intermediaries bar (center) represents the asset managers, banks, NBFIs, and placement agents that channel capital between the two sides. Exit routes connect private to public markets (IPOs, trade sales).

The dashed connection between Private Equity and Private Credit reflects frequent cross-channel financing. The Policymakers and Regulators frame (yellow border) represents the regulatory architecture shaping the ecosystem—rules include Basel III, accredited investor reforms, defined contribution (DC) pension access, and dedicated fund structures (e.g., European long-term investment funds [ELTIFs], long-term asset funds [LTAFs]). GP stands for general partner; HNWI stands for high-net-worth individual.

© 2026 RIJ Publishing LLC.

The Animus behind DOL’s ‘Amicus Briefs’

A human resources manager was once asked why the participants in her company’s 401(k) plan didn’t have a seat on the plan’s investment policy committee. “What do you mean?” she said. “Everyone on the committee is a participant.”

There’s an ambiguity in the regulation of 401(k) plans under the Employee Retirement Income Security Act of 1974 (ERISA). Where’s the line between plan sponsors and plan participants? And which side of the line does, or should, the Department of Labor (DOL) stand on?

Is there a contradiction between a plan sponsor’s duty to act solely in the participants’ best interests and an employer’s option not to sponsor a plan at all if the duties seem too onerous… in terms of litigation costs?

Different administrations in Washington appear to answer differently. By filing so-called “amicus briefs” on behalf of the corporate plan sponsors—the defendants—in several participant-led, ERISA-based class action suits, the Trump DOL has signaled its friendship with, logically, the corporations.

For example:

  • On July 10, a DOL amicus brief urged the U.S. Supreme Court to affirm a lower court’s dismissal a participant-led suit contending that in Anderson v. Intel, Intel Corp. acted imprudently by investing its 401(k) plan funds in hedge funds, private equity and other “non-traditional,” “allegedly risky” assets.
  • On July 21, a DOL amicus brief in Doherty v. Bristol-Myers Squibb asked the Second Circuit (Southern New York) to clarify the business requirements for corporate decisions to execute pension risk transfers (PRTs). This suit challenged Bristol-Myers Squibb’s decision to exchange its defined benefit plan assets for a group annuity issued by life insurers in Athene Holding, a segment of Apollo Global Management.
  • On July 24, a DOL amicus brief urged the U.S. Court of Appeals for the 4th Circuit (Eastern North Carolina) to affirm a district court’s decision to dismiss the claims in Stana v. SAS Institute Inc., that the employer breached its fiduciary obligations by not using forfeited funds (i.e., employer “matching contributions” forfeited by employees who separate from the employer before their contributions vest) for plan expenses.

It’s a truism that corporations’ biggest fear in sponsoring 401(k) plans, in picking service providers, and signing off on investment menus, is getting hit with federal class-action suits where participants question their decisions and demand tens of millions of dollars in compensation for alleged violations of ERISA’s requirement that sponsors act prudently and “solely” in the interests of participants.

In its amicus briefs, the Trump DOL addresses that fear, and leans in on behalf of the plan sponsors. Besides supporting the plan sponsors’ legal positions, the DOL warns that participant-led ERISA lawsuits, and the plaintiffs’ attorneys who bring them, threaten to discourage corporations from sponsoring plans at all. That reverses the Obama DOL’s approach.

These cases have other implications—pertaining to a plan sponsor’s choice of a “Bermuda Triangle” annuity issuer (in Doherty v. Bristol-Myers Squibb) and a 401(k) plan sponsors right to put alternative investments in its plan (Anderson v. Intel). But let’s look first at the Trump DOL’s shot-across-the-bow at participant-led suits in general.

‘Disincentivizing employers’

In its press releases, the Trump DOL gets right to the point. Its interventions in these cases aren’t just tactical but also strategic: to discourage future participant-led federal class-action suits against 401(k) plan sponsors.

A DOL’s press release called its amicus brief in Anderson v. Intel “one in a series filed by the DOL focused on ending the overuse of litigation against ERISA retirement plans and those who manage them.” The department’s press release about Stana v. SAS Institute said, “Continued litigation of this type could have the unintended effect of disincentivizing employers from creating retirement plans.”

In its amicus brief in Stana v. SAS Institute, the DOL took close aim at plaintiffs’ attorneys when it wrote, “private-party ERISA litigants (or, more specifically, private-party ERISA litigators) are now trying to contort these well-intentioned shields [i.e., “ERISA-imposed fiduciary duties” on plan sponsors] into cynical swords that often hurt the American worker.”

In the Bristol-Myers case, the DOL brief “argues that pension risk transfers benefit both employers and beneficiaries when not disrupted and litigating business decisions can hinder or eliminate benefits.” The department added that “continued litigation could deter employers from derisking their plans and ultimately upset the balance Congress established between federal and state regulation.”

The DOL characterizes decisions to trade a defined benefit plan for a group annuity as “business decisions” rather than participant-driven decisions, and characterizes pension risk transfers as a defined benefit (DB) plan sponsor’s effort to “derisk” a DB plan rather than a decision to reduce the sponsor’s costs in operating the plan.

Plaintiffs’ attorneys representing participants feel differently. “The DOL of old would frequently file amicus briefs on behalf of plaintiffs,” said Edward Stone, a Greenwich, CT, ERISA plaintiffs’ attorney. “We are seeing a DOL made in Trump’s image.  It has surrendered its ERISA watchdog role and morphed into a big player in the game of regulatory Jenga. It will inevitably lead to huge policyholder losses and get out of jail free cards for those foxes guarding the henhouse of retirement security.”

The future of private market assets in 401(k)s

The DOL’s intervention in Anderson v. Intel struck one knowledgeable observer as aligned with the Trump administration’s August 2025 executive order blessing alternative assets, including private equity, private credit, retirement income-generating tools, and even cryptocurrency, in 401(k) investment menus.

In that case, first filed in slightly different form a decade ago, former participants sued Intel for keeping hedge fund and private equity investments in its customized target-date fund series even as these investments hurt the funds’ performance. A federal appellate court has affirmed a lower court’s dismissal of the participant’s suit.

The Circuit Court judge ruled that the plaintiffs hadn’t provided a suitable benchmark against which to measure the performance of the Intel TDFs with private market assets. (The case is a bit unusual: Intel had used alternative investments in its defined benefit plan. When designing the target-date fund for its 401(k), the computer chip maker put alternative assets there as well.)

Mark Fortier was an executive at AllianceBernstein, the asset manager that succeeded Intel as investment manager of Intel’s target-date fund. Alternative asset managers, he said, might try to use the Intel ruling, along with DOL’s amicus brief, to show plan sponsors that they can include private market assets in their target date funds as long as they carefully look for and find an appropriate benchmark.

“The [DOL] amicus briefs [in the Intel case] give alternative asset managers marketing material to give sponsors,” Fortier told RIJ. “The asset managers like that story,” he said. “They can say, ‘Don’t worry, a prudent [due diligence] process will set you free.”

But the ambiguous nature of private market assets—are they volatility-reducing diversifiers or yield enhancers—might hinder the search for a suitable benchmark for their expected performance in target-date investments that include an allocation to them, Fortier believes.

“This is a subtle issue that the Intel suit doesn’t address,” he told RIJ. “What is the asset class that you’re trying to benchmark?” Do private market assets/alternatives deliver a higher return for the same risk as public market assets, as the alt-asset managers say? Or do they deliver the same returns for a lower risk, as the hedge fund managers say?

You can’t have it both ways, he said: “The “no free lunch” advocates like myself don’t buy it.” And a plan sponsor can’t choose an appropriate benchmark until it determines what alternative assets are supposed to do.

Amicus v. animus

ERISA was passed in 1974, near the end of a decade of civil unrest in the U.S. and of new “civil rights” legislation that recognized minority rights and that was aimed at placating, rather than punishing, much of the unrest. That legislation spawned thousands of pages of regulations, which put teeth in the laws.

Champions of a myriad of newly-articulated rights—not only of people of color but of voters, women, the environment, the aged and disabled, animals, tenants, the incarcerated, and pension plan participants—were soon able to wield those regulations as legal weapons against large corporations in class-action suits that organized previously diffuse interests into powerful “interest groups.”

From the beginning—no later than the 1968 presidential election—the wave of civil rights reform sparked a counter-reformation from both Democratic and Republican administrations. Their animus was directed at “regulations” and “red tape” in general, but it often included criticism of the litigation targeting politically-influential corporations, filed by plaintiffs’ attorneys whose fees were contingent on victory in court, that the regulations made possible.

The DOL’s recent ERISA briefs signal the Trump administration’s amicus with that animus.

© 2026 RIJ Publishing LLC.

Indexed annuity updates from Corebridge and Delaware Life

Corebridge enhances Power Series

Corebridge Financial, whose merger with Equitable nears completion, has added Protected Growth Benefit and “preset allocation options” to select versions of The Power Series of Index Annuities. The changes will enhance “the accumulation and diversification capabilities” of the company’s index annuities, a release said.

Protected Growth provides a guaranteed minimum accumulation benefit (GMAB). “While there are no fees for this optional product feature, interest crediting rates are lower when Protected Growth is elected,” according to the release. The Protected Growth Benefit rate for contracts with a 7-year surrender period is currently 26.25% and 17.5% for contracts with a five-year surrender period.

A contract with a $100,000 premium would have a guaranteed minimum contract value of $126,250 after seven years or a guaranteed minimum contract value of $117,500 after five years, depending on the term of the contract. The Protected Growth Benefit is available only on Power Index 5 Plus and Power Index Plus and is not available in California or New York.

Contract owners can pick any of five pre-set, blended indexing strategies – U.S. Stability, Global Stability, Balanced, U.S. Growth, and Global Growth – that include allocations to the S&P 500, Russell 2000, PIMCO Global Optima Index, MSCI EAFE, ML Strategic Balanced Index and Franklin Quality Dividend.

Pre-set allocation options are available in select products within The Power Series of Index Annuities family. There are no fees associated with this product feature. For more information, visit What We Offer on corebridgefinancial.com.

Delaware Life introduces TrackGuard+

Delaware Life Insurance Co. has launched TrackGuard+, a bonus fixed index annuity (FIA) that adds “a high upfront premium bonus” and “enhanced in-contract liquidity” to several index crediting strategies and the customary principal protection.

TrackGuard+ features:

  • A 21-26% bonus on the first-year premium. The bonus varies by state and is subject to a recapture schedule if the contract is surrendered during the surrender period. The client keeps all the interest credited to the bonus from contract issue even if the bonus is later recaptured.
  • Available indexes are the S&P 500 Dynamic Intraday TCA, Nasdaq-100 Volatility Control 12%, BlackRock U.S. Equity Bitcoin Balanced Risk 12%, Barclays Aries, and the S&P 500.
  • Beginning in the second contract year, for 0.95% fee, clients can carry forward any unused free withdrawal percent from the prior year, stacking on top of the standard 7% annual allowance for up to a maximum of 28% penalty-free access in a single year. The benefit applies even after a prior-year withdrawal.
  • Starting in the fifth contract year, policyholders are guaranteed at least 100% of premium (less withdrawals and net of market-value adjustments, recaptured bonus, and contingent deferred sales charges) on surrender. The benefit increases to amounts exceeding 100% of premium in later years.
  • At the end of year 10, the Premium Guard benefit ensures the account value is at least equal to premiums plus premium bonus (less prior withdrawals and recaptured premium bonus). The Premium Guard Credit will be applied pro-rata across the current allocations after any applicable fees are taken.

© 2026 RIJ Publishing LLC.

CANNEX’s new CEO: Gary Baker

CANNEX, a leading provider of pricing, data and analytics for annuities in North America, and for banks’ term deposits and guaranteed interest contracts (GICs) in Canada, has named Gary Baker as its new Chief Executive Officer.

Previously the Chief Operating Officer of CANNEX, Baker succeeds Lowell Aronoff, who cofounded CANNEX in 1984. Aronoff will become the chairman of a newly created board of directors.

Baker brings more than 30 years of financial services experience focusing on retirement products, including prior executive roles at Mass Mutual and GE Capital, and has spent the last 16 years helping shape CANNEX’s growth.

“The pace of technological change in our industry is faster than at any point in CANNEX’s history, and our clients expect us to move with it,” said Baker. “We are accelerating our investment in AI-enabled infrastructure to build the next generation of data and analysis solutions in support of regulatory standards in the U.S. and Canada.

“This is a natural evolution of the strong foundation Lowell and our late cofounder, Alex Melvin, built over the past 40 years, and I’m energized to lead CANNEX into this next phase.”

“Over the past 16 years, Gary has been an incredible leader within CANNEX,” said Aronoff. “He understands what makes CANNEX unique and how to leverage our strengths to capitalize on the opportunities we see to grow the business at this critical moment.”

© 2026 RIJ Publishing LLC.

Bracing for Health Costs in Retirement

The cost of health insurance shouldn’t be an American retiree’s biggest financial worry; Medicare does much of the heavy lifting. But Medicare isn’t free, nor are Medicare supplements. Insurance premiums, co-pays, deductibles are additional future expenses that retirees, or retirees’ financial advisers, shouldn’t ignore.

And then there’s the Medicare surcharge (the “IRMAA”) and possibly the costs of “continuing care,” long-term care or LTC insurance. Some of these health care-related expenses are foreseeable while others are, as the aging mind and body discovers, quite unpredictable.

But now there are apps for that. And there’s research that might inspire advisers to add such apps to their retiree toolboxes.

In a report published earlier this year, HealthView Services, a Middleton, Massachusetts firm that produces the apps and generates the research, presented national actuarial data (based on 530 million health care cases) showing that for an average healthy 65-year-old couple, total annual healthcare costs for traditional Medicare programs commonly selected by advised clients, which includes Parts B, D, Medigap (Plan G) and out-of-pocket expenses, will rise from $14,678 in the first year of retirement to $49,094 at age 85, assuming that the man lives to age 88 and a female spouse to age 90.

Over a couple’s lifetime (48 person-years in the example), HealthView projects combined healthcare costs of $581,587 (in today’s dollars) or $839,596 (in future, inflation-adjusted dollars). Those estimates don’t include long-term care expenses or Medicare surcharges (the IRMAA, or Income-Related Monthly Adjustment Amount) on single Medicare beneficiaries with taxable income (in 2026) over  $109,000 or couples earning over $218,000.

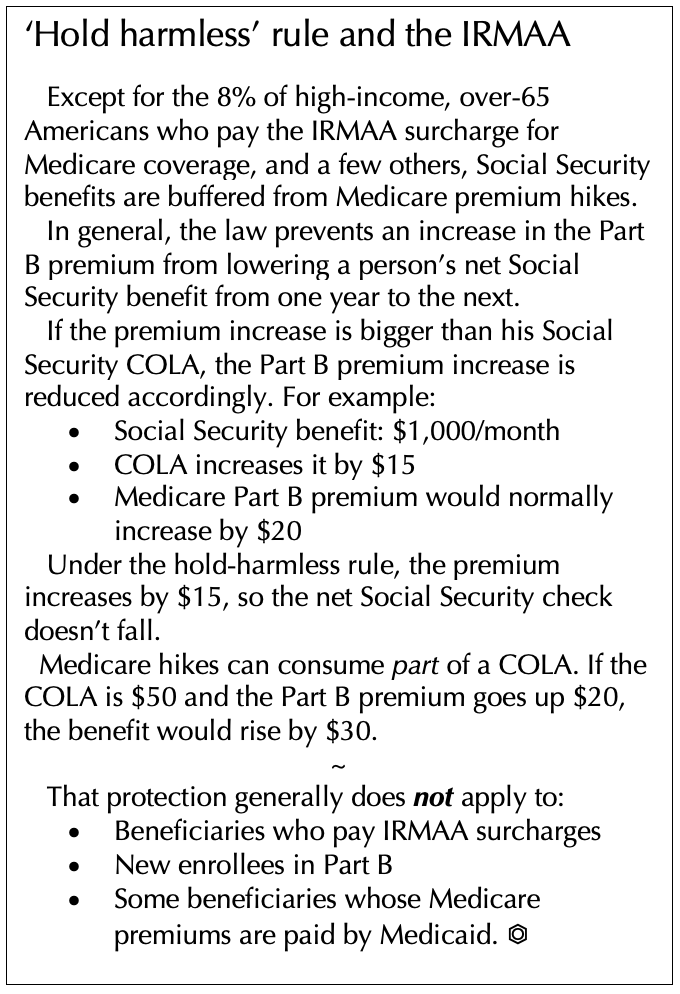
( Kiplinger.com reports that “The IRMAA Part B surcharge [for 2026] ranges from $81.20 to $487.00 monthly, or $974.00 to $5,844.00 annually, on top of the base premium of $202.90. The IRMAA surcharges for Part D in 2026, based on the national base beneficiary premium of $38.99, range from $14.50 to $91 per month, or an annual rate of $174 to $1,092.)

HealthView updates its estimates regularly. Fidelity Investments has published similar data in the past. If their estimates are shocking, it’s mainly because they’re lump-sum present-values and future-values. In the real world, most people experience health insurance premiums as a flow of payments, not a single payment. Also, Medicare premiums are deducted from Social Security benefits, so much of the pain is indirect.

On the other hand, with the costs of health insurance and health care rising faster than the Consumer Price Index and possible cuts in Social Security looming—and with advised clients most likely to be among the 8% of high-income Americans who will pay the IRMAA—knowledge of post-65 health care costs and how best to finance them could well be a value-add for advisers.

One way to prepare for lower Social Security benefits would be to pre-fund the gap left by the potential cuts, which HealthView expects to range from 17% to 22%, depending on each retiree’s current benefits, according to a July 2026 HealthView white paper, “Social Security Solvency & Retirement Planning: Calculating Lost Benefits and Income Solutions.”

“Assuming a 6% annual rate of return, an average-earning couple would [at age 54] need to put aside an additional $52,000 to $55,000 today to generate annual withdrawals sufficient to make up for a 17% decline in Social Security benefits. A high-income couple will require between $123,000 and $130,000,” the paper said.

Health care expenses in retirement vary with health status, lifestyle habit, income, state of residence and gender, HealthView data shows. The projected costs for an individual or couple with Type 2 diabetes would be significantly lower due to shorter life expectancy.

Women live longer than men but have lower Social Security benefits, so they face a special challenge; added longevity increases their average retirement healthcare costs by about 15%. “When a partner passes away, women from more affluent households potentially face the dual challenges of lower retirement income and higher Medicare premium surcharges based on MAGI,” the report said

RIJ’s takeaway: Illness during retirement and outliving one’s savings pose financial adversities that may or may not occur, depending largely on how long one lives. Given their high costs and uncertain occurrence, these are the precisely types of risk that most people—all but the wealthiest—can finance most efficiently with insurance—especially mandatory social insurance, which spreads those risks across the largest possible populations.

That’s the rationale for Social Security and Medicare, and why most Americans are grateful for them. Investments are about taking financial risk to accumulate wealth. Insurance is about offloading financial risk to preserve wealth. Each plays an important role in retirement income planning.

© 2026 RIJ Publishing LLC.

Group 1001’s ‘affiliated transactions’ spark federal investigation

The news broke last month that the U.S. Department of Justice and Securities and Exchange Commission officials have been investigating two life insurers controlled by Mark Walter, the billionaire owner of the world champion L.A. Dodgers, CEO of $362 billion asset manager Guggenheim Partners, and chair of TWG Global and Group 1001, an insurance holding company that includes Delaware Life Insurance Co.

In its first quarter statutory filing, released June 26, Delaware Life—which sold more than $10 billion worth of fixed deferred annuities in 2025, according to LIMRA—and Clear Spring Life and Annuity Co. (formerly Guggenheim Life and Annuity), both units of Walter’s holding company, Group 1001 (formerly Delaware Life Holding), a unit of TWG Global, disclosed that:

In February 2026, the Company and its affiliate, Clear Spring Life and Annuity Company (CSLAC), received grand jury subpoenas in connection with an investigation being conducted by the U.S. Attorney’s Office for the Southern District of New York; the U.S. Securities and Exchange Commission is conducting a parallel investigation (collectively, the Investigation). The Company is cooperating with the Investigation.

The Company understands that the Investigation is focused on whether certain private credit investments introduced to the Company and CSLAC by an affiliate should have been treated as affiliated or related-party transactions. Subsequent to receiving the subpoenas, the Company initiated an internal investigation to review its affiliated and related-party disclosures.

Through the internal investigation, errors were identified relating to the identification and presentation of certain related-party investments as presented in the Company’s 2025 Annual Statement. Specifically, certain private credit investments were identified as being predominantly contingent on the performance of related parties.

Group 1001 owns both alternative asset managers that run private credit businesses and annuity-issuing life insurers whose reserves help fund the private credit businesses. Such “affiliated” investments must be reported, since investors might find them conflicted and a hidden source of concentrated risk.

According to a Bloomberg report, the DOJ and SEC subpoenas “prompted Delaware Life and Clear Spring to run their own internal reviews, which turned up what the companies described as errors in prior financial reporting. The restatement was significant: Delaware Life had previously told regulators that roughly 3% of its investments, about $1.4 billion, involved related parties connected to Walter’s other businesses. The corrected figure came in at more than $17 billion, or at least 39% of total invested assets, as of the most recent year-end. An earlier related-party total, as of December 2024, ran to more than $11 billion.”

Three ratings agencies, SPGlobal, AM Best and Fitch, subsequently downgraded the outlook for the Group1001 insurers.

Lincoln Financial announces deals with Bain Capital and Fortitude Re

Lincoln Financial’s announcements of its second quarter 2026 net income and of its deals with Bain Capital, Talcott Financial, and Fortitude Reinsurance sent the share price of Lincoln National Corp. (NYSE: LNC) up 11% last Thursday, to $46.18.

Lincoln will be getting unprofitable business off its balance sheet, investing in more profitable “spread” businesses, and hiring Bain Capital to manage its investments in alternative assets. Lincoln reported net income available to stockholders of $1.32 billion in the second quarter, up from $688 million in the same period a year earlier.

In its second quarter earnings call, Lincoln said it has entered into a $5.8 billion reinsurance transaction to cede a block of in-force guaranteed universal life policies to a subsidiary of Talcott Financial Group, according to AM Best’s BestWire. Chief Financial Officer Christopher Neczypor expects the deal to close in the fourth quarter.

The deal will further reduce Lincoln’s exposure to a capital-intensive block of business. To date, the company has reinsured approximately 60% of its total in-force GUL.

The deal will be funded with part of the $825 million that alternative investment firm Bain Capital paid last year for a 9.9% equity stake in Lincoln. For its part, Lincoln committed $1.4 billion in assets for Bain to manage. Neczypor said that amount will grow to at least $20 billion by the sixth year after the close.

The non-exclusive asset management agreement will include private and structured credit, residential mortgage loans and private equity, among other classes, he said. Proceeds from the deal will be used to fund Lincoln’s growth in spread-based businesses, Neczypor said.

On the reinsurance leg of the overall strategy, in May Fortitude Reinsurance Co. Ltd. announced a $28 billion agreement to reinsure “a significant portion” of Lincoln’s universal life insurance and fixed annuity business. Lincoln will continued to service and administer the reinsured policies.

“The deal is structured partly as coinsurance with funds withheld and partly as a modified coinsurance transaction with counterparty protections including over-collateralization and investment guidelines aligning with its risk-management framework,” Lincoln said.

The transaction will represent an “all-in” statutory capital impact of approximately $200 million and reduce Lincoln’s risk-based capital ratio by approximately 10 percentage points, it said. It will result in a $30-40 million increase in annual subsidy remittances over the medium term.

In the Talcott deal, the statutory reserves to be transferred account for about 37% of Lincoln’s remaining in-force GUL block, the company said. Lincoln will also reinsure approximately $500 million of funding agreement business with a Talcott subsidiary.

Lincoln reported total annuity sales in the second quarter of $3.5 billion, down 13% from a year earlier. Spread-based products accounting for 63% of that total, Lincoln said in an earnings announcement. The segment reported a record-high in ending account balances, net of reinsurance, of $182 billion, up nearly 9% on a yearly basis, the company said.

Underwriting entities of Lincoln National Corp. currently have Best’s Financial Strength Ratings of A (Excellent).

Venerable to manage Guardian variable annuity assets

The Guardian Life Insurance Company of America has agreed to move ~$4.5bn in separate account assets in Guardian’s variable products trust to mutual funds advised by SunAmerica Asset Management, LLC (SAAM), according to SAAM’s parent, Venerable Holdings, Inc.

The deal is anticipated to close in late 2026, pending approvals. Venerable and SAAM, which Venerable acquired in 2026, manage the mutual funds underlying the variable annuity businesses of Venerable Insurance and Annuity Company and Corebridge.

An investor group led by affiliates of Apollo Global Management, Inc., Athene Holding Ltd., Crestview Partners, and Reverence Capital Partners created Venerable in 2023.

“The included funds will become a variable insurance mutual fund trust managed by SAAM through a series of fund mergers. The parties expected the arrangement to enhance scale and growth potential while continuing the investment strategies,” according to the release.

The private company owns and manages legacy variable annuity business, including variable annuities acquired from other entities. It has operations in West Chester, PA, Des Moines, IA, Houston, TX, and New York, NY.

© 2026 RIJ Publishing LLC.

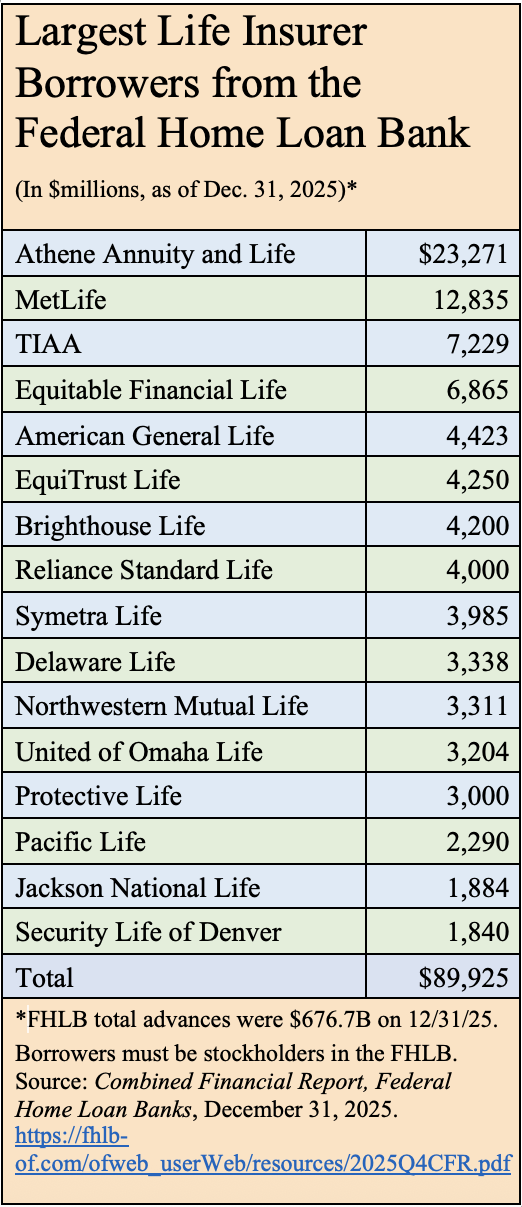
Annuity issuers borrowed $153B from FHLBs in 2025: AM Best

U.S. life/annuity insurers’ borrowings from the Federal Home Loan Banks (FHLBs) slowed in 2025, but still grew by 10% year-over-year, driven predominantly by funding agreements, according to a recent AM Best report.

The Best’s Special Report, “Funding Agreements Drive FHLB Borrowings for the L/A Industry in 2025,” states that borrowings in the form of funding agreements totaled $153 billion in 2025, compared with $136 billion in the previous year, as annuity writers have been able to leverage the lower cost of borrowing from the FHLBs and gain a favorable spread on investments. Although the FHLBs provide an inexpensive short-term financing option potentially used to increase investment income, an insurer may be exposed to credit risk, collateral risk and market risk.

The FHLBs are a system of 11 regionally based government-sponsored banks providing liquidity to financial institutions to promote housing and community initiatives. Insurers can gain access to the FHLB if they engage in mortgage lending and purchase FHLB stock and must post collateral to receive advances.

According to the report, borrowing capacity grew at a faster rate than borrowings in 2025, increasing by 18%, again heavily driven by annuity writers.

“Borrowing capacity is still broadly available, although it is somewhat more limited than in 2019, before the more recent annuity sales boom amid private capital heavily entering the life/annuity industry,” said Jason Hopper, associate director, Industry Research and Analytics. “Two-thirds of companies used less than half its available capacity in 2025, which is up from 62% in 2019; however, a notably higher share of companies have outstanding borrowings today as compared with 2019.”

Other takeaways in the report include:

  • Favorable crediting rates have led to a surge in deposit-type contracts by insurers, including guaranteed investment contracts (GICs). While the amount of FHLB funding agreements reported as GICs and as premium or other deposit funds rose notably over the last two years, the share of the total balance has hovered steadily around 22% for the industry in aggregate.
  • Since FHLB funding agreement borrowers are predominantly companies that sell annuities and spread-play business, the investment profile of these borrowers closely mirrors that of the individual annuity composite in asset classes such as private placements and affiliated and high-risk investments, as well as bond yields.

Cayman regulator aims for ‘jurisdictional maturation’

The Cayman Islands Monetary Authority (CIMA) issued a Thematic Review of Reinsurance Companies last month, finding that corporate governance accounts for 68% of all weaknesses identified across the Class B(iii) and Class D reinsurers examined.

While Bermuda is still the main reinsurance domicile for life/annuity companies, Cayman’s reinsurance industry has expanded to an institutional level, with 114 reinsurers, around US$30 billion in premiums, and US$102 billion in assets.

The review covered both life/annuity and P&C reinsurers holding these license classes, but the governance findings are “particularly material for commercial platforms with billion-dollar balance sheets,” according to one assessment by Walkers, a legal, compliance, and fiduciary firm.

“Cayman is aligning its governance expectations with the institutional standards that cedants, their US state regulators, rating agencies, and other key stakeholders already expect from major reinsurers,” Walkers attorneys wrote. “As the industry grows, supervisory standards are evolving accordingly.

“Jurisdictions with significant reinsurance markets that are reviewed by the IAIS already adhere to these governance standards; similarly, all Cayman platforms serving the same cedants must meet these expectations. This is a sign of jurisdictional maturation and a call to action to strengthen documentation, processes, and service-delivery frameworks across the industry.”

Apollo caps withdrawals from private credit fund

Apollo Global Management Inc. is again limiting withdrawal requests from its largest non-traded private credit fund for retail investors, as broader concerns about the asset class persist, Bloomberg reported.

Apollo Debt Solutions, which has roughly $25 billion in assets, capped withdrawals at 5% of outstanding shares on Monday after investors asked to redeem 16.8%, according to a shareholder letter. Redemption requests in the quarter were higher than the 11.2% investors wanted to pull in the prior period.

The fund reported that it has generated an 8.1% total net return since it was launched.

Apollo is the latest alternative asset manager to cap investor withdrawals for the second quarter running as concerns over private credit’s exposure to software firms and the potential for AI disruption rumble on.

Apollo President Jim Zelter said in May that redemptions from BDCs are likely to continue for the next two quarters following a turbulent first quarter for the sector, and that such requests could even increase.

‘Sidecars’: A source of funds and fees for Bermuda Triangle players

Strong U.S. annuity sales has led to increased formations of sidecars, with total ceded reserves to sidecars or entities engaged in sidecar-like activity increased to more than $90 billion in 2025 from $55 billion in 2023, according to a new AM Best report.

“The vast majority of reserves ceded are covering liabilities for indexed and fixed annuities,” said Best’s Special Report, “Big Year of Growth for Life/Annuity Sidecar-Like Activity in 2025.”

The formation of reinsurance sidecars has been confined generally to private equity/asset manager-backed insurers or insurers with investment management subsidiaries, the report’s author said. These sidecars can earn fees for the contributing owners, providing additional revenue streams for diversification.

“Individual annuities have experienced significant growth amid rising interest rates over the last few years, which has created space for additional capital to enter the reinsurance market and provide capacity as annuity writers aim to manage growth and maintain adequate capitalization. “As a result of managing strong premium growth through reinsurance, the individual annuity composite has steadily seen its reinsurance leverage double since 2019. In addition, overall surplus relief of nearly 11% in 2025 was double that of the previous year.”

“Sidecars… have become more pronounced in the life/annuity industry since 2021,” said Jason Hopper, associate director, Industry Research and Analytics, AM Best, adding that “reinsuring a block of fixed-indexed annuities to a sidecar… could go on for decades.” By contrast property/casualty sidecars have finite lives funding short-term risks with liquid assets.

The report also said:

  • Sidecars currently account for a range from low single digits up to over three-quarters of ceded reserves (i.e., reserve credit taken plus modified reinsurance reserves) by the ceding company, signaling more counterparty concentration at some companies.
  • Companies ceding reserves to sidecars have an outsized share of funds withheld in coinsurance compared with the industry aggregate. While sidecars account for approximately 4% of the industry reserve credit taken at primary insurers, they account for 10% of funds withheld.

Sixth Street invests in Monument Re

Investment firm Sixth Street has agreed to acquire a majority stake in Monument Re, a life insurer and reinsurer that acquires and manages in‑force life insurance portfolios in Europe. Hannover Re will remain a shareholder and reinsurance partner in Monument Re.

Sixth Street Insurance said it advises on more than $125 billion in insurance company assets.

Investment vehicles that Sixth Street manages or advises will acquire the stake, the release said.  Monument Re will gain capital and resources to accelerate its business plans and continue to operate as a standalone company. The transaction is expected to close by year-end. Hannover Re said it will remain a reinsurance partner and shareholder.

The combined market presence and experience of Sixth Street and Hannover Re positions Monument Re for ongoing growth, Monument Re Group CEO Carlo Elsinghorst said in a statement.

Last year, Monument Re transferred a €1.4 billion ($1.56 billion) legacy reinsurance portfolio to RGA Americas Reinsurance Co. Ltd., to focus on European life insurance consolidation. It said the portfolio was comprised of annuity and other life insurance liabilities it acquired in a 2020 Greycastle Holdings Ltd. Transaction.

  • © 2026 RIJ Publishing LLC. All rights reserved.

Major financial firms partner on public/private model portfolios

Morningstar’s Morningstar Wealth division is partnering with Apollo Global Management, Franklin Templeton and J.P. Morgan Asset Management to create research-backed model portfolios that combine both private and public market assets for retail investors and their advisors.

“Morningstar Public/Private Select Series” will combine:

  • Morningstar Wealth’s asset allocation, manager research, and due diligence capabilities
  • Public market strategies from Franklin Templeton and J.P. Morgan Asset Management
  • Private market strategies (including private credit and real estate) from Apollo and Franklin Templeton

Morningstar Wealth is a group within Morningstar Investment Management LLC, a registered investment adviser, which offers advisors investment strategies such as model portfolios and separately managed accounts (SMAs). The group has $370 billion in assets under management.

The portfolios will be constructed with ETFs and interval funds to make private markets usable in individual investor portfolios, offering:

  • Six risk-based portfolios, ranging from capital preservation to aggressive growth
  • Public and private exposures integrated into a single asset allocation
  • Transparent, competitive pricing, including no overlay fees
  • Accessible minimums, expanding access beyond traditional institutional investors

“By packaging private market exposure within a diversified model, Morningstar Wealth aims to remove the burden of sourcing, sizing, and managing liquidity, allowing advisors to focus on client needs rather than portfolio construction,” a Morningstar release said.

“The initial models will include exposure to private credit and real estate through interval funds ranging approximately between 12–20% of the models’ allocation, depending on risk profile and current market opportunity.”

Private markets have historically been limited to institutional investors and ultra-high-net-worth individuals. At the same time, industry demand continues to grow, with advisors increasingly seeking to incorporate private markets into mainstream portfolios.

Pacific Life and Principal Add Payout Options to 401(k)s

Retirement plan sponsors, if they decide to bundle an annuity-linked income distribution tool into their default investment offerings (usually target-date funds or trusts), must also decide what type of annuity they want to offer plan participants. With the SECURE Acts, Congress encouraged deferred annuities in 401(k) plans without championing any particular make or model.

There are a growing number of them on the market. While all of the proposed annuities help participants convert part of their accumulated savings into a monthly incoming at some point during retirement, and they all (by law) allow participants to liquidate their annuities if they leave their plans, they differ in their pre-retirement crediting mechanisms, their flexibility for the owners, and in the scope of their guarantees.

Two major retirement plan providers just announced new or refreshed income options. Pacific Life has a deferred income annuity purchased incrementally in advance of retirement. Principal Financial offers either a choice between a group annuity that wraps a lifetime withdrawal benefit wrapper around participant accounts and a fixed indexed annuity with an aspirational payout rate.

  • Principal LifeTime Income Builder Index, a QDIA-eligible option with a growth-oriented, passively invested TDF portfolio. The portfolio begins allocating to a fixed indexed annuity (FIA) about age 47 and automatically transitions to distributing 6% income at around age 65.
  • Principal is also adding third-party retirement income TDF series through new strategic partnerships with TIAA/Nuveen, the LifeCycle Income Index (The trustee for the NLI CIT series is SEI Trust Company) and Income America 5forLife.

[Pacific Life’s and Principal’s 401(k) annuities can be located on this “401(k) Lifetime Income Solutions Map.” It’s available at the Defined Contribution Institutional Investment Association’s Resource Library.]

The six percent payout is the targeted but not guaranteed percentage for a single life payout. Three-fourths (4.5%) of the six percent is designed to come from the FIA and the rest from the fund’s other assets until those assets are exhausted, a Principal release said. Participants who save in Income America’s 5forLife can receive a guaranteed minimum annual withdrawal benefit (GMWB) of 5% of the value of their savings at age 65 for the rest of their lives, even if their own money runs out. As with all GMWB riders, retirees can dip into their savings but would see a reduction in monthly income.

Principal’s retirement business serves more than 13 million participants at more than 46,000 plans.

Income Horizon from Pacific Life

Pacific Life has launched Income Horizon, a collective investment trust (CIT) series with an embedded deferred income annuity “designed to help defined contribution (DC) plan participants accumulate guaranteed lifetime income” before retirement, according to a release.

A subsidiary of Broadridge Financial Solutions, Matrix Trust Company, will serve as the discretionary trustee and provide CIT governance, fiduciary oversight, and operational infrastructure, the release said.

“Unlike approaches that rely on estimates of future income, Income Horizon uses clearly defined income units that represent a specific amount of guaranteed lifetime income,” the release said. “These units help provide participants with greater clarity around their accumulated income, empowering individuals to plan for retirement with enhanced precision.”

Income Horizon is a Group Annuity Contract issued to an Income Horizon Collective Investment Trust (CIT) by Pacific Life Insurance Company, which is licensed to issue insurance products in all states except New York.

According to Pacific Life’s website, “Income Horizon is an in-plan deferred income solution delivered through a Collective Investment Trust (CIT) structure. Beginning at age 50, a portion of participant deferrals may be automatically allocated to build guaranteed lifetime income directly within the plan.” Participants gradually accumulate units of lifetime income, worth $1 of income per unit assuming a single-life payout starting at age 70. The cost per unit would apparently fluctuate over time, depending on such variables as current interest rates and the participant’s age.

The Income Horizon CIT series is available through the National Securities Clearing Corporation (NSCC). Pacific Life and Broadridge Financial Solutions are not affiliated.

Retirement Income News

Empower to buy Milliman’s retirement businesses

Empower, one of the country’s largest full-service retirement plan providers, has agreed to buy the defined benefit plan administration of Milliman, Inc., for $340 million. Milliman is retaining its actuarial consulting business in the health and retirement space and expects to partner with Empower after the sale

The transaction is expected to close in the second half of 2026, subject to customary regulatory approvals and closing conditions. Until the transaction closes, Empower and Milliman’s administration business will continue to operate as independent businesses.

Empower’s legal counsel is Eversheds Sutherland. Milliman’s legal counsel is K&L Gates and Chesky Partners is its financial advisor.

The deal gives Empower roughly:

  • 400 defined benefit plans representing approximately 790,000 plan participants and approximately $80 billion in assets under administration.
  • 1,100 defined contribution plans representing approximately 750,000 participants and more than $50 billion in client assets.¹
  • 100 health and welfare administration clients with approximately 100,000 plan participants.

Empower manages approximately $1.8 trillion in assets under administration (AUA) and serves ~20 million participants in 93,000 employer-sponsored retirement plans. In 2024, the 1,000 advisors in its Personal Wealth division managed about $86 billion in individual accounts.

Over the past decade, Empower,  has expanded its capabilities through strategic acquisitions, including Personal Capital, MassMutual’s retirement business, Prudential’s full-service retirement business and Plan Management Corp. (OptionTrax). Since 2020, Empower has doubled both its assets and customer base, reflecting rapid growth through acquisitions and organic expansion.

Two former Fidelity senior executives, Robert Reynolds and Edmund Murphy, have been instrumental in building Empower into a top-three full-service retirement plan provider. A former vice chairman at Fidelity and later CEO at Putnam Investments, Reynolds became president and CEO of Great-West Financial in 2014.

That year, Great-West rebranded its retirement services business as “Empower,” integrating Great-West’s retirement operations, J.P. Morgan Retirement Plan Services, and Putnam’s retirement business. In 2019, Reynolds became chairman of Great-West Lifeco and Murphy succeeded him as CEO of Empower.

Post-transaction, Milliman and Empower expect to establish “a strategic relationship for actuarial services and defined benefit plan administration.” The two firms would become preferred service providers in “select actuarial services and defined benefit administrative opportunities generated by each firm’s respective business activities,” a release said.

Ford offer Hueler’s Income Solutions platform as 401(k) decumulation option

Ford Motor Company employees and 401(k) participants in the U.S. can now convert part of Ford 401(k) into a lifetime annuity through Hueler’s Income Solutions platform. The service was launched at Ford in January.

Ford joins General Motors, Boeing, and other large companies that partner with Hueler on its marketplace for immediate and deferred income annuities.

Ford plan participants can use the platform to solicit and compare annuity quotes from multiple insurance providers. They can model lifetime income payments in real-time, and personalize features to fit their needs, a Hueler release said.

An annuity is a long-term contract between an individual and an insurance company. In exchange for part of the individual’s retirement savings, the insurance company provides monthly payments that are guaranteed for life or for a set number of years, creating a steady, predictable income stream. Annuities can also be structured to provide continued income to a survivor, like a spouse or partner.

“The partnership with Hueler gives Ford employees the power to choose what’s right for them, including how much of their savings to use, with no minimum amount required,” Hueler said.

U.S. Treasury selects two BlackRock funds for Trump Accounts

The U.S. Treasury today announced that Two BlackRock iShares exchange traded funds (ETFs) will be offered among the investment options available under Trump Accounts, the U.S. Treasury announced this week.

Trump Accounts are “a federal initiative designed to enable a generation of American children to begin building wealth from birth,” the announcement said

BlackRock’s iShares Core S&P 500 ETF (IVV) and iShares Core S&P Total U.S. Stock Market ETF (ITOT) offer diversified exposure to many of America’s leading companies and the long-term growth potential of the U.S. economy. With expense ratios of 0.03%, both funds reflect BlackRock’s longstanding commitment to making investing more affordable.

In March, the BlackRock Foundation announced a $1 million grant to Invest America to support public service campaigns focused on awareness, education, and enrollment in Trump Accounts. The Foundation has also supported children’s savings initiatives, including a $3.75 million grant to NYC Kids RISE and a $1.15 million grant to establish The Early Wealth Partnership, which promotes engagement with CalKids, California’s statewide children’s savings account program.

In December, BlackRock committed to matching the federal government’s $1,000 contribution to Trump Accounts for eligible U.S. employees, helping families begin investing for the future from an early age.

The selected iShares ETFs are expected to become available through the program in the coming months following the official launch of Trump Accounts. To learn more, and to download the app and sign up for a Trump Account, visit www.trumpaccounts.gov.

Security Benefit launches short-surrender period FIA

Security Benefit has introduced its Blueprint Fixed Index Annuity (FIA). The product, positioned as an alternative to CDs, Treasury bonds, and money market funds, offers three-year and five-year surrender charge period options, multiple crediting strategies, and optional index account guaranteed caps and fixed account rates.

“Blueprint is one of the industry’s only FIAs offering Guarantee Period Fixed Account rates and index account caps on a three-year surrender charge period, helping to eliminate renewal rate concerns,” said Doug Wolff, Security Benefit’s CEO, in a release.

“Advisors can create accumulation strategies around a floor (no market loss) and ceiling (rates and caps) with the flexibility of short time horizons so they can adjust client plans as market conditions or financial needs change.”

Blueprint Annuity uses Zinnia’s insurance technology platform, which includes Zahara, a contract administration system, and Zinnia Live, a digital engagement layer.

Options include:

  • Fixed accounts offering one-year and guarantee period fixed account (three or five years) for guaranteed growth.
  • Three index accounts with caps (max credits) and trigger rates (with index moves of 0% or more) based on part of the change in the S&P 500, which covers 80% of the U.S. stock market.
    • 1-yr Annual Point to Point based on S&P 500 w/Cap
    • 1-yr Annual Point to Point based on S&P 500 w/Trigger Rate
    • Guarantee Period Annual Point to Point w/Cap (3 or 5 years)

Prosperity FIA has 10-year and 14-year surrender periods

Prosperity Life Group today announced the launch of Prosperity PathWay Series Fixed Indexed Annuities (FIAs), issued by S.USA Life Insurance Company, Inc. (S.USA), a Prosperity Life Group company.

Prosperity PathWay Series includes two FIAs that combine growth opportunity, protected lifetime income, and allocation flexibility while helping protect from market downturns:

  • Prosperity PathWay | FIA
  • Prosperity PathWay Max | FIA with a Premium Bonus*

The series is designed to “help simplify retirement income planning conversations” by giving clients a choice of three Preset Allocation Options (either growth, balanced or conservative), with each option combining multiple index strategies.

Contract owners can use index-linked strategies and/or a fixed interest account.

The FIA series includes three guaranteed lifetime withdrawal benefit (GLWB) income options offering:

  • Earlier retirement income
  • Future income growth potential
  • Long-term income growth opportunities

There is one income option with no explicit rider fee.

Prosperity FIA/GLWB PathWay Series includes 10-year and 14-year withdrawal charge period options and offers annual penalty-free withdrawals beginning in contract year two.

Prosperity Life Group offers life and annuity insurance, reinsurance, and capital solutions.

Affiliated companies include underwriting companies SBLI USA Life Insurance Company, Inc., S.USA Life Insurance Company, Inc., Shenandoah Life Insurance Company, and National Western Life Insurance Company.

New ERISA fiduciary violation case filed in Virginia

A $28 million class-action lawsuit filed in a Virginia federal court charges that Parsons Financial Corporation and its fiduciaries kept a Nuveen large-cap blend fund in its retirement plan’s investment line-up despite chronic underperformance, in violation of the Employee Retirement Income Security Act of 1974 (ERISA).

The complaint, filed in U.S. District Court, Eastern District of Virginia, by the law firm Sanford Heisler Sharp McKnight, alleges that the Nuveen Dividend Growth Fund lagged behind its  benchmark, the S&P 500, and experienced significant outflows of cash.

Between 2012 and 2020, according to the complaint, the fund underperformed the S&P 500 by >46% (194.20% v. 147.44%), costing the plan ~$18,200,000. From 2020 to 2025, the fund lagged the S&P 500 by more than >37 percentage points, resulting in a plan loss of $28 million.

In 2025, Sanford et al obtained final approval of a record $69 million settlement in its multi-year class action against UnitedHealth Group. In 2024, the firm and co-counsel obtained final approval of a $61 million settlement in a long-running ERISA class action against General Electric.


© 2026 RIJ Publishing LLC.

Caution: Children Might Impoverish Their Parents

I’ve heard a lot of recommendations about solving the Social Security funding problem. We’re apparently stuck on the tax vs. benefits issue. Democrats reject benefit cuts. Republicans reject tax increases. President Trump has prioritized tariffs, tax cuts, deportation, oil and war over Social Security.

A regrettable part of the debate has been the pitting of ‘generations’ against each other. We’re told that the debt-laden young are being asked to take on the added burden of paying benefits to wealthy old people. This accusation seems odd to me. Young people are just future old people. There is no dividing line between generations. Is it a good idea for workers to cut their own future Social Security benefits to avoid a higher payroll tax today?

If they do choose to cut their future benefits, only some will have the capacity or motivation to make up the difference with personal savings. I don’t have precise numbers, but given the fees and volatility of investing—and the frequent need by middle-class workers to use long-term savings for big expenses—workers will need to save more in stocks and bonds, on average, than they do on payroll taxes in order to receive the amount of lifetime income they will be guaranteed by Social Security.

The financial industry will create illustrations showing that you can accumulate more in stocks and bonds (and private market assets) than by contributing to Social Security. That might happen; but only if you can afford never to touch your savings. Most Americans won’t be in that position.

There are many creative ways to scare the public with long-term projections. Imagine an economist in 1964 predicting that it would cost the 76 million Baby Boomers tens of trillions of dollars to feed, clothe, shelter, and educate their anticipated children. Someone might have added a warning that those millions of unborn Americans would rob their parents of decent lifestyles. Clearly, those trillions didn’t exist in the 1964 economy. But the children, and the money, appeared. (Spoiler: A chunk of that money is our national debt.)

The argument that Boomers are now a deca-trillion-dollar liability for their own children and grandchildren is just as ridiculous. Boomers have more money than younger people because they saved and invested in the economy. For decades, they even lightened the nation’s tax bill by over-paying into the Social Security trust fund. They’ll hand off trillions of dollars in assets to their children and charities.

Neither Social Security, or taxes generally, are zero-sum games between rich and poor or young and old. The big-picture problem is our shrinking homegrown population, which could lead to a smaller domestic economy, less output, and deflating asset values. Social Security’s financing dilemma is a symptom, not a cause, of that problem. An economist might even be able to demonstrate that consumer spending by Social Security beneficiaries will carry us through the looming demographic choke point. Stoking generational antagonism won’t help.

© 2026 RIJ Publishing LLC. All rights reserved.

Research Roundup

Here are two papers on private credit, one on the suitability of target-date funds for low-income workers, one on the money-creating power of the Federal Reserve, and one that blames financial crises not, as Hamlet said, on our stars but on ourselves. Most of the papers can be found through a search by WP number at the National Bureau of Economic Research website.

“Why is Private Lending so Popular?” by David T Robinson and Melanie Wallskog. NBER Working Paper No. 34617.

“Private lending has exploded over the past two decades. To explore its rise, we focus on Business Development Companies (BDCs),” write these Duke University professors. “We show that their growth is intimately connected to growth in private equity. Many BDCs are directly connected to large private equity organizations, and their compensation structures mirror those in private equity.

“Private credit—lending to risky companies—and private equity—ownership of risky startups—appear to be different private markets businesses. But they meet or overlap in the world of Business Development Companies, or BDCs. Publicly-traded, BDCs not only provide debt for PE-sponsored deals, but also make PE-like investments themselves involving deferred interest, preferred equity, and exposure to underlying assets. Their growth is intimately connected to growth in private equity.

“We find that around 70% of the overall growth in the market has been from larger, PE-affiliated BDCs who appear primarily to support PE-sponsored transactions. Thus, providing debt to LBOs likely accounts for a majority of the overall rise in private lending’s popularity. Among non 4PE-affiliated BDCs, we find that the bulk of the recent growth in AUM occurs in BDCs with more complex investment portfolios. In other words, both ‘PE channels’ contribute significantly to the rising popularity of BDCs.”

“Private Credit, Balance Sheets and Financial Stability,” by Gregor Matvos, Tomasz Piskorski, and Amit Seru. NBER Working Paper No. 34991.

In this industry-supported research paper, authors Gregor Matvos and Amit Seru of Stanford and Tomasz Piskorski of Columbia argue that “private credit funds appear conservatively structured and unlikely to pose systemic risks comparable to traditional banks under their current balance-sheet configurations.”

Using comprehensive fund- and asset-level data covering most of the industry, the authors show  that “private credit funds are highly capitalized, with equity typically accounting for 65–80% of total assets—more than six times the capitalization of U.S. banks, where equity represents about 10%.

According to the paper, “Performance data show positive average net annualized returns with limited downside risk to creditors, as losses are largely borne by equity investors. Overall, private credit funds appear conservatively structured and unlikely to pose systemic risks comparable to traditional banks under their current balance-sheet configurations.

“Debt usage is moderate and largely reflects bank credit lines used for liquidity management. Fund lives average 10–12 years, while underlying loan maturities are generally shorter, implying little or no maturity mismatch—unlike banks, which fund long-term assets with short-term callable deposits. Private credit portfolios are diversified across industries, geographies, and credit strategies, reducing exposure to correlated shocks.”

The authors warn however that “potential vulnerabilities… could emerge as the sector grows, including governance and disclosure frictions, stress-period dynamics, bank–nonbank linkages, and the transmission of losses through limited partner balance sheets and retail investment vehicles.”

“Life Cycle Portfolio Choice with Human Capital and Social Security,” by Jason Scott, John B. Shoven, Sita Slavov, and John G. Watson. NBER Working Paper No. 34966.

“Target date funds – which initially invest a large share of retirement savings in stocks and shift gradually towards bonds over the life cycle – are designed to provide a ‘one-stop shop’ for retirement investing. The rationale for this pattern is that human capital, which is highest at the start of a worker’s career, is ‘bond-like,’” write these authors in the abstract of their research.

“Thus, utility is maximized when financial wealth is initially invested primarily in stocks, with the investment mix shifting towards bonds as the present value of future labor income declines. We revisit this logic in a dynamic model in which shocks to labor income are correlated with the stock market, and in which Social Security replaces a higher share of income for lower-income individuals.

“In line with empirical evidence, lower-income individuals in the model experience a higher degree of correlation between labor earnings growth and stock returns. We find that utility-maximizing retirement portfolios can vary greatly across individuals, deviating substantially from the pattern of a target date fund for lower-income individuals.”

“The Effect of Annuities on Longevity,” by Borja Larrain, Alessandro Previtero, and Felipe Severino. NBER Working Paper No. 35082.

This survey of the lives of 600,000 Chilean retirees from 2004 to 2022 shows that “the decision to annuitize—instrumented by recent market returns—substantially reduces mortality at five- and ten-year horizons. Further analyses indicate that annuities reduce mortality by shielding retirees from income volatility and investment-related stress. Complementary survey evidence suggests that annuitants invest more in health and report lower disability rates.

“Annuities can affect longevity through several interconnected channels. Annuities provide a stable source of lifetime income, reducing the likelihood that retirees face liquidity constraints. They also shield retirees from income uncertainty and anxiety associated with adverse financial market movements. Higher earnings and lower earnings volatility can increase both immediate and long-term longevity, consistent with evidence on job displacements in Sullivan and von Wachter (2009a,b).

“Similarly, stock market fluctuations can lead to stress, diminished mental health, and ultimately higher short-term mortality (Engelberg and Parsons 2016, Schwandt 2018). Finally, life-contingent payments from annuities can promote health investments (Philipson and Becker 1998), thereby improving health later in life and reducing mortality.”

“Democratic Sovereignty and the Prerogative to Make Money: The Case of the Federal Reserve,” by Christine Desan, Harvard Law School.

Desan is a Harvard Law School professor who has written about money’s role in society. In a new monograph, she examines, through her specialized lens, the ongoing power struggle between advocates of an all-powerful “unitary presidency” and those who believe that the Constitution dictates a “separation of powers” where the executive, legislative and judicial branches “check” each other’s over-reach.

The author of “Making Money: Coin, Currency, and the Coming of Capitalism” (Oxford, 2015), Desan sides with the latter. She argues that, while the Fed isn’t a branch of government, independence from the president was part of its founding purpose.

The constitutional conclusion follows: Congress’s prerogative over money-making clearly secures the Fed’s independence from presidential interference. That conclusion is lost in current scholarship that treats the Fed as fundamentally like other independent agencies. The Court has assumed, similarly, that the unitary executive presides over a relatively homogeneous regulatory field.

“Congress established the Federal Reserve System to carry out a critical legislative prerogative—making the sovereign money supply,” she writes. “Congress used an institutional form—national banking—innovated precisely to secure sovereign money-making from executive (originally monarchical) interference. Congress in turn assigned a vital responsibility—the capacity to make money out of debt in the people’s name—to the Fed.”

Those words suggest that Desan is a chartalist, or, like adherents to Modern Monetary Theory, on the chartalist spectrum. A chartalist regards money as a “creature of the law, created and regulated by the state to organize economic activity. The more traditional view is that money arose as an efficient substitute for barter and has no value unless tied to a valuable commodity, such as gold or silver.

“The Political Economy of Financial Crises,” by Charles W. Calomiris and Matthew S. Jaremski. NBER Working Paper No. 35101.

“The common narrative… that we are inherently vulnerable to external shocks is wrong. Instability is not a fact of nature,” according to this paper by Charles W. Caloramis of Columbia University and Matthew S. Jaremski of Utah State University

“Financial crises are better seen as a mirror of who we are as a society, reflecting our political structures, vying constituencies, cultural preferences, and blind spots. A proper understanding of financial crises thus forces us to face the awkward truth that the costs that attend financial crises are often self-inflicted.”

The authors show “how policymakers shape financial rules in ways that favor politically-influential groups but result in financial vulnerability. Key mechanisms include restricted bank chartering, safety nets, credit subsidies, and sovereign borrowing. Political forces also shape crisis management. Delayed interventions, selective support, and constrained policy responses can deepen and prolong crises.

“Instead of seeing financial crises as arising from an unavoidable vulnerability to external shocks they are better seen as a mirror of the societies in which they occur, reflecting their political structures, vying constituencies, cultural preferences, and blind spots.”

© 2026 RIJ Publishing LLC.


Cayman Islands seeks ‘qualified jurisdiction status’

The Cayman Islands intends to submit its application to receive Qualified Jurisdiction Status for its reinsurance sector from the National Association of Insurance Commissioners by the end of the second quarter, according to AM Best. The process is driven and managed by the Cayman Islands Monetary Authority and is coordinated in the U.S. with the NAIC.

Receiving the distinction allows insurers to get credit for reinsurance from a non-U.S.-domiciled company, according to NAIC documentation on the process. Another major advantage of receiving Qualified Jurisdiction Status is lower reinsurance collateral requirements, NAIC documents say.

“If granted, QJS would formally recognize the Cayman Islands’ reinsurance regulatory framework within the NAIC process and further align it with U.S. supervisory expectations, reflecting the fact that approximately 90% of the jurisdiction’s business is U.S.-facing,” the Monetary Authority said in an statement.

The Cayman Islands has a CRT-2 country risk rating from  AM Best, with low levels of economic and political risk and moderate levels of financial system risk, according to a Best’s Country Risk Report. The approval timeline can vary due to the need for ongoing engagement throughout the review cycle. QJS status is expected to apply to specific license classes in Cayman, and some of the benefits might not apply automatically.

© 2026 RIJ Publishing LLC.

New private credit analysis tool created by Morningstar

Morningstar Credit Analytics, a subsidiary of Morningstar, Inc., has launched Corporate Credit Analytics, “a new set of tools designed to bring greater transparency and consistency to private credit analysis,” according to a release. Private credit has grown to more than $2.5 trillion in assets but remains structurally opaque, according to PitchBook’s 2025 Annual Global Private Debt Report.

“Institutional investors and regulators have raised concerns about how risk is measured, compared, and communicated,” the release said. “Private credit decisions are still shaped by incomplete and inconsistent information. That makes it harder to compare risk and defend decisions.

“Corporate Credit Analytics replaces public-market comparisons with aggregated private‑company data. Credit teams can now have a common, data-driven, and defensible framework to help evaluate and benchmark borrower performance, from initial underwriting and portfolio surveillance through investment committee and fund investor reporting.”

A standardized framework for private credit analysis

The Corporate Credit Analytics platform brings three tools together to replace fragmented, non-comparable data with consistent, comparable credit analysis:

  • Data Explorer surfaces aggregates of real company financial statements and loan-level data sourced from private company disclosures, rather than public comparables. The data set includes approximately 80 metrics spanning financial statements, debt schedules, covenant thresholds, credit estimates, and key credit ratios including EBITDA to interest expense, debt to EBITDA, cash flow to debt, leverage, and liquidity.
  • Data Overview provides configurable visualizations of trends, ratio distributions, and key performance metrics across private credit rating categories and industries, supporting portfolio insights and effective communication with investment committees and stakeholders.
  • The Credit Estimate Tool generates ratings-aligned credit risk scores for private and limited-disclosure borrowers using methodologies consistent with Morningstar DBRS frameworks. Outputs are mapped to familiar rating categories and benchmarked against aggregated segment statistics by industry, region, and credit quality.
Serving the institutional credit market

Corporate Credit Analytics is designed for institutional users across the private credit ecosystem. That includes direct lenders, portfolio managers, CLO managers and structurers, bank credit teams, debt capital markets professionals, and ratings advisory functions.

Use cases include: underwriting, portfolio construction, fund investor communications, securitization, rating agency engagement, and ongoing surveillance.Users can access data and insights through the Morningstar Credit Analytics platform or via APIs, with upcoming Model Context Protocol (MCP)-enabled connectivity for AI-driven and agentic workflows.

© 2026 RIJ Publishing LLC.

News from the Bermuda Triangle

We try to keep track of moves by life insurers that use all or part of the “Bermuda Triangle” strategy. That’s what we call the strategy where annuity-issuing U.S. life insurers partner with alternative asset managers and affiliated offshore or captive onshore reinsurers, as well as special purpose vehicles—to raise capital, use capital more efficiently, or reduce the risks of capital-intensive legacy businesses.

The largest practitioners of this strategy tend to fall along a continuum, ranging from asset managers that bought into the life/annuity business after 2010 (e.g., Apollo, KKR, Ares, Brookfield) to established publicly-traded or mutual life insurers (e.g., Prudential, MassMutual, Ohio National) and, in between, companies that employ pieces of the strategy without establishing the full vertical integration (deferred annuities, private market assets, and asset-intensive reinsurance) that epitomizes it.

Prismic Life raises $1.9 billion in new capital

Prudential Financial continues to bring third-party institutional money into its Bermuda Triangle strategy, whose key points are Prismic Life, its Bermuda reinsurance holding company, Prudential Global Investment Management (PGIM), its asset manager, and its U.S. life/annuity companies.

In May, Prismic Life raised about $1.9 billion in capital commitments from a global consortium of institutional investors—about $300 million more than its target—for life and annuity reinsurance deals, according to a Prudential release.

“Prismic Life provides Prudential with access to third-party capital and strategic optionality supporting its long-term growth strategy,” said Andy Sullivan, chairman and CEO of Prudential Financial, in the release. Prudential sold a gross $15.3 billion in fixed and variable deferred annuities in 2025, according to LIMRA, the 11th-highest annuity issuer.

According to Prudential Insurance Company of America’s March 31, 2026 statutory filing, the insurer has $331.5 billion in assets, $310.5 in liabilities, and a $15.2 billion surplus. Life insurance sales for the first quarter of 2026 were just over $1.6 billion and annuity sales were just under $1.6 billion.

The life insurance business reported $1.4 billion in reinsurance assumed and $1.6 billion in reinsurance ceded. The annuity business assumed $1.93 billion in reinsurance and ceded just $125.4 million.

“Prismic Life provides Prudential with access to third-party capital and strategic optionality supporting its long-term growth strategy,” said Andy Sullivan, chairman and CEO of Prudential Financial, in the release. Prudential sold a gross $15.3 billion in fixed and variable deferred annuities in 2025, according to LIMRA, the 11th-highest annuity issuer.

Prismic is a joint venture of Prudential Financial and Warburg Pincus. PGIM, Prudential Financial’s $1.4 trillion investment management arm of Prudential Financial, and Warburg Pincus provide Prismic Life’s public and private market asset management.

A Bermuda-exempted limited partnership, Prismic Life is the holding company of two licensed Class E Bermuda-based L/A reinsurers: Prismic Life Reinsurance, Ltd. and Prismic Life Reinsurance International, Ltd.

To date, Prismic has raised more than $3.3 billion in total capital to support the reinsurance of liabilities, including Prudential Financial’s US and Japanese books and third-party business. Prismic Life Reinsurance International covered a yen-denominated in-force block of Daiichi Life whole life and annuity policies, with Daiichi continuing to administer the underlying contracts.

In January 2025, Prudential Financial disclosed a separate reinsurance agreement covering about $7 billion of reserves tied to USD-denominated Japanese whole life policies with a Prismic subsidiary. Daiichi reported total assets of ¥35,364,060 million ($222.79 billion) as of December 31, 2025, with a solvency margin ratio of 831.8%.

In PRUCO Life Insurance Company’s annual 10-K filing with the Securities and Exchange Commission, a number of deals involving reinsurance of its guaranteed universal life (GUL) policies were reported. Effective October 2024, Pruco reinsured a closed block of GUL with Wilton Re. Effective January 2024, Pruco struck a reinsurance agreement with Somerset Re for a GUL closed block. Somerset Re was acquired by Aquarian Holdings in 2023.

Japanese insurance giant commits $19 billion to Barings

Barings, a $481 billion global alternative investment manager, a subsidiary of MassMutual and Japan’s MS&AD, last month announced the close of over $19 billion in committed capital for its Global Direct Lending strategy, garnering interest from a diverse group of institutional, insurance and wealth clients.

The two-year fundraising period coincided with strong and sustained deployment activity, including over $18 billion across 355 transactions globally.

The latest fundraise expands Barings’ more than $67 billion (as of May 15, 2026) Global Private Finance platform, which draws on an “origination network across North America, Europe and Asia-Pacific and a 30-year track record of providing financing solutions to middle market private equity sponsors,” according to a release.

MassMutual is also a key investor in Martello Re Ltd., based in Hamilton, Bermuda. In July 2024, July 23, 2024, Martello Re Limited (“Martello Re”) reported the close of a second round of equity funding, raising $935 million of equity commitments from existing and new shareholders, which exceeds an initial $800 million target set at launch of the capital raise.

In addition, Martello Re has upsized its current credit facility by $360 million, adding four new banks to its lender group. These commitments, when combined with the company’s current equity and credit facility capacity, brings total drawn and undrawn capital at Martello Re to approximately $3.6 billion, providing a strong foundation for continued growth.

Barings is a $481 billion (as of May 15, 2026) global alternative asset manager that partners with institutional, insurance, and wealth clients, and supports leading businesses with flexible financing solutions. The firm, a subsidiary of MassMutual and MS&AD, seeks to deliver excess returns by leveraging its global scale and capabilities across credit, real assets, capital solutions and emerging markets.

MassMutual sells $6 billion block of life insurance to Nationwide

Nationwide Financial is set to add $6 billion in reserves through a reinsurance deal with MassMutual covering a block of fixed universal life insurance policies. The transaction includes more than 30,000 policyowners and has a total face value of nearly $16 billion. It is expected to close in the second quarter of 2026.

In this type of block reinsurance transaction, in contrast to funds-withheld or coinsurance arrangements with affiliated or captive reinsurers, both assets and liabilities associated with the policies move to the reinsurer.

Under the agreement, MassMutual will continue to administer the block of policies. Customer servicing will stay with MassMutual after the transaction closes. Nationwide doesn’t expect to add staff.

Augustar Retirement launches new traditional VA

AuguStar Retirement, which markets variable, fixed index and multi-year guaranteed annuities through banks, brokers/dealers, independent marketing organizations and insurance agents, has expanded its annuity lineup with the launch of StarStream deferred traditional variable annuity. The new product offers four separate income benefits:

  • Level: Designed for predictable lifetime income
  • Protector: Combines lifetime income with an enhanced death benefit
  • Boost: Offers higher withdrawals earlier in retirement
  • Daily: Allows daily step-ups to capture market gains

StarStream supports both near‑ and long‑term income strategies, including opportunities to increase future withdrawal rates when income is deferred. The product provides access to a diversified investment lineup that includes equity, fixed income and a fixed account. When an optional benefit is elected, allocation requirements apply.

AuguStar Retirement is a member of the Constellation family of businesses, which also includes AuguStar Life, AuguStar Seguros, Constellation Investments, Constellation Re and Constellation Institutional Markets. Augustar was previously known as Ohio National. Constellation’s investors and equal partners, CDPQ and Ontario Teachers’, are two of North America’s largest long-term institutional investors, managing CA$796 billion in net assets, including CA$136 billion in private capital investments (as of Dec. 31, 2025).

Constellation Re (Bermuda) Ltd is the Bermuda-based reinsurance arm of Constellation Insurance. The Bermuda entity provides on- and offshore reinsurance services, leveraging the company’s strong capital position, robust credit ratings, and global reach.

In December 2024, the Bermuda Monetary Authority (BMA) registered Constellation Re (Bermuda) Ltd in Class C of the Bermuda insurance classification system. Since 2020, Constellation Re has executed $43 billion in complex M&A and reinsurance transactions across a diversified portfolio of liabilities. Constellation Insurance, which includes Constellation Re, holds strong ratings from A.M. Best (“A”), Fitch (“A”), and Moody’s (“Baa1”).

According to Constellation Insurance’s website, the company established the Bermuda entity to expand its reinsurance business and diversify its insurance and financial services group and to take advantage of Bermuda’s favorable regulatory environment and established reinsurance market.

26North Re buys Independent Insurance Group

26North Reinsurance Holding Company has entered into a definitive agreement to acquire 100% of Independent Insurance Group, LLC (“Independent Group”), which operates Independent Life Insurance Company (“Independent Life”), the only carrier exclusively dedicated to issuing structured settlement annuities for personal injury claimants and their families.

The acquisition marks 26North Re’s entry into the U.S. insurance market and establishes its first onshore platform, complementing its existing Bermuda- and Cayman-domiciled operations. Independent Life will continue to operate under its existing brand following the close of the transaction, preserving the relationships and service standards that settlement planners and their clients rely on. 26North Re intends to build on that foundation, backing the business with long-term capital and proprietary asset origination to accelerate growth.

“This partnership will strengthen Independent Life’s leading franchise and provide the resources to enable consistent competitive pricing for settlement planners and claimants. For the people those settlements serve, 26North Re’s backing reinforces the certainty they have always counted on,” said 26North Senior Partner Cole Charnas. “We look forward to working alongside the management team on the next phase of the company’s expansion.”

With this transaction, 26North Re enters the structured settlement market, a specialized segment of the U.S. insurance industry in which long-dated liabilities, rigorous underwriting standards and disciplined asset management are prerequisites for all participants.

© 2026 RIJ Publishing LLC.

No Rush to Private Credit Among DC Plan Advisors

Few advisors to defined contribution plan sponsors are familiar with “alternative” assets and only a minority favor adding them to the investment lineups of 401(k) plans, according to a new survey of plan advisors by LIMRA, the life insurance/annuity industry’s market research arm.

The comment period on the Department of Labor (DOL) proposal on the topic ended June 1. More than 31,000 comments were submitted in 90 days.

That lack of knowledge and enthusiasms contrasts with the big push by trade associations representing alternative asset manages that was sparked by President Trump’s executive order last August in favor of “democratizing” complex investments that have ordinarily been available only to defined benefit plans and other institutional investors.

“Theres a $14 trillion pool of assets in defined contribution plans. That’s not unattractive for investment managers,” Deb Dupont, assistant vice president, Workplace Benefits Research, Institutional Retirement at LIMRA, told RIJ recently.

“But there doesn’t appear to be a groundswell of demand,” she said. “The energy is coming from the supply side. The [August 5, 2025 Trump) executive order opened the door to relief for the plan sponsors. Now the asset managers are trying to get alts placed in the 401k system.”

Dupont pointed out that, in legislative terms, the current debate over alts, and whether the DOL intends to give plan sponsors a “safe harbor” against lawsuits if they adopt alts, resembles the debate over “Environmental, Social and Governance” of a years ago more than it resembles the discussion seven years or ago around a safe harbor for those plan sponsors who adopt deferred annuities as investment options.

The annuity safe harbor has the force of the SECURE legislation of 2019 and 2022 behind it, she said, while the political foundation for both ESG investments and alts consisted only of executive orders or DOL rules, which aren’t as legally strong as legislation.

Survey findings

The findings of the 4Q2025 survey of 160 financial advisors, 20% of whom receive most of their practice income from advising DC plans, included:

  • Only 16% of advisors were very familiar with the president’s 2025 executive order directing the DOL to re-assess the inclusion of alternate asset classes and investments (alts) in DC plans.
  • Advisors are more knowledgeable about real estate than other non-traditional asset classes, and also more likely to feel that real estate has a place in a DC plan.
  • Just 31% of plan advisors said they fully understand cryptocurrency. Only 8% feel it is appropriate for a DC plan.
  • Most advisors feel that their plan sponsor clients are not aware of developments that may open their plans up to alts.
  • Just under half of advisors feel that alts are too risky for plans.
  • Advisors who specialize in DC plans are more knowledgeable of alts generally, and more open to them.
  • Alts in DC may be a more challenging issue for smaller (emerging market) plans and their advisors.
  • Fewer than half of advisors feel that private equity and credit should be baked into plan menus via any specific proposed vehicle (managed accounts, brokerage accounts, asset allocation fund strategies, dedicated funds).
  • Only 11% said that alts have no place in DC plans overall.
  • 39% felt that cryptocurrency has no place in DC plans.
  • Lack of participant knowledge is advisors’ main concern about including alts in DC investments.
  • Only about a quarter of advisors are likely to recommend private equity and/or credit to their DC plan clients
  • Few advisors feel that plans will rush to incorporate these asset types.

There’s still a lot of uncertainty around the role that alternative assets would play in 401(k) plans, Dupont said. “The public doesn’t necessarily understand that alts would be part of broad investment strategies,” she told RIJ.

That is, big asset managers like Apollo and Blackrock would like to see managers of target date funds or target-date CITs in 401(k) plans allocate five or 10 percent of their diversified assets to “alts” such as real estate, tranches of collateralized loan obligations (CLOs), and other private market assets, as a way to diversify risk and increase account growth.

There’s the rub, or rubs. Plan sponsors are supposed to act in their participants’ best interests, and there’s no solid evidence yet that private market assets would enhance participants’ accumulations. Indeed, it’s believed that private credit’s highest yields are in the past.

Asset managers are determined to place alts in target-date funds or CITs) because plan participants can be defaulted into those Qualified Default Investment Alternatives investments, thus ensuring a significant, permanent demand for alts.

Many alts are securitizations of auto loans, credit card debt, or loans to medium-sized companies. Securitizing these loans mean bundling many of them together, and then using legal structures or financial engineering to turn them into stock-like or bond-like investments that insurance companies, institutional investors, and marketers of target-date investments, can buy.

So no individual plan participant would purchase a stand-alone alt investment. Owners of target fund shares probably wouldn’t know that 10% of their savings might be in alts. The decision to put alts in target date funds would be up to the managers of those funds, and then plan sponsors would follow their advisors’ recommendations on whether to accept that alt-enhanced version of the TDFs.

“The plan sponsor won’t be on the hook for the decision to include or not to include the alternative investment in the plan,” Dupont said. “The plan advisor would be on the hook for selecting the target date fund that includes the alts. Brokerage windows [where plan participants can buy a wider range of curated investments] are another story.”

© 2026 RIJ Publishing LLC. All rights reserved.